


Cloud Contract Could Reshape The Case For Akamai Technologies (AKAM)
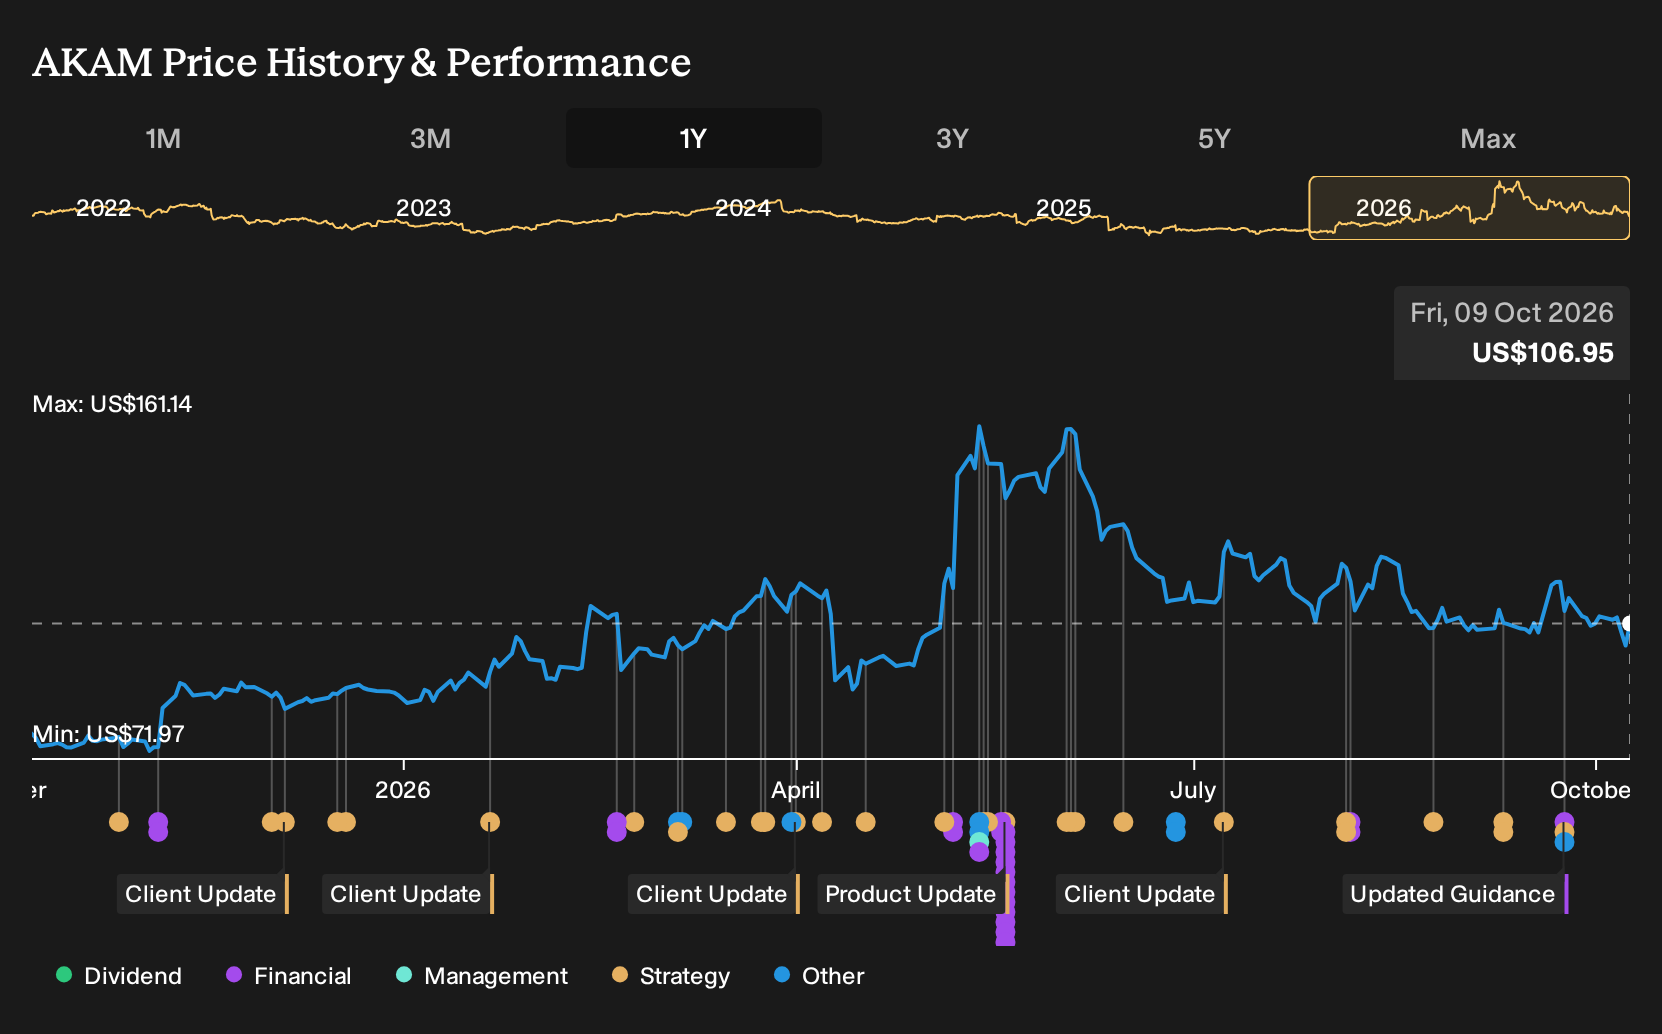
- Akamai Technologies recently secured a seven year cloud contract with Anthropic valued at US$11.6b, alongside planned related capital expenditure of US$5.5b that reshapes its future revenue opportunities and investment needs.
- The Anthropic agreement concentrates a large portion of Akamai Technologies future cloud infrastructure services on a single AI customer, increasing both long term cash flow potential and dependence on that client's deployment pace.
- We will now explore how Akamai Technologies investment narrative could shift as this US$11.6b Anthropic cloud deal reshapes its cash flows.
Scan beyond Akamai Technologies and this Anthropic contract by reviewing 92 AI infrastructure stocks that could also be positioned for the next leg of AI infrastructure demand.
Akamai Technologies Investment Narrative Recap
To own Akamai Technologies today, you need to believe the pivot toward security, cloud and AI infrastructure outweighs the drag from a maturing CDN operation. The Anthropic deal sharpens that bet. It potentially deepens compute scale and relevance in AI workloads, while also tying a bigger slice of future cash generation to one customer relationship and its deployment timing.
In the near term, the key swing factor is execution on heavy compute build out without letting margins erode too far. The biggest risk is that rising capex and concentrated contracts strain cash coverage of debt and compress profitability if client ramps are slower than expected.
The most relevant near term marker for this story is Akamai Technologies upcoming third quarter 2026 earnings call on 5 November. Management may update investors on how the Anthropic contract fits into broader cloud infrastructure services, including capex phasing and expected impact on operating margin in the second half as investments ramp.
For investors, that call is where narrative meets numbers. Progress on security and compute ARR, clarity on customer concentration and any refinement of medium term margin and cash flow guidance may help in assessing whether the Anthropic deal is reinforcing the existing AI infrastructure thesis or simply adding more capital intensity and volatility to the model.
Akamai Technologies analysts are outlining a path to US$7.2b in revenue and US$736.0 million in earnings by 2029. This aligns with forecast revenue growth of 18.7% per year and implies an earnings increase of about US$325.0 million from current earnings of US$411.0 million.
Uncover why Akamai Technologies' fair value indicates a 49% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate take focuses on Akamai Technologies valuation risk rather than contract upside. Before this Anthropic news, the most optimistic analysts were already baking in roughly US$7.9b of revenue and US$1.1b of earnings by 2029. That is a far richer future than the most cautious forecasts, and it shows how widely opinions can differ. Use this spread as a prompt to stress test your own view before leaning toward either camp.
Explore 3 other Akamai Technologies fair value estimates, including one that suggests as much as 49% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Akamai Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Akamai Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Akamai Technologies' overall financial health at a glance.
Looking For More Ideas Beyond Akamai Technologies?
Once you have a view on Akamai Technologies, it can help to line it up against other opportunities on the Simply Wall St Screener so you see where it really fits in your wider watchlist.
- If you want potential bargains with strong fundamentals, start with a 28 high quality undervalued stocks that already filter for quality and pricing support.
- For readers who care most about capital strength and resilience, focus on a list of solid balance sheet and fundamentals (25 results) to compare against Akamai Technologies' financial footing.
- If you prefer to keep risk in check while still looking for opportunities, spend time in a 31 resilient stocks with low risk scores that tilts toward steadier business profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com