


Carlsberg (CPSE:CARL B) Stock Looks Fairly Valued Even After A 19% Gain
Carlsberg shares have delivered a 19.3% return over the past year, and with fresh headlines around brewery closures and new bottling deals, the key question now is whether that price move can be backed up by the brewer's earnings power.
- A 19.3% gain over 12 months puts real weight on the current earnings multiple and raises the issue of how much profit strength the market is already baking in.
- The planned closure of Marston's Brewery in the UK and the expansion of the PepsiCo partnership into Georgia and Armenia may support shifts in Carlsberg's cost base and earnings mix that matter for any earnings driven valuation.
- There is a second opinion on Carlsberg worth weighing. See what analysts think Carlsberg's shares could be worth.
For investors, the debate is whether Carlsberg's current share price is appropriately anchored to the earnings the business is generating today.
If you want a broader watchlist alongside Carlsberg while you weigh that 19.3% one year return against its earnings, a focused screen of 173 high quality undervalued stocks.
Is Carlsberg Fairly Priced on Earnings?
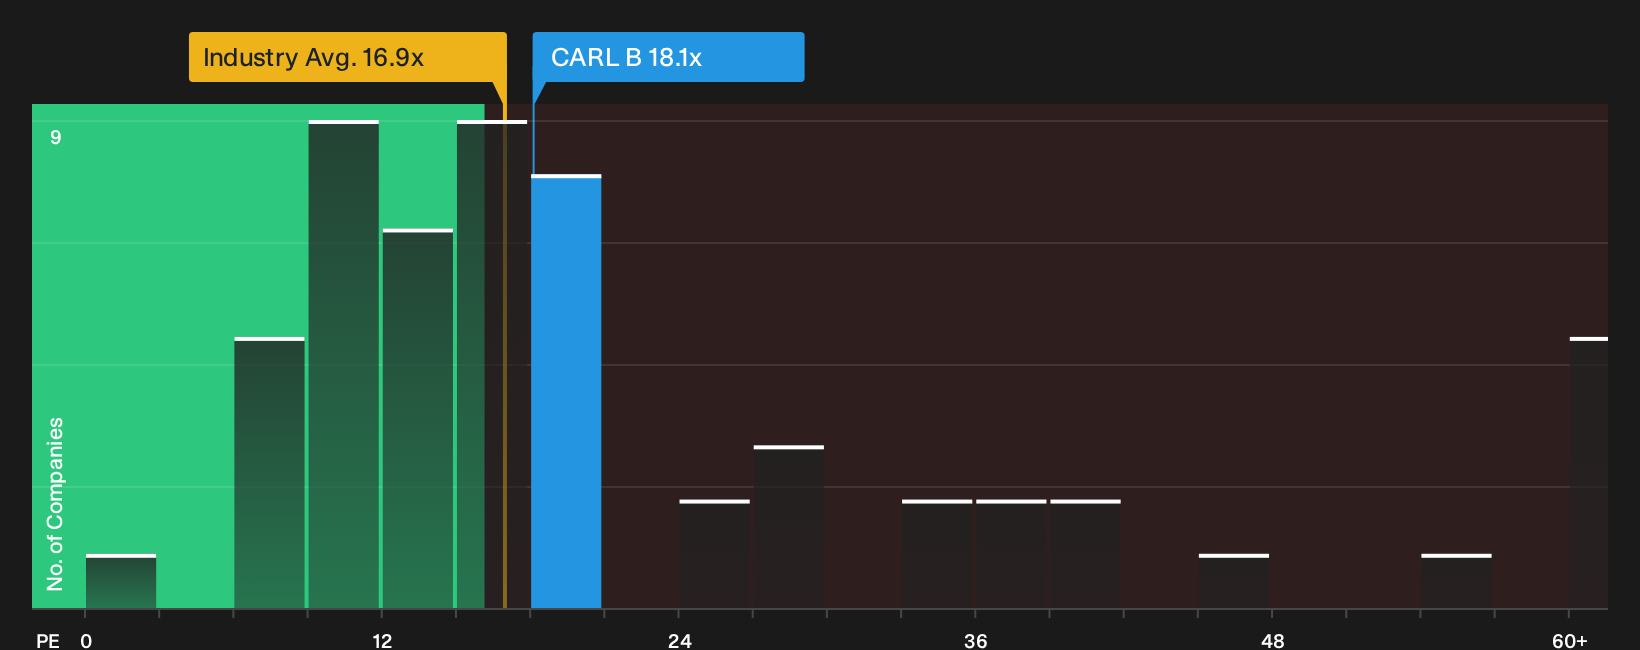
The P/E ratio suits Carlsberg because earnings remain the core yardstick for a mature brewer. Carlsberg trades on a P/E of 18.1x, which is slightly above the Beverage industry average of 16.5x and very close to the peer group at 17.8x. That points to a valuation that is only modestly higher than the wider sector, rather than a stock priced at an extreme.
The fair ratio model, which blends factors like margins, growth expectations, size and risk, suggests a P/E level close to where Carlsberg actually trades today. As a result, the market multiple looks about right rather than clearly cheap or expensive. Because the planned closure of Marston's Brewery and the expanded PepsiCo partnership could reshape the earnings mix over time, the current P/E near its tailored fair level leaves you weighing whether those changes make the existing earnings base feel sturdier or more uncertain. Explore the numbers behind Carlsberg's P/E valuation.
The Carlsberg Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this Carlsberg valuation question leaves off by spelling out which assumptions on future growth, profitability and earnings power would need to hold for the share price to sit meaningfully above or below where it trades today. Each one treats Carlsberg's fair value as a thesis you can track over time rather than a single frozen snapshot on the Community page.
Bulls and bears on Carlsberg are looking at the same multi beverage shift and drawing very different conclusions about what the current price embeds.
Bull case: 17% undervalued
"The acquisition of Britvic strengthens Carlsberg’s exposure to soft drinks and gives the group a more balanced portfolio at a time when beer volumes are under pressure in some markets…"
Discover why this Narrative puts Carlsberg at 17% undervalued.
Bear case: 10% overvalued
"Despite Carlsberg expanding its Pepsi partnerships and entering multi-beverage structures in more markets, these agreements increase dependence on external brand owners and expose the group to rising concentrate pricing, contractual marketing obligations and route to market investments across Europe and Central Asia…"
Explore why this Narrative puts Carlsberg at 10% overvalued.
One more angle on Carlsberg that investors should not ignore
Everything so far has focused on what Carlsberg looks like today, yet professional analysts have already mapped out where they expect the brewer to be a few years from now. This gives you a fresh lens to compare with the current price. Explore where analysts expect Carlsberg to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com