


Applied Materials (AMAT) Stock Looks About Right Following Fresh AI Chipmaking News
Applied Materials has ridden a powerful multi‑year rally in the chip equipment cycle and AI buildout, and the current question for investors is whether a share price above US$500 is adequately grounded in what the business earns today. With the stock now closely linked to big AI manufacturing plans at customers and partners, the key issue is how much of that story is already embedded in its earnings profile.
- Over the past 5 years the stock has returned 301.6%, which puts a lot of weight on whether its earnings can support that kind of repricing.
- Recent partnerships with Intel, Besi and KIOXIA around advanced packaging and AI-focused memory may support expectations for stronger and potentially more capital-intensive earnings streams as those projects mature.
- Your read on Applied Materials is one view; the desks covering it have another. See what analysts think Applied Materials's shares could be worth.
The issue now is whether Applied Materials' current valuation is justified by its earnings power when set against the Fair Ratio benchmark.
If you want a broader benchmark while you assess Applied Materials around AI manufacturing and earnings, you can apply the same lens to 92 AI infrastructure stocks.
Is Applied Materials Fairly Priced on Earnings?
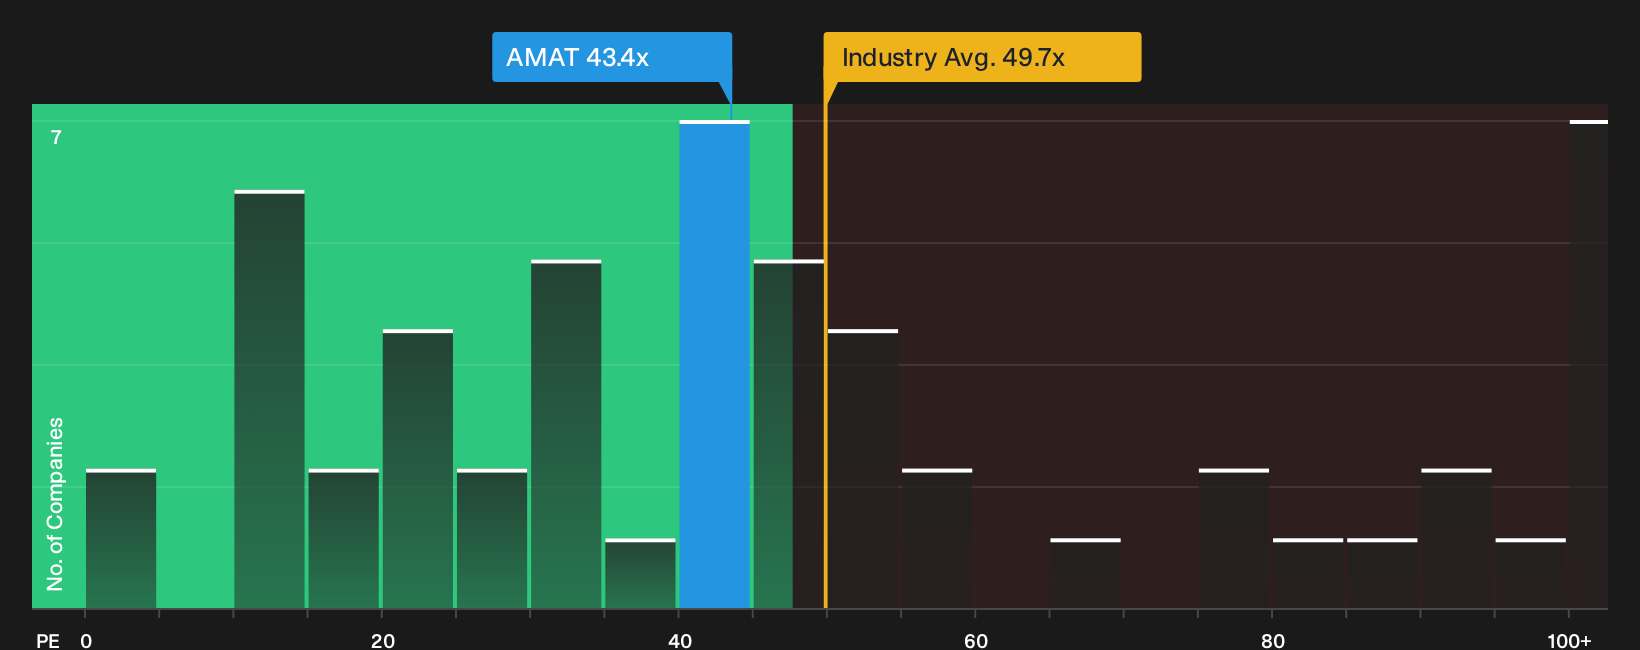
The P/E ratio is a useful lens for Applied Materials because the stock is often evaluated on what it earns today relative to its share price. On this basis, Applied Materials trades at about 43.4x earnings, which is slightly below both the semiconductor sector average near 49.7x and the peer group around 45.4x. This indicates that investors are paying a premium to the wider market for each dollar of profit, but are not paying the highest multiples seen across comparable chip equipment companies.
The Fair Ratio model, which aims to reflect what a P/E might look like once the firm’s growth profile, margins, scale and risk are blended together, points to a level close to where Applied Materials trades today. Because the recent Intel and Besi collaborations have helped focus attention on AI-related tools, the fact that the multiple only modestly trails the broader industry suggests the stronger narrative has yet to move the shares significantly beyond what the current earnings base supports. Explore the numbers behind Applied Materials's P/E valuation.
The Applied Materials Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the valuation question around Applied Materials and turn it into clear, alternative storylines that spell out what would need to happen to growth, margins and earnings for the shares to be worth meaningfully more or less than they are today on the market. Each one treats fair value as a thesis about the business that can be tracked over time, rather than a single frozen snapshot, and they sit on Simply Wall St's Community page.
The community is split on Applied Materials, with one camp leaning into the AI buildout story and another arguing the current share price already reflects a long runway of execution.
Bull case: 21% undervalued
"The EPIC co development platform is scaling, with around US$5b of investment and at least 11 partnerships including Broadcom, Kioxia, Besi…"
Discover why this Narrative puts Applied Materials at 21% undervalued.
Bear case: 17% overvalued
"Management is hiring and investing to double quarterly systems output capacity by 2028 and has nearly doubled manufacturing space already…"
Explore why this Narrative puts Applied Materials at 17% overvalued.
One more Applied Materials check that belongs beside the current price tag
All the multiples and narratives still leave one loose thread: how professionals who model this business see its earnings a few years from now compared with today. Explore where analysts expect Applied Materials to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com