


Ohba (TSE:9765) Stock Faces Profit Squeeze Despite Steadier Revenue Growth
Ohba stock has drifted lower in recent weeks, even as the latest numbers paint a more resilient picture than the share price suggests. The headline this quarter is the squeeze on profitability. Quarterly net income landed at ¥122 million on revenue of ¥3,117 million, well below the earnings power implied by the trailing twelve month basic earnings per share of ¥92.40. In the short term, that pressure keeps traders cautious. Over a longer horizon, the gap between current valuation and discounted cash flow estimates keeps the debate alive over how much of Ohba’s earnings power is already priced in.
Love Ohba’s earnings power but uneasy about the recent squeeze on quarterly profit and the share price drift? Compare this quarter’s story with 23 resilient stocks with low risk scores to see how more resilient businesses with steadier fundamentals measure up.
Q1 2027 Earnings Summary
- Revenue (Q1 2027 vs Q1 2026): ¥3,117 million vs. ¥2,944.284 million (up about 5.9%)
- Net Income (Excl. Extra Items, Q1 2027 vs Q1 2026): ¥122 million vs. ¥124.356 million (slightly lower, down about 1.9%)
- Basic EPS (Q1 2027 vs Q1 2026): ¥7.73 vs. ¥7.81 (effectively flat, down about 1.1%)
- Trailing Twelve Month Net Income Margin (latest vs. prior year): 8.5% vs. 7.4% (margin higher over the last 12 months)
Prefer clean charts instead of scrolling through dense earnings tables and raw figures? See Ohba’s full financial picture with a visual view of valuation in the company report for Ohba.
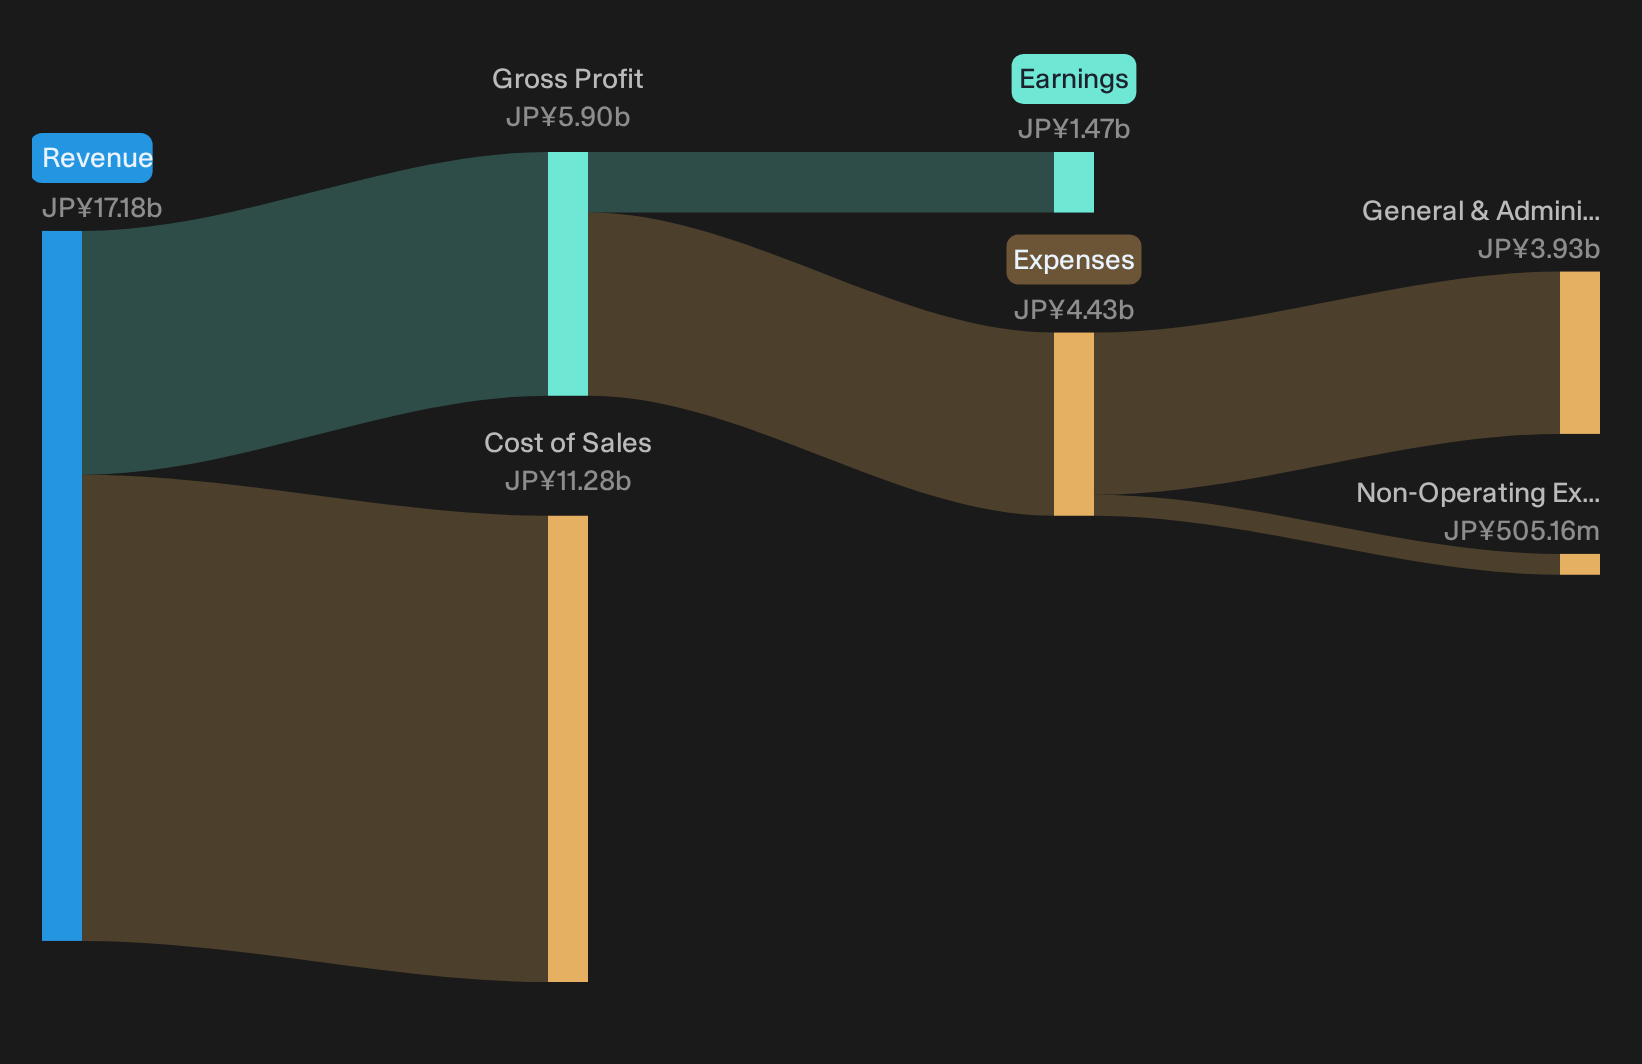
Ohba bullish story leans on steady execution
For anyone backing Ohba as a quiet, steady social infrastructure partner, the latest quarter mostly keeps that story intact. Revenue moved modestly higher year on year, which fits a project based consultant tied to ongoing public works rather than big one off wins. Trailing twelve month net income margin sitting at 8.5%, above the prior 7.4%, suggests that the broader earnings engine still works even if this quarter’s net income and EPS were slightly softer.
Profit squeeze keeps the cautious narrative alive
Bears focusing on profit pressure still have material to point to. Net income excluding extra items slipped a little against last year and basic EPS edged down, which aligns with concerns about bidding pressure and cost creep in consulting work. Short term share price weakness over the past week and month reinforces the sense that investors are not ignoring these risks. At the same time, margins over the last twelve months look healthier, which tempers the view that profitability is structurally broken.
With earnings quality described as high and the P/E sitting above peers, the real question is whether Ohba's cash, debt and payout profile actually support this story. Check the full financial health analysis of Ohba stock to verify the balance sheet strength before you make your next move.Own Your Edge With Simply Wall St
Ohba’s mix of resilient trailing margins and short term profit pressure is exactly the kind of setup that rewards patience and timing. Register for free with Simply Wall St and add it to your Watchlist to track price against fair value so you can wait for the entry point that actually fits your plan. After you commit capital, keep control of the bigger picture with the Portfolio Command Center that cuts through noise and focuses your attention on the updates that matter. For a longer view, lean on the Community to see how other investors are thinking about risks, catalysts and position sizing so you can spot emerging shifts early and stay ahead of the market.
Seeking Alternatives Before The Crowd?
Fresh ideas do not wait. Breakout stories build momentum, quiet winners keep flying under the radar for now, and laggards keep dropping while it matters. Spot the shift and get in early.
- Spot cash generative compounders early by scanning the 12 high quality undervalued stocks that aim to balance sturdy balance sheets with room for sentiment to catch up.
- Chase real earnings momentum instead of hype by reviewing the 39 profitable AI stocks that aren't just burning cash where cash positive operators anchor their growth stories.
- Anchor your watchlist with dependable cash returns by checking the 28 dividend fortresses built around companies prioritising robust income streams.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com