


How Investors Are Reacting To Amazon.com (AMZN) AI Spending Surge
- Recent news around Amazon.com centers on heavy AI infrastructure spending, new Alexa+ hardware and travel booking tie ups, plus continued restructuring in its Stores division and regulatory scrutiny over unapproved health products.
- The mix of capital intensive AI projects, workforce reshaping and compliance pressure gives a clearer view of Amazon.com’s real cost base and execution risks around its long term cloud and consumer ambitions.
- We will look at how Amazon.com's AI centric spending surge, including new Alexa+ devices, reframes the longer term investment narrative.
Compare Amazon.com's AI-focused spending with a curated set of peers by reviewing 92 AI infrastructure stocks that are also investing heavily in chips, data centers, and cloud capacity.
Amazon.com Investment Narrative Recap
To be comfortable owning Amazon.com, you need to believe its heavy AI and cloud spending eventually turns into long running contracts across AWS, Alexa+ devices and new services like travel booking. The key near term swing factor is whether that AI centric capex can keep demand tight enough to support pricing and capacity use across chips, data centers and subscription products.
The biggest current risk sits on the execution and compliance side. The recent FDA warning on unapproved STI products, fresh labor unrest at a New York warehouse and disclosed Bedrock security flaws all point to higher regulatory, safety and reputational pressure that could raise operating costs or slow parts of the business if not contained.
The Alexa+ collaboration with eDreams ODIGEO looks most relevant here because it shows how Amazon.com is trying to turn AI infrastructure into practical, revenue linked use cases. Voice based travel search and booking gives Alexa+ a clearer commercial role and can support engagement on the new premium Alexa tablets that rely on the same assistant.
This ties back to potential catalysts in a straightforward way. For the current investment story to hold, AI infrastructure and custom silicon need broad, sticky workloads. Travel planning through Alexa+, along with shopping tools like Auto Buy and Bedrock agents once hardened, helps support that user and developer activity while the firm works through regulatory issues and workforce reshaping.
Amazon.com Analyst Assumptions And Valuation Bridge
Amazon.com's narrative projects US$1,161.3b revenue and US$163.0b earnings by 2029. That profile assumes revenue growth of 14.4% per year and an earnings increase of about US$27.7b from current earnings of US$135.3b.
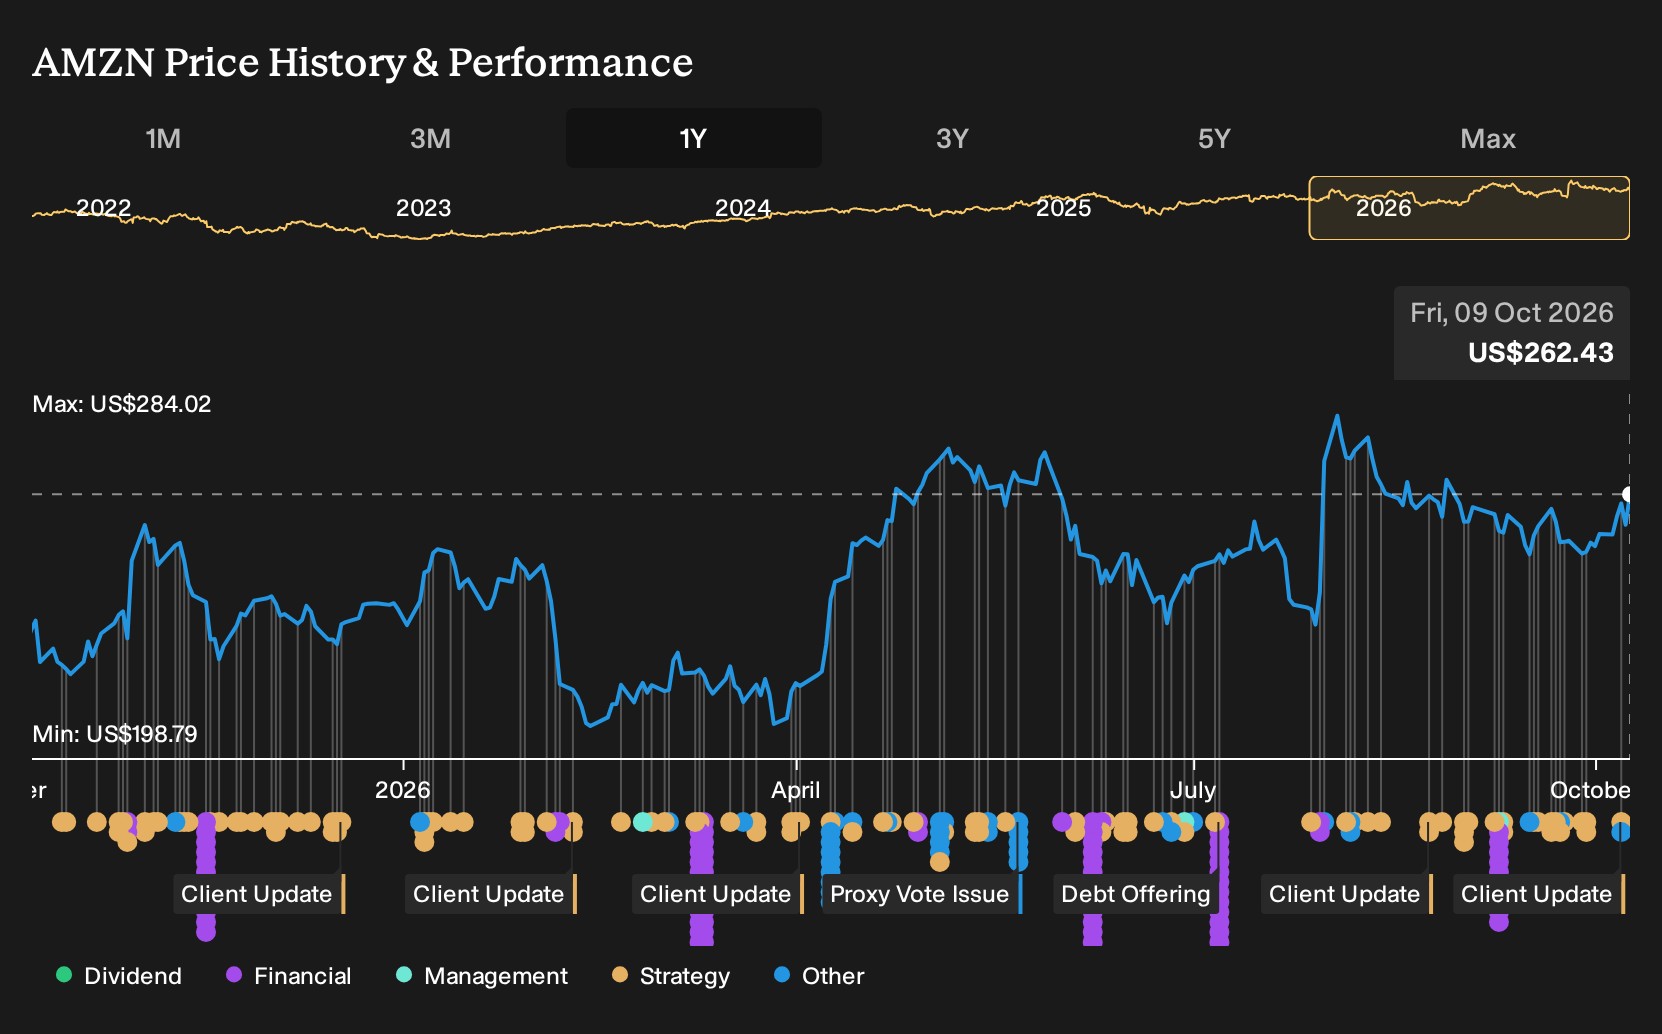
Uncover why Amazon.com's fair value indicates a 26% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Simply Wall St Community members have shared 38 fair value views on Amazon.com, stretching from US$269.78 to US$475.09. You see a wide span here, with some readers calling the stock highly stretched and others eyeing deep value. Set that against heavy AI capex, regulatory scrutiny, and labor disputes, and it is clear opinions can diverge sharply. Use this spread of views as a prompt to stress test your own assumptions and explore several alternative angles before committing fresh money.
Explore 37 other Amazon.com fair value estimates, including one that suggests as much as 81% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Amazon.com research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Amazon.com. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amazon.com's overall financial health at a glance.
Looking For More Ideas Beyond Amazon.com?
Once you have a view on Amazon.com, it often helps to widen the lens and compare it with other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- If you want income on top of potential capital gains, scan for higher yielding payers through 8 dividend fortresses that might complement a growth focused position like Amazon.com.
- If capital preservation sits higher on your priority list right now, you can filter for steadier candidates using a 31 resilient stocks with low risk scores that aims to keep downside swings in check.
- If you prefer focusing on balance sheet strength and underlying fundamentals, you could start with a list of solid balance sheet and fundamentals (25 results) that can sit alongside a large platform stock such as Amazon.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com