


Coty (COTY) Could Be 17% Undervalued On A DCF View
Recent Move In Coty Shares
Coty (COTY) has been back on traders’ screens after its share price closed at US$2.85, with short term returns turning positive even as longer term performance remains weak.
Recent trading in Coty points to a short burst of optimism, with the 7 day share price return of 7.14% and 90 day share price return of 27.23% set against a year to date share price decline of 8.36% and a 1 year total shareholder return that is down 31.98%.
Look beyond Coty’s sharp rebound and compare it with a curated 28 high quality undervalued stocks.
Coty shares have bounced hard in a short span, while longer-term holders are still sitting on deep losses. Does that recent strength improve the risk-reward profile for new buyers, or does it mainly reset the valuation starting point?
Most Popular Narrative: 8% Overvalued
Coty’s most followed valuation storyline pins fair value around $2.65 using a 10.05% discount rate. This sits below the recent $2.85 close and frames the latest bounce as slightly ahead of that thesis.
The current valuation and this narrative’s fairly valued, bullish stance together imply that the share price already reflects both the delivery of ongoing cost and deleveraging targets, and the risk that sales and margin pressure, legal actions, and the Gucci license exit could weigh on future results.
See why 9 investors see Coty as 8% overvalued.
Result: Fair Value of $2.65 (OVERVALUED)
Still, the Coty narrative leans heavily on cost cuts and premium fragrance demand, while recent share loss and the coming Gucci Beauty license exit both threaten that script.
Find out about the key risks to this Coty narrative.
Another View On Coty’s Valuation
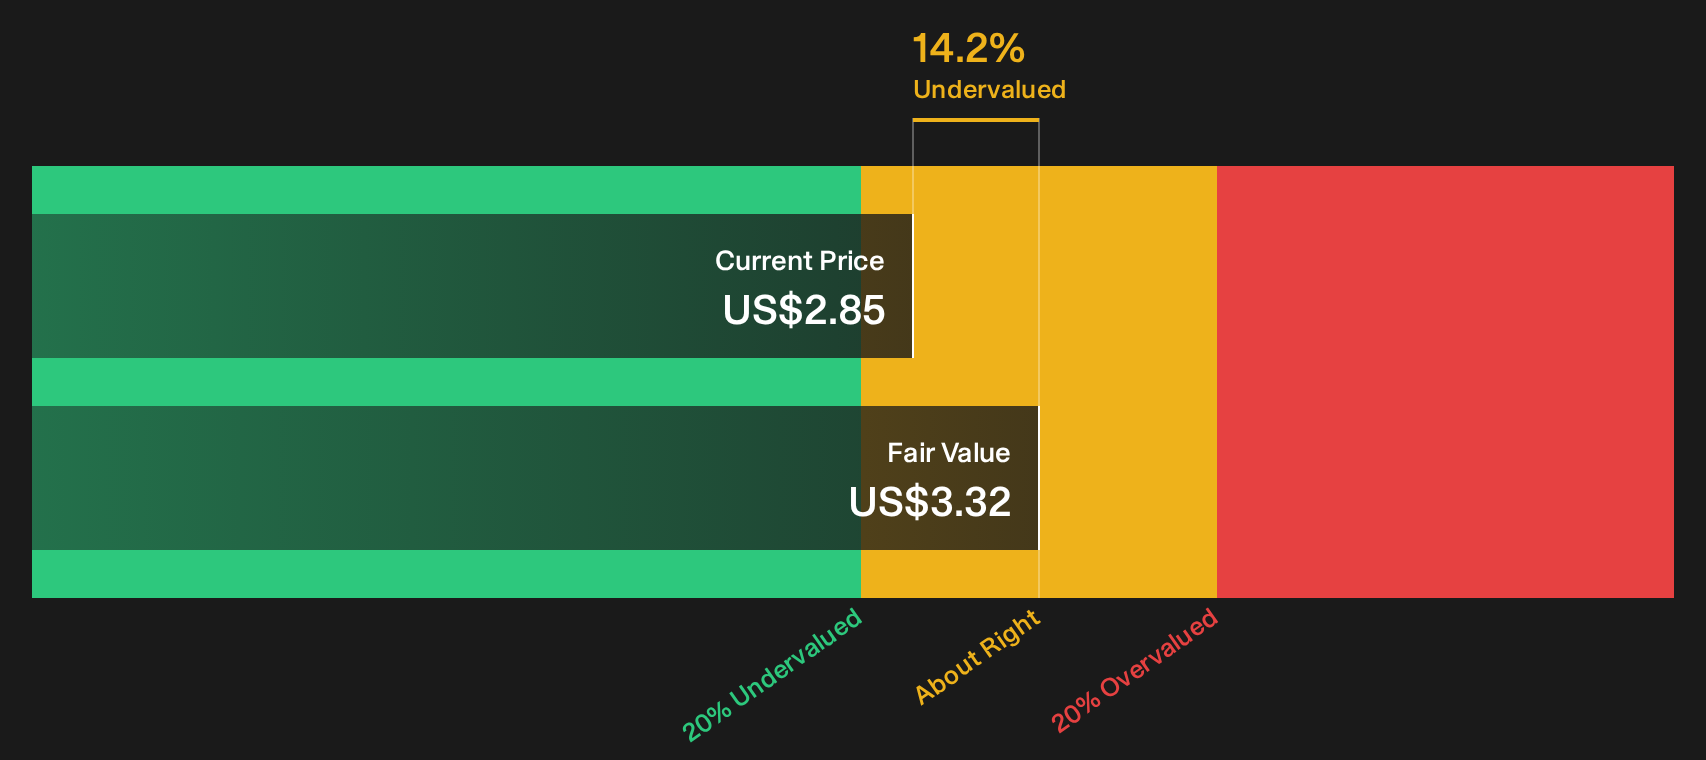
Analysts see Coty as about 8% overvalued at $2.85 versus a $2.65 target, yet our DCF model offers a different perspective. Based on projected cash flows, the SWS DCF model points to a fair value near $3.32, which frames today’s price as a discount rather than a premium. Which assessment do you view as more compelling?
For a closer look at how that cash flow based estimate is constructed, including the key inputs and assumptions that drive the result, Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this Coty setup feels finely balanced, move quickly to test the numbers and pressure test the upside story for yourself. Then review the 3 key rewards
Ready For More Ideas Beyond Coty?
If you stop with Coty, you only see one angle. Cast the net wider with the Simply Wall St screener and line up your next set of ideas.
- Target potential mispricing by scanning a curated 28 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect them yet.
- Prioritise resilience by working through a list of solid balance sheet and fundamentals (25 results) that can help you focus on financial strength when conditions get choppy.
- Get ahead of the crowd by reviewing a 20 high quality undiscovered gems before everyone else starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com