


Should Operating Joint Ventures Require Action From Electrolux (OM:ELUX B) Investors?
- Midea Group and AB Electrolux reported that all three North American joint ventures are now operating, aiming to roughly double regional production of Food Preservation and Fabric Care products while extending into new categories.
- The effort to combine these ventures with cost efficiency, automation and digitalization puts AB Electrolux’s operating model under a real-world stress test on scale, complexity and execution.
- This article examines how AB Electrolux’s investment narrative is reshaped by the expanded Midea partnership and its plan to roughly double production.
Scan how AB Electrolux’s push to roughly double North American output compares with other manufacturers aiming for scaled production and efficiency through our hand-picked list of solid balance sheet and fundamentals (204 results)
AB Electrolux Investment Narrative Recap
To own AB Electrolux, you need to believe that operational fixes and product focus can rebuild an unprofitable appliance group that still carries meaningful brand equity. The Midea joint ventures speak directly to that belief, since they concentrate volume in North America, where local manufacturing and product localization have been a key part of the long term thesis.
The near term swing factor remains execution on cost efficiency, automation and digitalization while demand in Europe, Asia and Latin America stays uneven. The biggest risk right now is that weak pricing power and currency pressures keep margins thin, so the extra North American capacity simply adds complexity instead of earnings resilience.
The most relevant piece of recent news is the confirmation that all three North American joint ventures with Midea are now operating. This connects directly to earlier plans to sharpen AB Electrolux’s portfolio mix toward premium and core products while lifting efficiency through automation and supply chain upgrades.
If these shared factories and product platforms scale as intended, they could support the existing cost efficiency program and help the business absorb tariff and FX shocks more cleanly. If ramp up issues, quality problems or slower consumer uptake emerge instead, the same arrangement could magnify execution risk and keep interest coverage uncomfortably tight.
AB Electrolux Forecasts Behind the Expanded Midea Partnership
AB Electrolux is not just talking about fixes on the factory floor. The current analyst models put hard numbers against that story, and those figures set the bar that the expanded Midea partnership will be judged against.
Analysts currently factor in revenue growth of 3.9% a year over the next three years. This assumes the broader group can absorb weak spots in Europe and Latin America while making better use of its capacity in North America. That pace is not extreme, but it still requires consistent delivery on product launches, pricing discipline and the kind of utilization gains these joint ventures are supposed to deliver.
Earnings today tell a different story. The group is loss making, with current earnings showing a loss of SEK 1.5b and profit margins at a loss of 1.1%. The consensus view looks for earnings to reach SEK 6.0b by 2029. This implies a swing of SEK 7.5b from loss to profit as factories, mix and costs come together. That is a big reset in profitability, even before factoring in the more cautious analysts who only pencil in SEK 4.3b.
AB Electrolux's narrative projects SEK 144.3b revenue and SEK 6.0b earnings by 2029. This assumes 3.9% yearly revenue growth and an earnings increase of SEK 7.5b from current earnings of a SEK 1.5b loss.
For that earnings path to line up with current analyst price targets, the stock would need to trade on a P/E of 7.1x in 2029, compared with a current P/E based on a loss of 17.2x in absolute terms. That implied multiple sits well below the 18.2x P/E quoted for the wider GB Consumer Durables peer group. This leaves less room for disappointment if execution on costs or volume falls short.
The 2029 hurdle is not just about profit. Analysts also assume margins will move from a loss of 1.1% to a positive 4.1% over roughly three years. That kind of margin rebuild puts pressure on everything the Midea partnership touches, from automated lines and shared platforms to quality control and logistics. Any slip in start up efficiency or rework rates at the new North American plants would work directly against that margin lift.
Share count also feeds into the story. Forecasts point to shares outstanding growing 7.0% a year over the next three years. For you as an investor, that means the absolute earnings targets for AB Electrolux have to stretch further just to keep earnings per share on the same path that consensus is expecting.
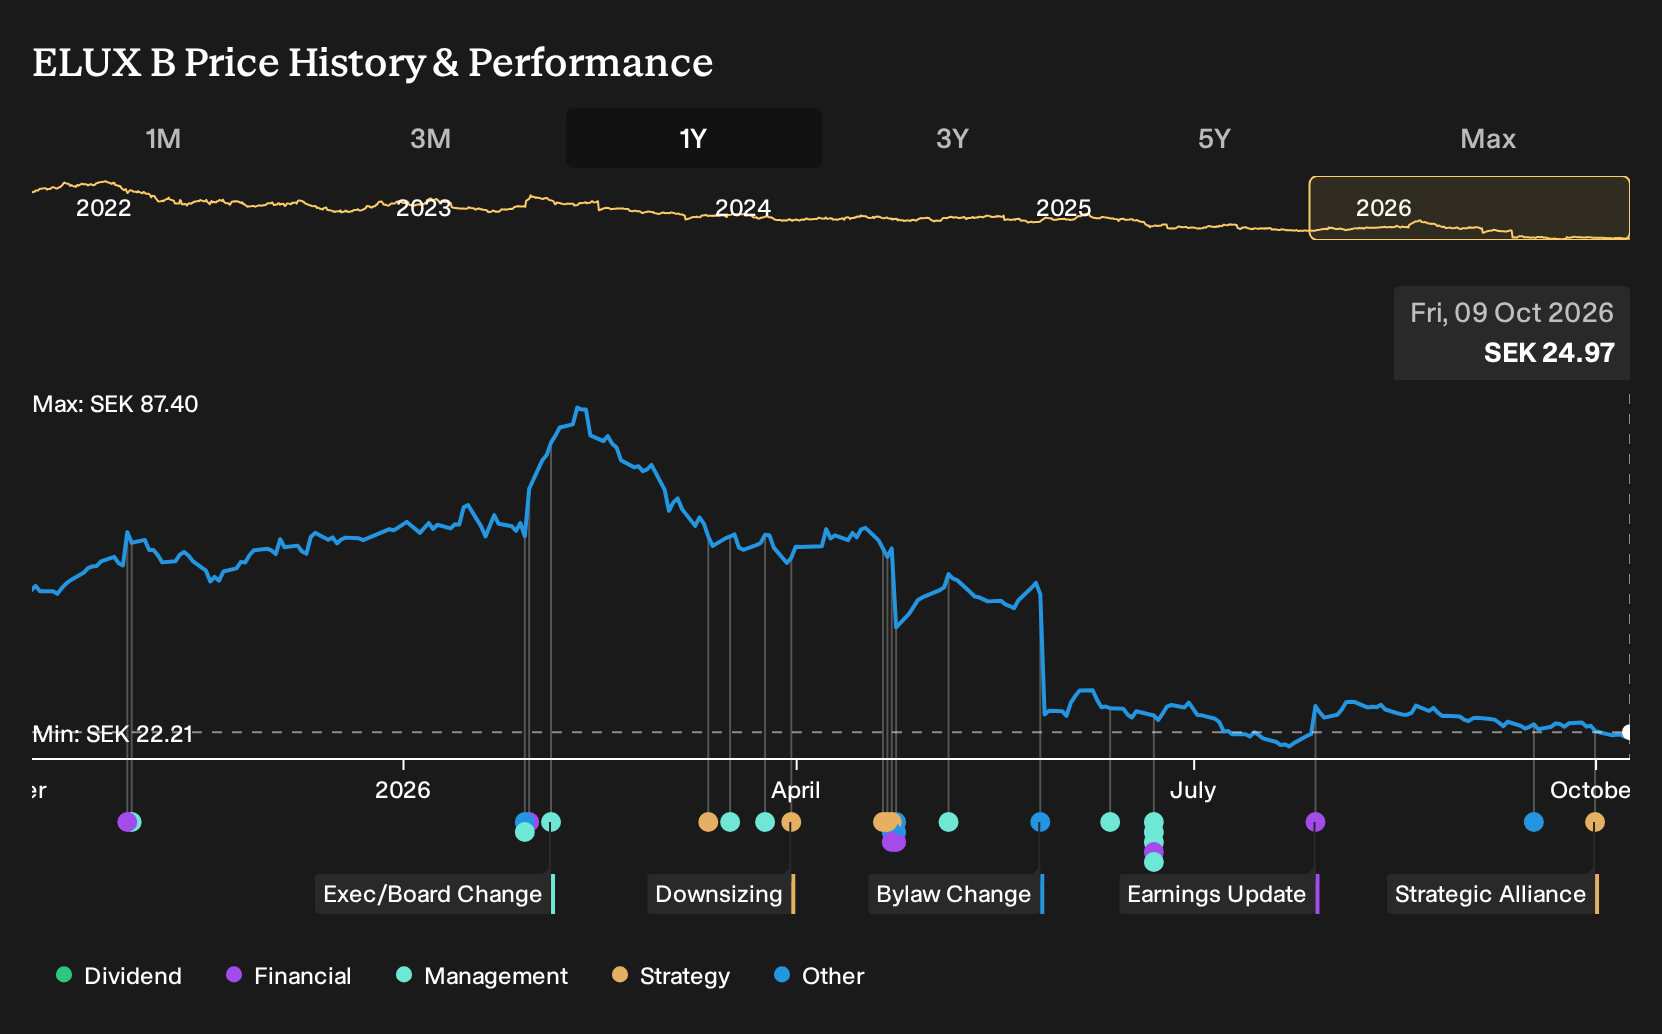
Price targets wrap all of this together. The average analyst fair value sits at SEK 31.85, only 3.5% above the recent share price of SEK 30.73. The tight gap suggests the market already builds in a fair amount of the planned turnaround, including the contribution from Midea ventures, and leaves limited upside in the consensus case if execution on production ramp up or cost cuts stumbles.
There is still a spread in opinion. The most optimistic analysts see value at SEK 39.61, while the most cautious stop at SEK 25.00. That range can be read as a rough map of scenario outcomes, from clean scaling of the North American footprint and smoother margins, through to a world where pricing pressure, FX and operational hiccups in the joint ventures keep returns muted.
For anyone assessing AB Electrolux, these numbers set a clear reference point. The Midea-backed expansion does not sit outside the model; it is one of the main levers analysts are using to justify the swing from loss to profit and the margin rebuild into the next decade.
Uncover why AB Electrolux's fair value indicates a 28% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on AB Electrolux focuses on prolonged tariff pressure. If higher import costs stick, the most cautious analysts think revenue could hover near SEK 125.4b by 2029 with earnings around SEK 4.6b. That is far below the consensus path and was set before this Midea capacity news. You may want to compare both narratives carefully.
Explore another AB Electrolux fair value estimate, including one that suggests it could be worth just SEK31.85!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AB Electrolux research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AB Electrolux. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AB Electrolux's overall financial health at a glance.
Looking for More AB Electrolux Investment Ideas?
If the AB Electrolux story has you reassessing where risk and reward line up in your portfolio, it can help to compare it with other businesses screened on balance sheet strength, valuation and income potential. The Simply Wall St Screener lets you filter for the traits you care about most so you can build a watchlist that matches your own criteria rather than just following headlines.
- For investors who want potential mispricing with fundamentals to back it up, review 174 high quality undervalued stocks that combine quality metrics with discounted valuations.
- If capital preservation and steadier profiles matter more to you than chasing every rebound, start with 222 resilient stocks with low risk scores that score well on financial resilience and lower risk flags.
- Income focused investors who care about getting paid while they wait can scan 223 dividend fortresses that aim for higher yields supported by underlying cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com