


3 Japanese Founder Led Stocks With Up To 42% Earnings Growth
Rich countries such as Japan now face rising borrowing costs, which puts government budgets under real pressure and keeps investors on edge. Founder run Japanese businesses can look relatively simple in this context. Leaders with large personal stakes often focus on disciplined capital use and long term resilience rather than quick fixes. This article walks through three founder led Japanese stocks from our screener that highlight how that approach can show up in practice.
The three founder led stocks below are just a small sample. The wider screen surfaced 101 more businesses with equally compelling stories that are not covered here.
If you want to identify and analyze founder led opportunities that fit your own risk profile, head straight into the Founder-Led Companies screener.
SHIFT (TSE:3697)
Overview: SHIFT is a founder-led Tokyo software testing provider built around its CAT test-management tool, quality platform, and consulting, with smaller nursery and disability-support operations.
Operations: SHIFT generates ¥96,956 million from software testing services and ¥46,302 million from software development, with all ¥150,255 million in revenue coming from Japan.
Market Cap: ¥239.5 billion
SHIFT gives you a founder-led software testing platform in CAT, backed by CEO Hidetaka Kaneko. The stock carries a 36.1x forward P/E, margin pressure, and high share-price swings, so patience may matter for some investors. An important consideration is how quickly profitability can align with the founder’s growth ambitions.
To see how that trade off looks in detail for SHIFT, review the DCF valuation analysis for SHIFT and judge whether growth ambitions outpace the current price.
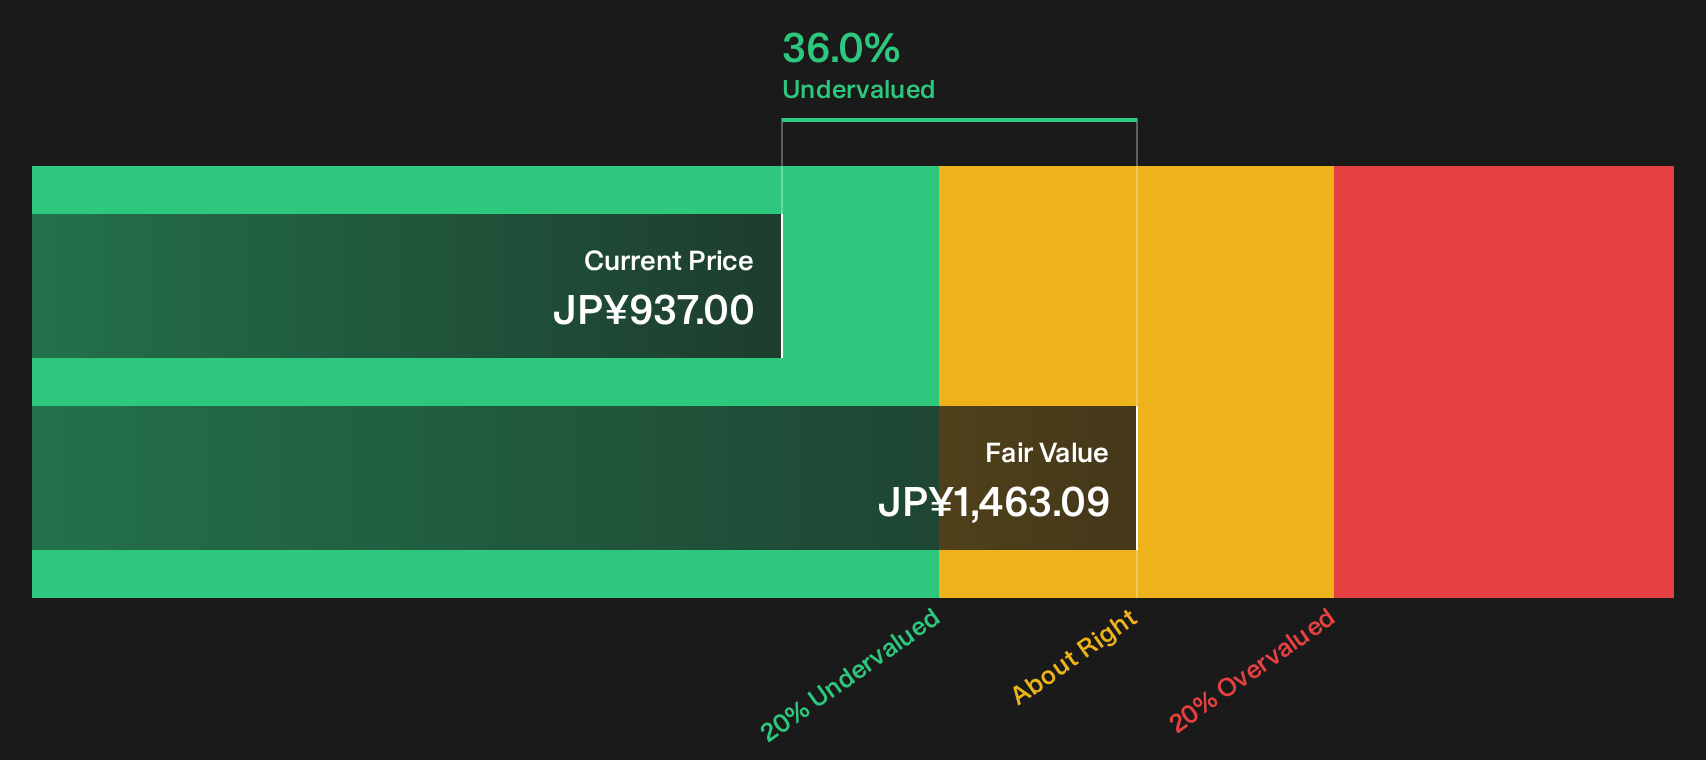
Sansan (TSE:4443)
Overview: Sansan runs a founder-led cloud contact and document management platform in Japan, centered on its Sansan B2B service and supported by Bill One, Contract One, Eight, and data tools.
Operations: Sansan generates ¥46,847 million from the Sansan and Bill One segment, ¥6,720 million from Eight, and ¥415 million from Others, with all ¥53,761 million earned in Japan.
Market Cap: ¥278.3 billion
Sansan ties the Founder-Led Companies theme directly to numbers, with founder-driven cloud services reaching ¥53,761 million in sales and net income of ¥6,778 million. Earnings have been very strong and forecasts indicate expansion that is faster than the broader Japanese market, even with a higher P/E and share price swings. This makes long-term alignment with Masayuki important if one unseen pressure shifts the balance between profit and growth.
If that balance between profit and growth feels finely poised, scan the 3 key rewards and 1 important warning sign to see where Sansan’s momentum could either accelerate or stall next.

CyberAgent (TSE:4751)
Overview: CyberAgent is a founder-led Japanese internet group where Susumu Fujita directly shapes Ameba streaming, WinTicket betting apps, advertising, and games.
Operations: CyberAgent earns ¥478,159 million from Internet Advertisement, ¥269,737 million from Game, and ¥246,561 million from Media & IP, almost entirely in Japan.
Market Cap: ¥635.7 billion
CyberAgent fits this founder-led screen because Susumu Fujita is not just on the letterhead; he personally steers Ameba, WinTicket, and the wider media push that now feed directly into the earnings story.
"ABEMA is now profitable and weekly active users reached 31.37 million in FY 2026 Q3. Any further scaling of original shows such as Kyo-Suki and Shuffle Island plus anniversary-style event programming can give CyberAgent more pricing power on advertising and subscriptions and support higher Media & IP revenue and net margins."
What happens if a single assumption about how much viewers will pay for that extra content starts to shift over the next few years?
If that pricing power really starts to shift, read the full narrative for CyberAgent to see how CyberAgent’s media engine could keep accelerating despite viewer sensitivity.

Seeking Fresh Alternatives Before They Fly
Fresh stock ideas do not stay quiet for long. Breakout potential, early momentum and falling entry windows get caught quickly. Check these curated shortlists before the crowd moves in and consider your options.
- Spot income workhorses that aim to keep paying, then scan the 28 dividend fortresses while yields still look appealing and coverage metrics remain front and centre.
- Look at real business adoption of blockchain before sentiment changes again by reviewing the 20 cryptocurrency and blockchain stocks currently flying under the radar for now.
- Explore automation tailwinds while factories and warehouses continue upgrading by filtering through the 91 robotics and automation stocks before the strongest operators stop looking overlooked.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com