


Does Expanded Loan Capacity Change The Bull Case For NETSTREIT Stock (NTST)?
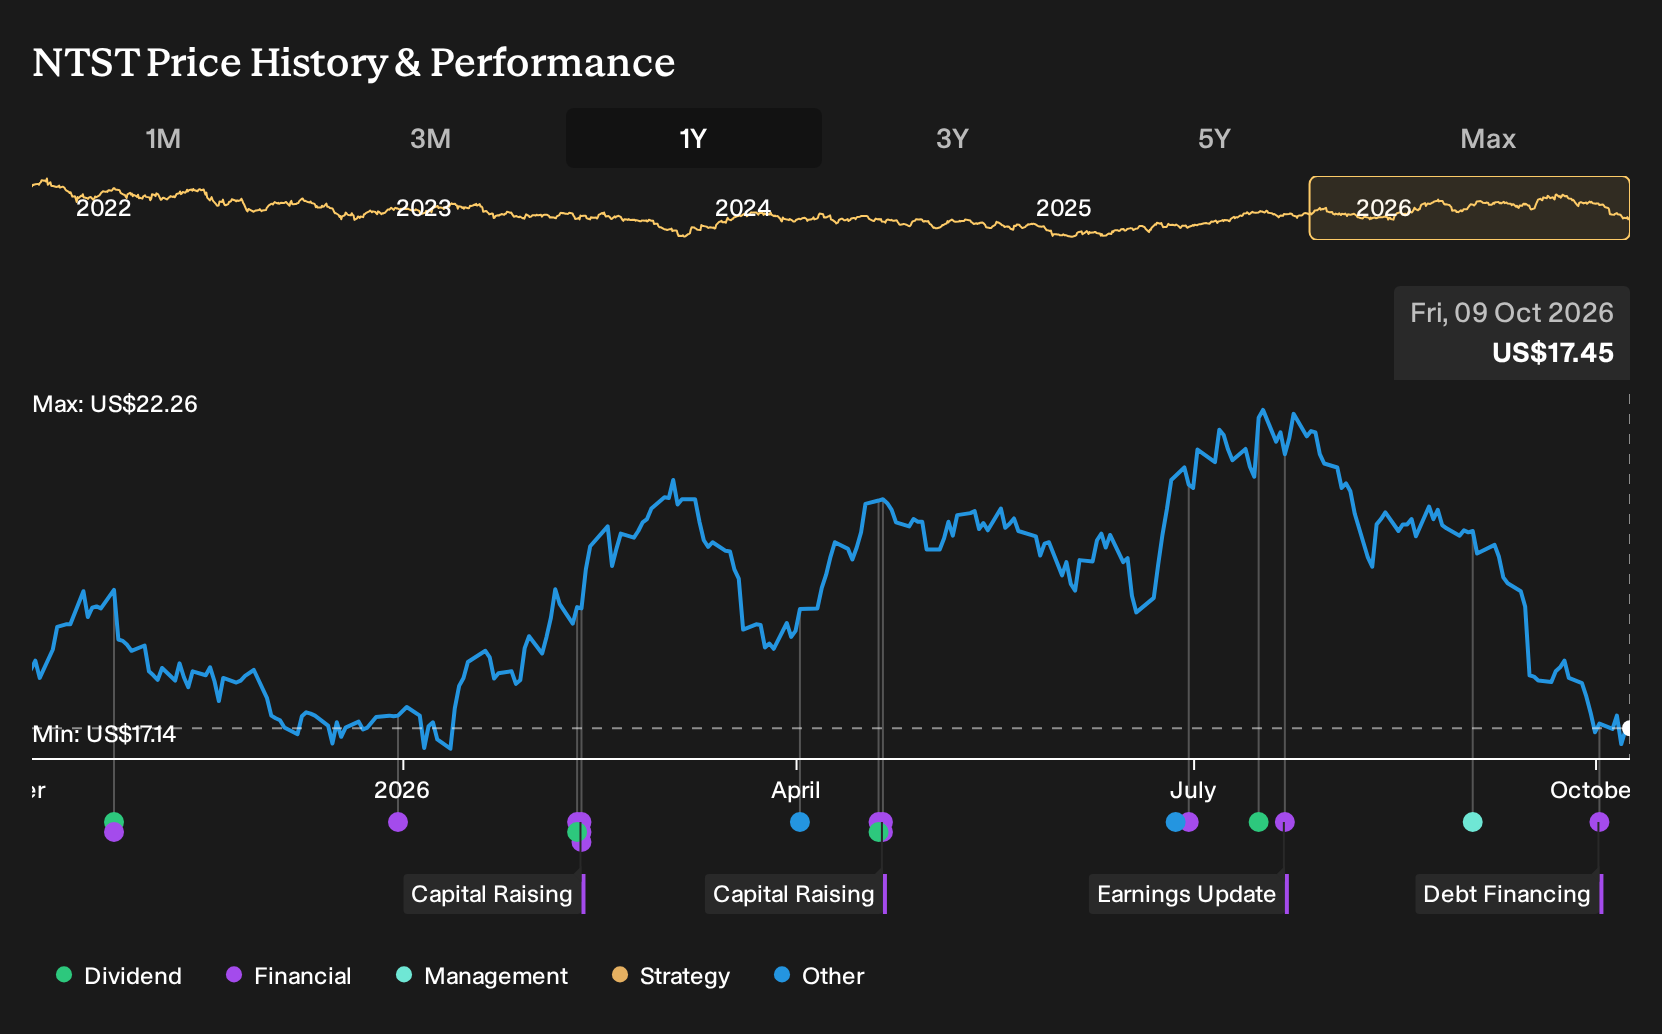
- NETSTREIT amended its term loan agreements in late September 2026, lifting the 2031 and 2032 senior unsecured facilities to US$300 million each and adding a new undrawn US$400 million 2033 delayed draw term loan with ticking fees and defined prepayment premiums.
- The company used the fully funded incremental term loans and the remaining US$50 million under the 2032 facility to retire a US$200 million 2028 term loan and secured lower margin spreads across several credit lines, reshaping its mix of liquidity, funding costs, and debt maturity options.
- We will now see how NETSTREIT's investment narrative is affected by this expanded term loan capacity and refinanced 2028 maturity.
NETSTREIT Investment Narrative Recap
For NETSTREIT to make sense in a portfolio, you need to believe the REIT can keep sourcing necessity focused tenants, recycle weaker assets and put its balance sheet to work without eroding returns. The recent term loan amendments primarily matter because they keep liquidity plentiful while extending maturities, which supports that external investment story.
The key near term swing factor is whether NETSTREIT can maintain attractive spreads between acquisition cap rates and its funding costs as rates shift. The bigger risk is that a high P/E and short interest limit equity issuance flexibility. The latest refinancing changes this risk reward mix but does not overturn it.
The September 28 PNC term loan amendment is the critical disclosure tied to this credit move. NETSTREIT increased both the 2031 and 2032 senior unsecured term loans to US$300 million and added a new undrawn US$400 million 2033 delayed draw facility, while retiring a US$200 million 2028 term loan.
This step aligns directly with the catalyst of deploying US$700 million to US$800 million of net investment in 2026 by preserving dry powder and pushing out near term maturities. It also touches the main risk. Interest payments were flagged as thinly covered, so lower margin spreads on these facilities slightly ease, but do not eliminate, that pressure.
NETSTREIT's current analyst storyline assumes revenue reaches US$386.1 million and earnings hit US$55.1 million by 2029. This reflects revenue growth of 20.8% per year and an earnings increase of about US$41.3 million from the current US$13.8 million base.
Uncover why NETSTREIT's fair value indicates a 31% potential upside to its current price before that discount closes.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community span roughly US$22.87 to US$71.89, which is a wide gap for NETSTREIT. Those private investors are clearly not aligned. When you set that against interest rate risk, high short interest and a premium P/E, it becomes a reminder that opinions can differ sharply, so exploring multiple viewpoints really matters.
Explore another NETSTREIT fair value estimate, including one that suggests potential upside of up to 312% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your NETSTREIT research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NETSTREIT. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NETSTREIT's overall financial health at a glance.
Looking for more investment ideas beyond NETSTREIT?
Once you have a view on NETSTREIT, it can help to compare it with other businesses that fit different risk, income, and quality profiles. A focused stock screener turns that into a targeted search rather than a guessing game.
- For potential mispriced opportunities with solid fundamentals, scan a curated set of 28 high quality undervalued stocks that might offer a more attractive balance of quality and price.
- If capital preservation and steadier profiles matter more to you, narrow your research to 31 resilient stocks with low risk scores that score well on resilience and downside protection.
- When you want healthier finances and cleaner balance sheets at the core of your watchlist, build a custom shortlist starting with a list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com