


Elevance Health (ELV) Stock May Be Undervalued Despite 2027 Medicare Advantage Plans
Elevance Health has delivered a solid share price run recently, and that move puts a spotlight on a simple question for investors who care about fundamentals. Is the current valuation of the stock properly anchored to the earnings the business is generating today?
- Over the past year, Elevance Health has returned 19.2%, which puts fresh pressure on the question of whether the earnings profile can carry the current share price.
- The planned 2027 Medicare Advantage offerings aim to simplify benefits and support members with complex needs, which can influence how investors think about Elevance Health's future profit mix and the durability of its earnings base.
- The analysts covering Elevance Health have run their own numbers. See what analysts think Elevance Health's shares could be worth.
The stock's next move may depend on whether Elevance Health's current earnings are strong enough to justify where the shares trade today.
If you are weighing whether Elevance Health’s recent earnings justify the current share price, it can help to compare that question across 28 high quality undervalued stocks.
Does Elevance Health Look Undervalued on Earnings?
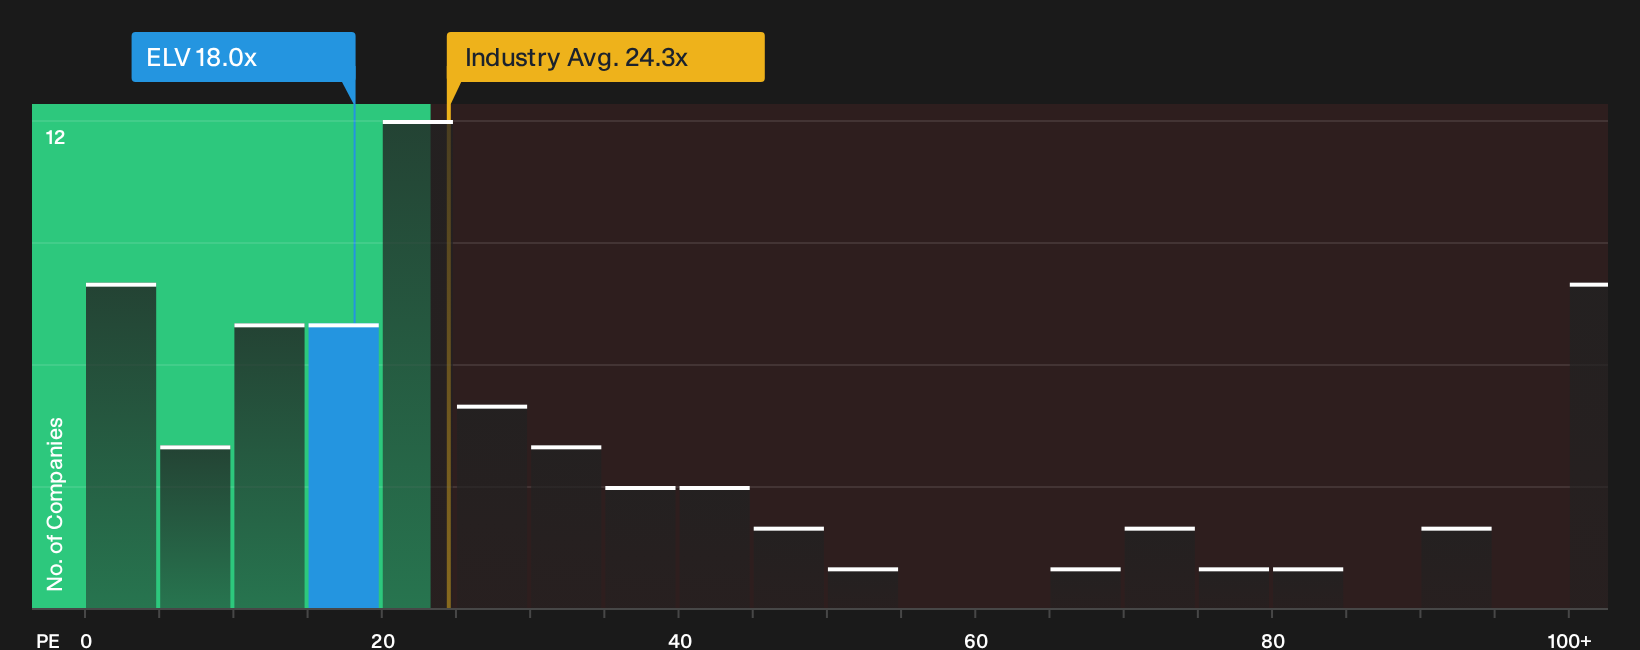
The P/E ratio fits Elevance Health because earnings are a core reference point for how insurers are valued. Right now the stock trades on about 18.0x earnings, which is below the wider healthcare sector average of roughly 24.3x and also under the peer group near 27.8x.
Because the model’s tailored fair P/E is higher than the current 18.0x level, the shares screen as undervalued on this earnings yardstick. With the 2027 Medicare Advantage refresh focusing on more coordinated support for complex members, the current discount suggests the market is not fully pricing in how that product mix could shape Elevance Health’s profit profile over time. Explore the numbers behind Elevance Health's P/E valuation.
The Elevance Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Elevance Health pick up where this valuation puzzle leaves off by spelling out exactly which assumptions on growth, profitability and earnings would need to hold for the shares to be worth materially more or less than today, and they sit on the platform’s Community page. Each Narrative ties its number to a specific view on where Elevance Health's growth, margins and key risks could move next, giving you something concrete to track as new information appears.
Bulls see Elevance Health using its tech stack and services arm to steady margins while bears focus on stubborn Medicaid and ACA cost pressure.
Bull case: 9% undervalued
"Ongoing deployment of Elevance Health’s AI, analytics and digital platforms such as HealthOS and Sydney Health, including automated prior authorization and earlier visibility into medical cost trends, is expected to tighten medical cost management and support more stable net margins and earnings over time…"
Discover why this Narrative puts Elevance Health at 9% undervalued.
Bear case: 5% overvalued
"Although Elevance Health reports that CareBridge and other Carelon programs are producing double digit medical cost savings in targeted groups, persistent elevated utilization in behavioral health, specialty pharmacy and emergency departments suggests these savings may not scale fast enough across the wider book…"
Explore why this Narrative puts Elevance Health at 5% overvalued.
One more Elevance Health angle that could change your view
Everything so far has focused on what Elevance Health looks like today, but there is a separate question about where professional forecasters expect the business to be a few years from now, and how that stacks up against the current price. Explore where analysts expect Elevance Health to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com