


How Investors May Respond To Tomra Systems (OB:TOM) EU Packaging Rules Tighten
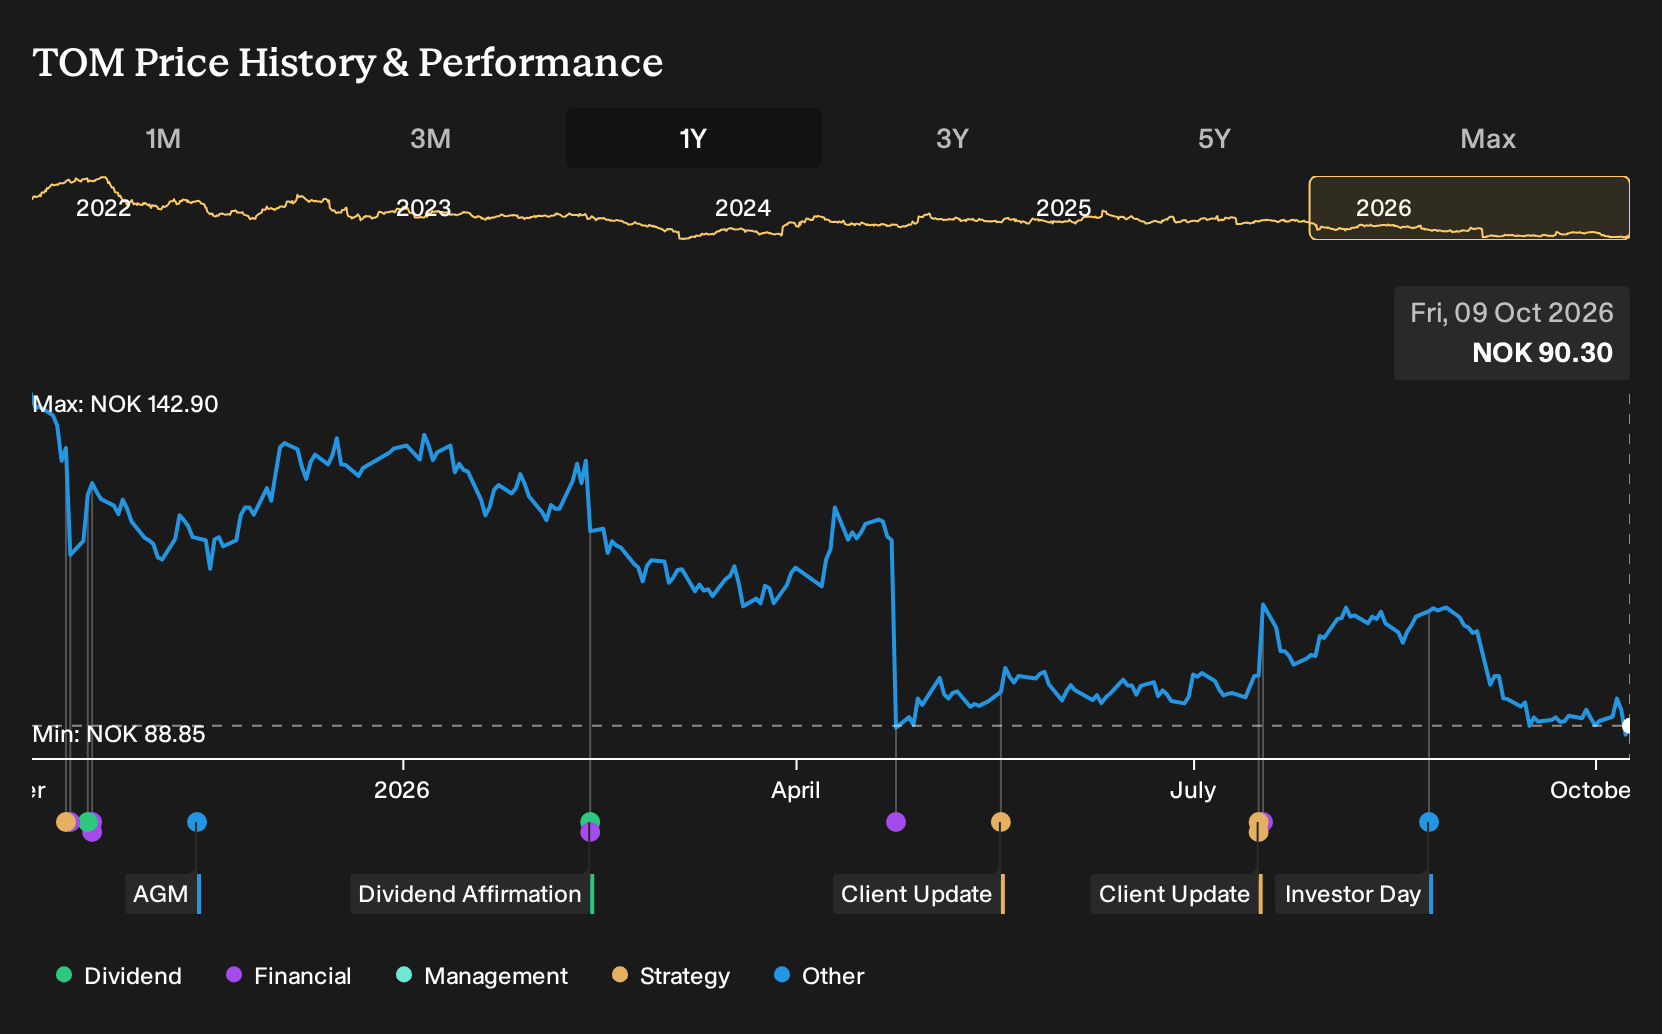
- Tomra Systems is now directly exposed to the European Union's mandatory Packaging Waste Regulation, which took effect in August 2026 and tightens packaging sustainability and reduction rules across member states.
- Insider share purchases by key Tomra Systems executives align with the new regulation and highlight management's conviction in the recycling-focused business model under stricter EU packaging standards.
- We now look at how Tomra Systems' investment narrative is shaped by the EU Packaging Waste Regulation and its recycling focus.
Scan other recycling and circular economy plays that could also gain from tighter packaging rules by reviewing our hand picked 618 high quality undiscovered gems aligned with similar regulatory tailwinds.
Tomra Systems Investment Narrative Recap
To own Tomra Systems, you need to believe tighter packaging rules keep driving demand for its reverse vending, recycling and sorting equipment across Europe and new markets. The EU Packaging Waste Regulation directly supports that idea by hardwiring higher collection and recycling requirements into law. The near term swing factor is whether that regulatory push translates into firm orders rather than cautious, phased customer rollouts.
The biggest operational risk is still weak order intake in Recycling and any further delay in deposit return rollouts in markets like Poland, Portugal and Spain. Overcapacity in virgin plastics and tariff uncertainty can also dull equipment spending, which would matter more for Tomra Systems now that expectations are tied more closely to regulatory driven growth.
In this context, the recent insider share purchases look most relevant. Senior Tomra Systems executives buying stock after the EU Packaging Waste Regulation took effect gives a clear signal that management sees the recycling focused model as aligned with the new rules and capable of absorbing short term order volatility.
For you as an investor, the interest is operational. If regulatory clarity and insider conviction coincide with improving order momentum in Collection and Recycling, that supports the existing catalyst of new deposit return schemes and higher mandated recycled content. If orders remain patchy despite these tailwinds, it would highlight execution and timing risk as the key things to watch.
What The Current Forecasts Assume For Tomra Systems
Tomra Systems' narrative projects €2.1 billion in revenue and €243.9 million in earnings by 2029. This rests on analysts assuming 13.5% yearly revenue growth and earnings rising about 3x from €83.0 million today.
Uncover why Tomra Systems' fair value indicates a 47% potential upside to its current price. This potential upside could narrow quickly.
Exploring Other Perspectives
One optimistic angle around Tomra Systems focuses on how quickly high margin service contracts might build on top of new deposit markets. The most bullish analysts were already pencilling in €2.1b of revenue and €286.7m of earnings by 2029 before this EU Packaging Waste Regulation news. Views clearly differ and could shift as you reassess the story.
Explore 6 other Tomra Systems fair value estimates, including one that suggests as much as 239% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Tomra Systems research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Tomra Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tomra Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Tomra Systems?
Once you have a view on Tomra Systems, it can help to line that up against other opportunities using the Simply Wall St Screener so you can see where the risk and reward trade off feels most attractive for you.
- If you want potential value upside with quality fundamentals, compare Tomra Systems with a 174 high quality undervalued stocks that share strong cash generation and balance sheets.
- If capital preservation is a priority, weigh Tomra Systems against a 222 resilient stocks with low risk scores that may offer a smoother ride through market swings.
- If you prefer sturdier finances over story driven situations, set Tomra Systems alongside a list of solid balance sheet and fundamentals (204 results) and see how the financial strength stacks up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com