


Arcutis Biotherapeutics (ARQT) Following Fresh ZORYVE Data Is The Story Fully Valued
Arcutis Biotherapeutics (ARQT) is back in focus after presenting new ZORYVE data across atopic dermatitis, psoriasis and seborrheic dermatitis at two major dermatology meetings in Europe and the United States.
The fresh ZORYVE data has landed alongside a mixed price picture for Arcutis Biotherapeutics, with an 8.53% 1 day share price return and 11.49% 30 day share price return helping offset a year to date share price decline of 8.34%. Total shareholder return sits at 32.57% over one year and a very large 3 year gain of roughly 7x, pointing to strong long term momentum despite recent volatility.
Scan how Arcutis Biotherapeutics compares to other dermatology and healthcare names by reviewing a hand-picked 34 healthcare AI stocks that could see sentiment shift quickly on clinical or regulatory news.
After a sharp 1 day bounce and a solid 1 year run, yet with Arcutis Biotherapeutics still down year to date, does the current valuation leave more upside for buyers, or does it overly credit the ZORYVE story already?
Most Popular Narrative: 28% Undervalued
Against the last close at $26.58, the most followed narrative pins Arcutis Biotherapeutics fair value near $36.88, setting a clear gap that hinges on how convincingly ZORYVE can scale into broader skin disease markets.
Arcutis is poised to sustain and accelerate top-line revenue growth through continued expansion of ZORYVE indications, targeting large, underserved populations such as pediatric atopic dermatitis and scalp psoriasis, while leveraging broadening insurance coverage and the ongoing shift away from steroid use in chronic dermatologic conditions.
See why 35 investors see Arcutis Biotherapeutics as 28% undervalued.
The narrative work that underpins that $36.88 fair value uses a 7.45% discount rate and assumes Arcutis Biotherapeutics can expand margins materially from current levels while growing revenue faster than the broader US market. Analysts contributing to this view forecast earnings growth of 42.3% per year and see revenue rising about 18.5% annually, with profitability building as ZORYVE scales across psoriasis, atopic dermatitis and seborrheic dermatitis.
Support for the thesis comes from several concrete markers. ZORYVE is the lead franchise, accounting for the bulk of the $463.98m in revenue, with new pediatric and infant indications and a virtual health platform aimed at widening access. The business has recently turned profitable, reports high quality earnings, and carries an estimated future return on equity of 44.7% in three years, which is far above the 20% threshold many investors use as a high bar.
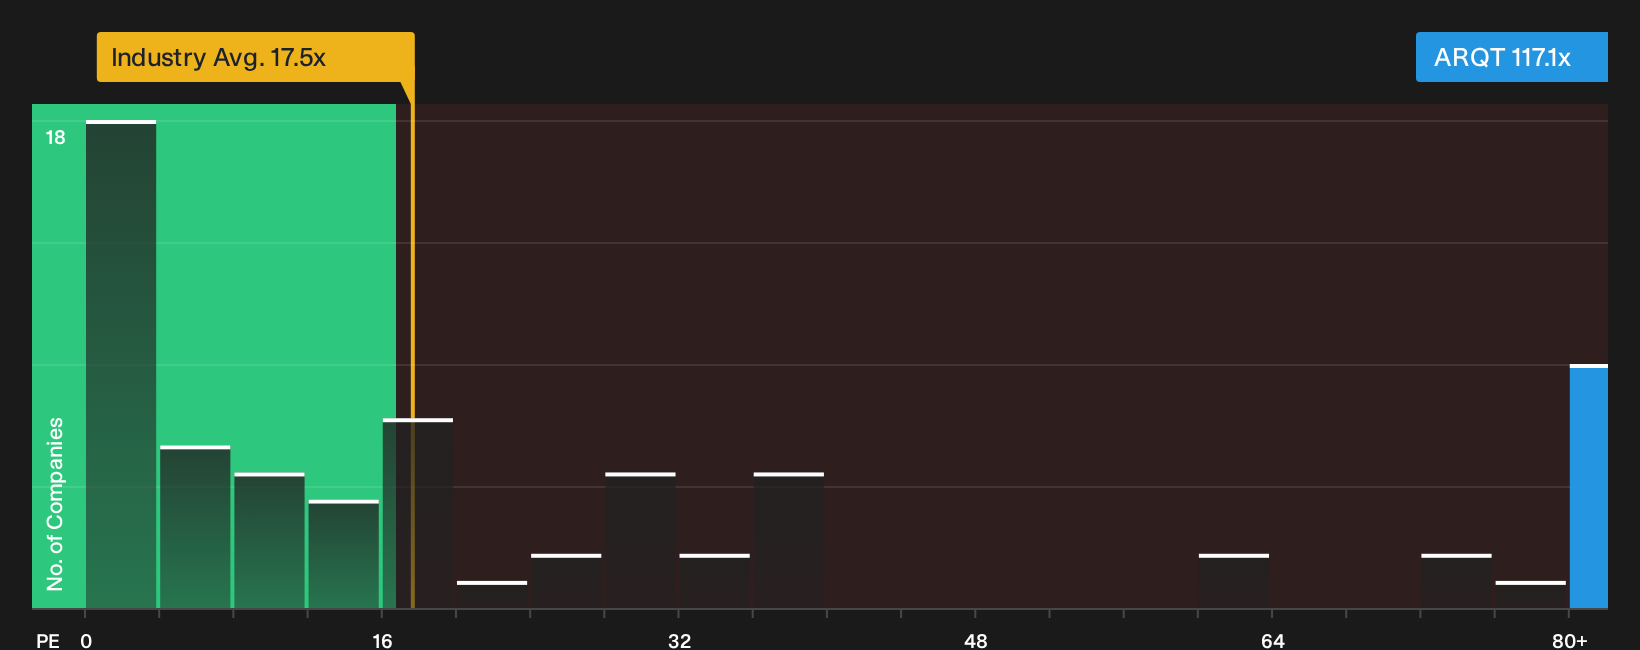
There are counterweights. The P/E multiple of 117.1x is far above both the US Biotechs industry average of 17.1x and an estimated fair P/E of 32x, which suggests the market is already paying up based on current earnings. Concentration in a single flagship product, reliance on higher risk funding sources rather than customer deposits, and recent insider selling all feature in the risk checklist that readers should weigh against the upbeat forecasts and analyst agreement on upside potential.
Result: Fair Value of $36.88 (UNDERVALUED)
Still, the Arcutis Biotherapeutics story leans heavily on ZORYVE execution, and shifts in payer coverage or reimbursement terms could quickly weaken that upbeat fair value case.
Find out about the key risks to this Arcutis Biotherapeutics narrative.
Another View: What Arcutis Biotherapeutics’ P/E Is Telling You
The story shifts once the focus moves from discounted cash flows to the simple P/E. Arcutis Biotherapeutics trades on 117.1x earnings, while the US Biotechs industry sits near 17.1x and the fair ratio is flagged at 32x. That gap loads a lot of expectation into today’s price. If growth or execution slip, how much air is there in that multiple?
Our valuation work comparing current P/E to the fair ratio raises fresh questions about where the market could rotate if sentiment cools. It is worth stress testing your own assumptions against See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does the mixed tone of this Arcutis Biotherapeutics story leave you curious or cautious? Act quickly, review the details yourself, then weigh both sides with 4 key rewards and 1 important warning sign
Looking For More Arcutis Biotherapeutics Sized Ideas?
If Arcutis Biotherapeutics has your attention, do not stop here. Broaden your watchlist and stress test your thinking with a few focused stock ideas.
- Target potential mispriced opportunities by scanning a 28 high quality undervalued stocks that line up strong fundamentals with prices that may not fully reflect them.
- Build a steadier income stream by reviewing a 8 dividend fortresses that offer higher yields while still passing quality and payout checks.
- Protect the downside first by filtering for a 31 resilient stocks with low risk scores that pair resilient balance sheets with more measured volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com