


How Investors Are Reacting To Vault Minerals (ASX:VAU) Mine Contract Extension
- Vault Minerals has extended its mining services agreement with Macmahon Underground at the Daisy Milano Gold Mine in Western Australia, keeping operations contracted through October 2028 and supporting continued production from this core asset.
- The miner now operates as a producer with multiple active sites, solid resource backing, and a debt-free balance sheet, which gives it more flexibility to manage costs and invest in its portfolio than many gold peers that still rely heavily on external funding.
- Now the focus turns to how Vault Minerals' extended Daisy Milano contract might reshape the broader investment narrative around this producer.
Scan beyond Vault Minerals and see how other producers with strong assets and cleaner balance sheets line up in the 4 high quality undervalued stocks.
What Is Vault Minerals' Investment Narrative?
To be a shareholder in Vault Minerals, you need to believe this is now a mature producer story rather than a speculative explorer. The thesis leans on multiple operating hubs in Australia and Canada, a debt free balance sheet, and earnings that analysts expect to grow 12.8% per year, even though forecast revenue growth is a modest 1.3% a year. The extended Macmahon contract at Daisy Milano fits that picture. It reduces execution uncertainty around one key underground asset and helps underpin near term production planning.
In the short term, the real swing factors stay pretty simple. These include operational delivery at Leonora, Mount Monger, Deflector and Sugar Zone, cost control in a high capital intensity sector, and how the market weighs strong long term returns against a P/E of 22.6x that screens above both industry and peer averages. The contract news does not change those core risks. It just makes one important moving part a little more predictable.
Even so, there is a less comfortable angle in the Vault Minerals story once you look closely at ...
There's only one way to know the right time to buy, sell or hold Vault Minerals. Head to Simply Wall St's company report for the latest analysis of Vault Minerals's Fair Value.
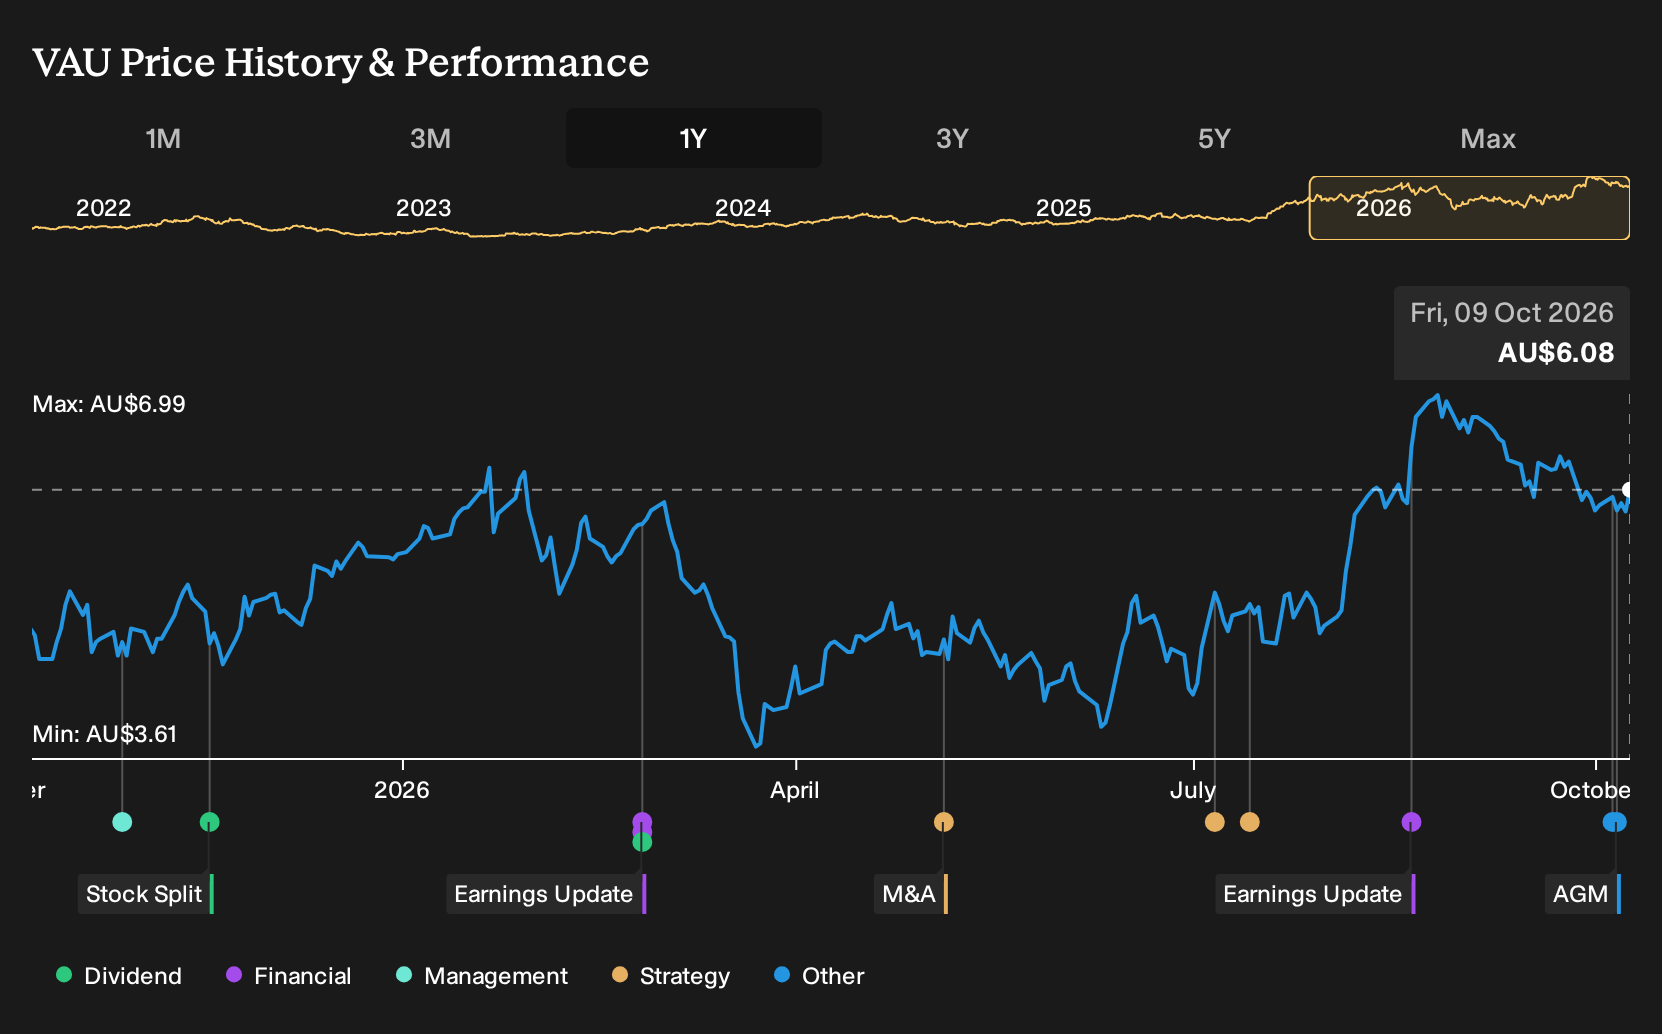
Exploring Other Perspectives
For Vault Minerals, the big swing factor in the alternate view is Sugar Zone. The most pessimistic analysts were already assuming fairly flat revenue out to 2029 while still pencilling earnings of about A$512.0 million, up from A$278.4 million. Those forecasts pre date this Macmahon contract extension, so opinions may change as new information becomes available.
Explore 3 other Vault Minerals fair value estimates, including one that suggests it could be worth just A$6.83.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Vault Minerals research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Vault Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vault Minerals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Vault Minerals?
If the Vault Minerals story has you thinking about portfolio upgrades, it can help to compare it with other businesses that share some of the same financial strengths but sit in very different corners of the market.
- For investors who want potential growth with tight budgets, take a look at 17 elite penny stocks with strong financials that already show stronger fundamentals than many tiny peers.
- If resilience and smaller drawdowns matter most to you, filter for 7 resilient stocks with low risk scores that our models flag with sturdier risk profiles.
- Those who care most about robust finances can focus on companies in the list of solid balance sheet and fundamentals (12 results) and quickly compare leverage and liquidity across the list.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com