


How Earnings Growth And Branch Expansion Will Impact PNC Stock
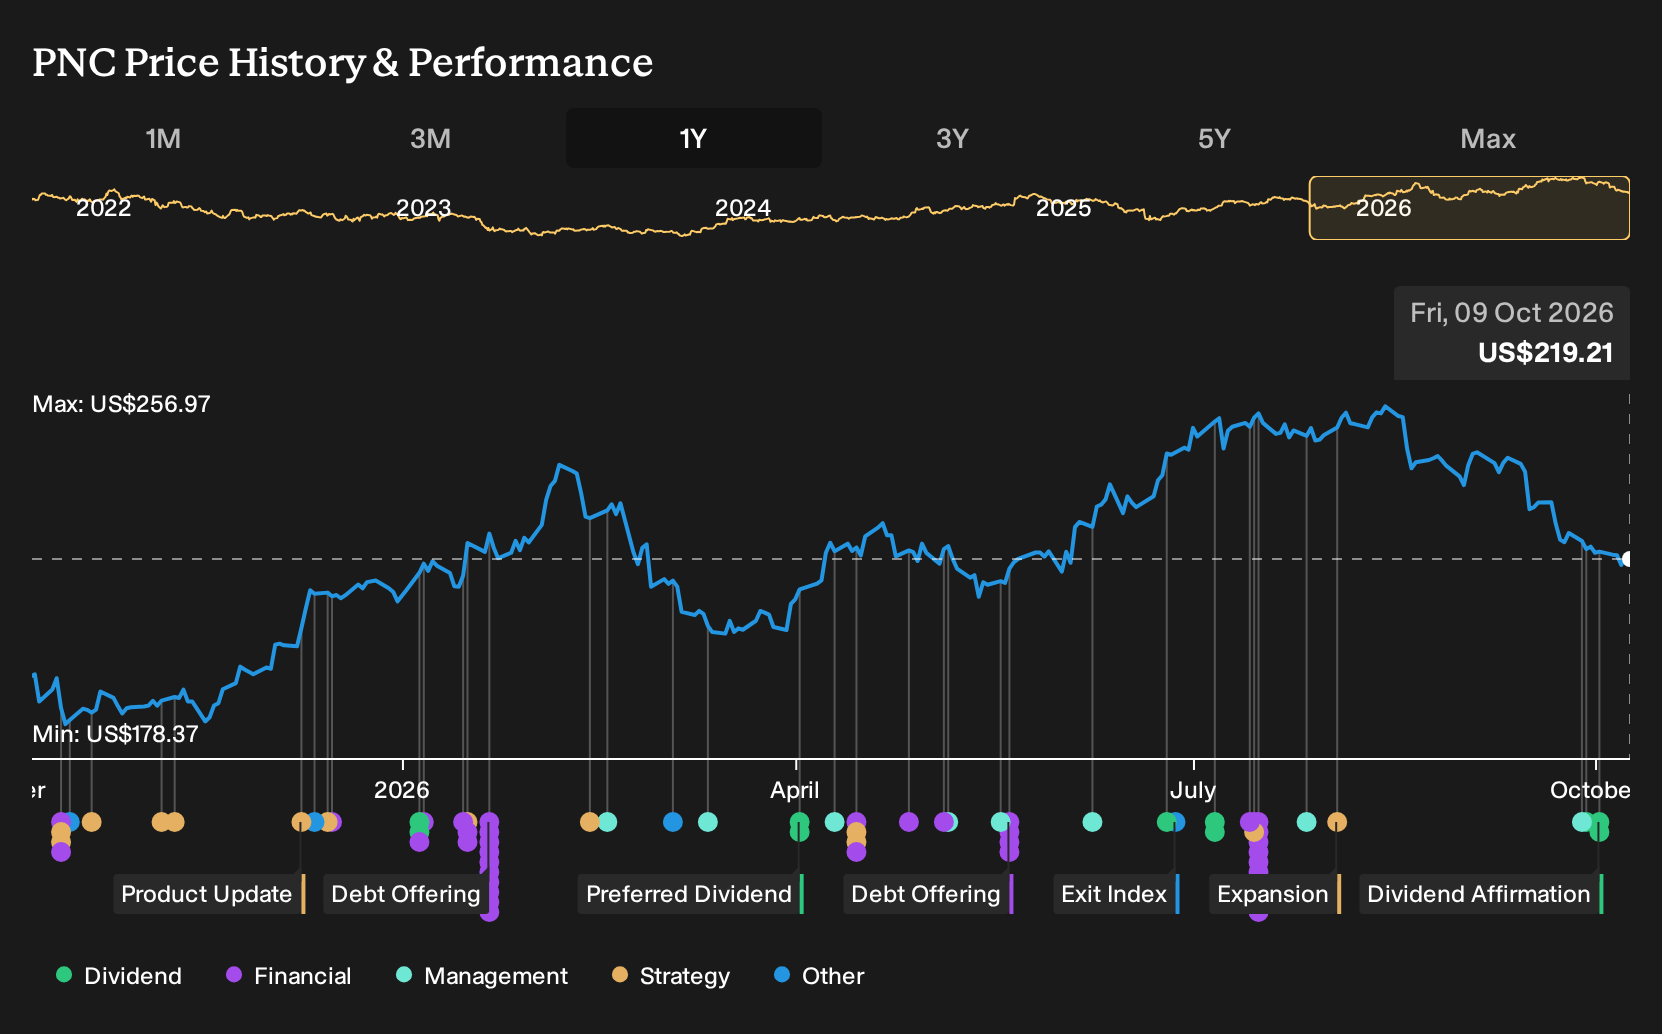
- PNC Financial Services Group has redeemed US$1.25b of 6.615% senior notes one year before their scheduled 2027 maturity and confirmed fresh common and preferred dividends across multiple series with specific payout and record dates through late 2026.
- The combination of early debt redemption and continued cash returns reflects active balance sheet management and an ongoing capital return framework that shapes how income focused investors may view PNC Financial Services Group today.
- We will examine how PNC Financial Services Group's investment narrative relates to expected earnings strength and its planned branch buildout.
Scan how PNC Financial Services Group’s balance sheet moves compare to peers by reviewing a curated set of 31 resilient stocks with low risk scores that prioritize resilience alongside shareholder returns.
PNC Financial Services Group Investment Narrative Recap
To own PNC Financial Services Group, you need to believe its heavy spend on technology, AI and a larger branch footprint can keep earnings and fee income growing without letting costs run away. In the short term, the key swing factor is execution on this efficiency story, especially as fee based areas like capital markets and asset management can cool if client activity softens.
The biggest risk right now is a turn in credit quality that forces higher provisions and eats into those improving net margins. The latest debt and preferred redemptions change the capital mix but do not materially alter that near term equation for you as a shareholder.
The clearest operational signal in the recent news is the early redemption of US$1.25b of 6.615% senior notes due 2027. Retiring this funding a year early slightly reshapes PNC Financial Services Group’s liability stack and frees up future interest expense, which matters if you are watching how much room management has to keep investing in AI and branch expansion.
Viewed alongside the affirmed US$2.00 quarterly common dividend and the planned Triad branch buildout, the debt and Series S preferred redemptions show a balance between funding growth projects, maintaining cash distributions and simplifying the capital structure. The real test remains whether this cleaner balance sheet helps PNC translate its tech and fee income plans into durable earnings while managing credit and market sensitive fee lines.
PNC Financial Services Group's current analyst framework points to US$29.1b in revenue and US$8.7b in earnings by 2029. This is built on assumed yearly top line growth of 6.2% and an earnings increase of about US$1.4b from US$7.3b today.
Discover how PNC Financial Services Group's fair value indicates a 24% potential upside to its current price, a gap that could narrow quickly if sentiment catches up.
Exploring Other Perspectives
Community fair values from 2 Simply Wall St Community members cluster between US$271.55 and US$388.17, which is a wide band for the same PNC Financial Services Group cash flows. You also need to weigh that against risks around fee income sensitivity and credit quality. Opinions clearly diverge, so explore several alternative viewpoints before deciding how PNC fits your own thesis.
Explore another PNC Financial Services Group fair value estimate, including one that suggests it could be worth just $271.55!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your PNC Financial Services Group research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PNC Financial Services Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PNC Financial Services Group's overall financial health at a glance.
Looking for more investment ideas beyond PNC Financial Services Group?
Once you have a view on PNC Financial Services Group, it can help to line it up against other opportunities that match your income goals, risk appetite and time horizon. The Simply Wall St Screener lets you do that in a structured way so you are not just reacting to headlines.
- If capital preservation matters most, start with a focus on resilience and balance sheet strength through a curated 31 resilient stocks with low risk scores that aims to keep downside risk in check.
- If value is your priority, compare PNC Financial Services Group with companies that pair solid fundamentals and attractive pricing by scanning a 28 high quality undervalued stocks tailored for that profile.
- If income is at the top of your list, line up PNC Financial Services Group against a 8 dividend fortresses and see which dividend payers best fit your cash flow needs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com