


TGS (OB:TGS) Draws Interest As Q3 Update Supports A Fair Value Debate
TGS (OB:TGS) is back in focus after its Q3 2026 operational update flagged a normalized Ocean Bottom Node crew count slightly above expectations and the completion of key offshore contracts.
The Q3 update has coincided with a pickup in interest around TGS. The 1-day share price return of 4.17% has reversed part of a 30-day share price decline of 5.53%, while a year-to-date share price gain of 43.62% and 1-year total shareholder return of 84.09% indicate that momentum remains skewed to the upside over a longer horizon.
Scan how TGS compares with other energy plays showing strong fundamentals and contract visibility by reviewing the curated list of solid balance sheet and fundamentals (204 results) in the same segment.
Bulls point to TGS’s recent operational delivery and full Q4 vessel bookings, while bears flag the strong run in the share price. Which story does the current valuation actually support?
Most Popular Narrative: 8% Undervalued
TGS last closed at NOK135, while the most followed narrative sees fair value at NOK146.65 using a 7.32% discount rate. That gap is small enough that your view on future seismic demand and data monetization really matters.
The company is expanding its dataset coverage in high-potential regions such as Brazil's Equatorial Margin, Argentina's Malvinas, and the Gulf of Mexico, positioning itself to benefit from frontier exploration trends as supermajors invest in securing future energy supplies, which may support top-line performance and library value realization. Active cost optimization, including vessel sales, capacity reductions, and integration synergies, has improved EBITDA margins despite revenue softness and may influence net margins and earnings if market conditions change.
See why 11 investors see TGS as 8% undervalued.
Result: Fair Value of NOK146.65 (UNDERVALUED)
Still, the whole TGS story depends on oil company spending not rolling over and on large clients renewing big ticket data deals without long pauses.
Find out about the key risks to this TGS narrative.
Another View: TGS On Earnings Multiples
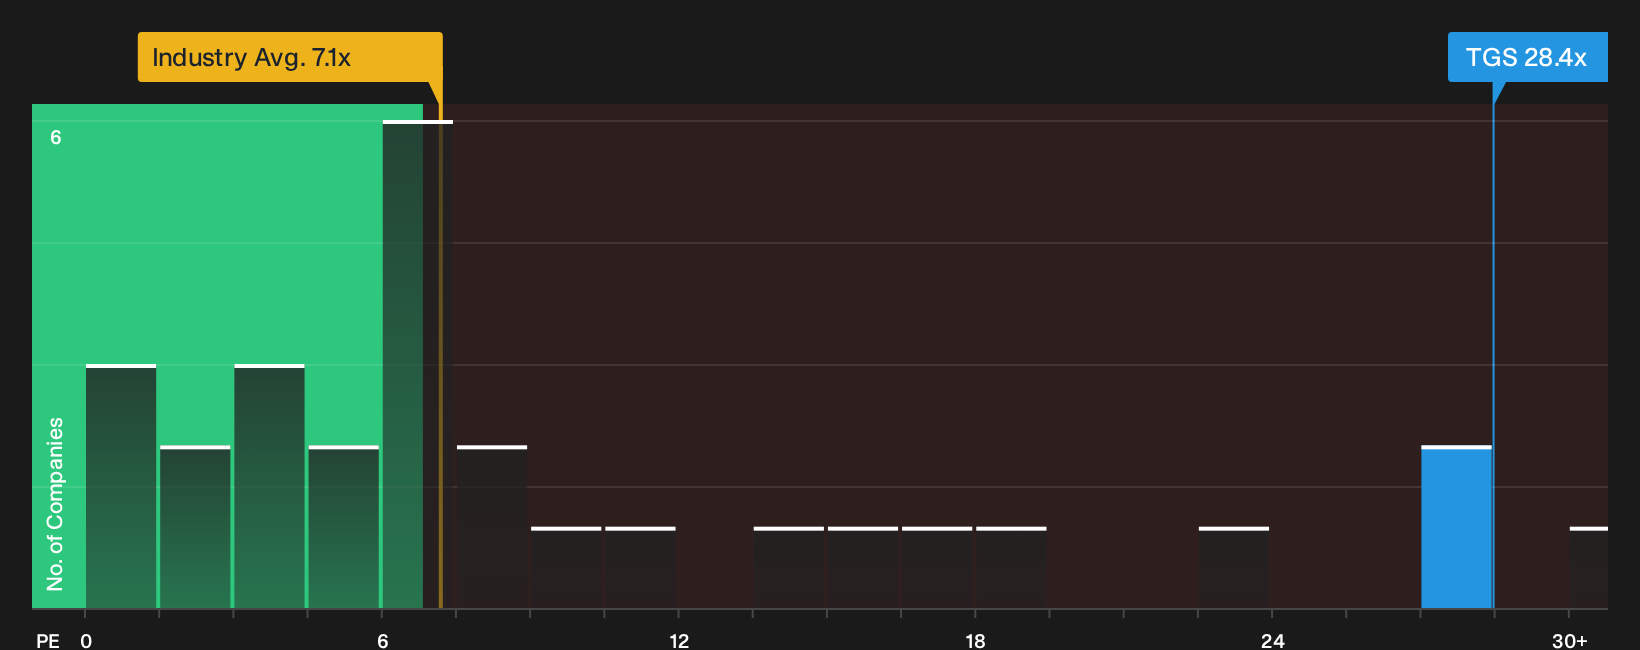
On a simple P/E lens, TGS looks expensive rather than cheap. The shares trade on 28.4x earnings compared with a fair ratio of 18.3x, the Norwegian Energy Services average of 7.1x and peer levels around 9x. That gap points to real rerating risk if expectations cool.
Before leaning too hard on any one method, it helps to see how this earnings multiple view fits into the wider valuation work and risk checks in the full model, then decide which story you trust more for your own process. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of optimism and caution around TGS feels finely balanced, consider acting promptly and stress test the numbers yourself against the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond TGS?
Do not stop at one opportunity. Broadening your watchlist with a few targeted filters can surface companies that better match your goals and risk tolerance.
- Target potential bargains early by scanning companies that screen well on quality and valuation through the 174 high quality undervalued stocks.
- Anchor your income plan with companies that may support regular payouts using the 223 dividend fortresses.
- Focus on resilience and capital preservation first by filtering for businesses that pass strict risk checks via the 222 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com