


Tesla (TSLA) Stock Could Look Expensive Despite Europe Driving Software News
Tesla has been a headline stock for years, helped by strong investor focus on electric vehicles, autonomous driving and AI. With the share price now around US$382.70 after a mixed stretch of returns, the live question for many investors is whether that tag still lines up with what its sales can reasonably support.
- Over the past 3 years the stock has gained about 52.4%, which puts a lot of weight on whether its revenue base and sales trajectory can carry that kind of move.
- Recent developments around Tesla Assisted Driving in Europe, rapid robotaxi expansion in Austin and growing energy and storage projects may support higher long term sales expectations but also focus more of the story on future scaling rather than current car deliveries.
- The analysts covering Tesla have run their own numbers. See what analysts think Tesla's shares could be worth.
The issue now is whether Tesla's current share price can be squared with the level and quality of its sales that investors can see today.
If you want a clearer sense of how Tesla's story around AI, robotaxis and energy compares with other listed businesses, a focused stock screen can be a useful second reference point. You can start with 92 AI infrastructure stocks.
Is Tesla Getting Expensive on Sales?
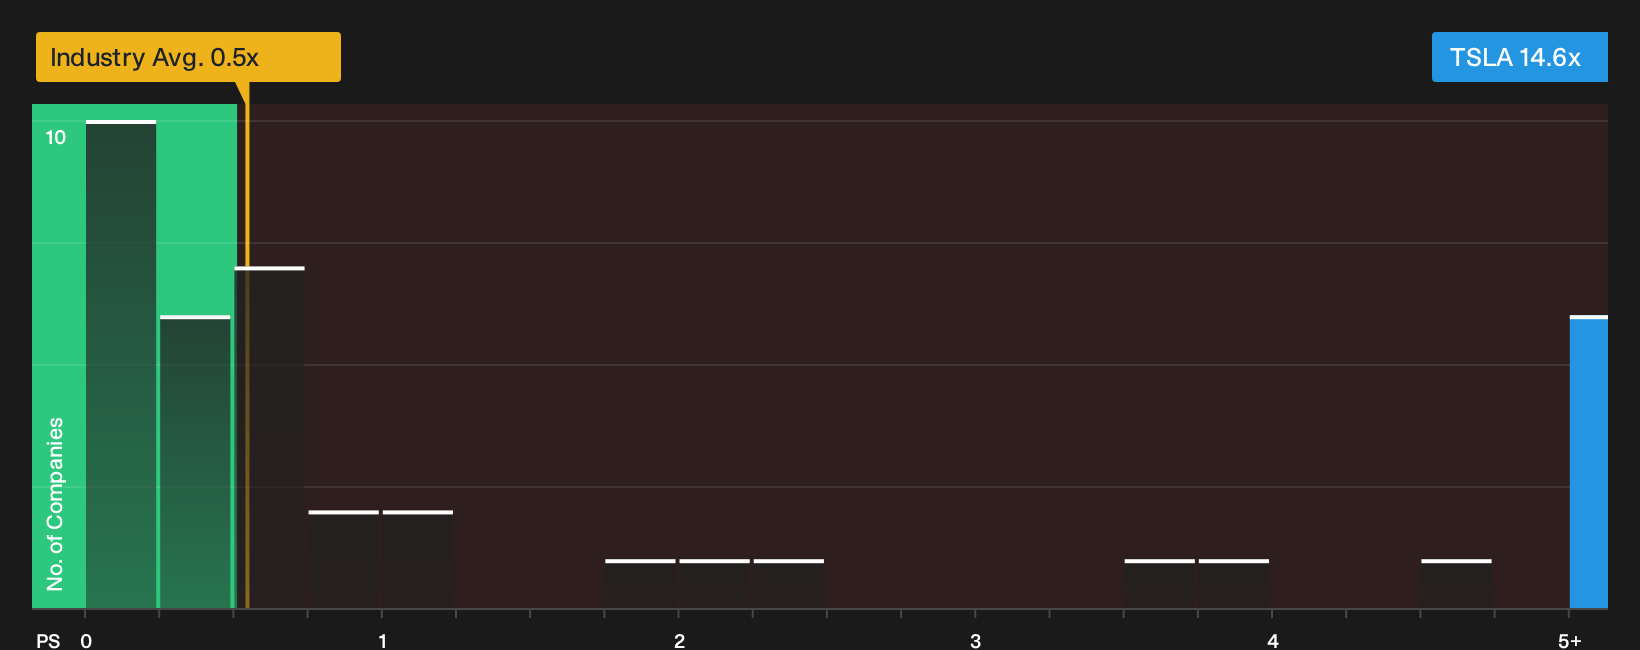
P/S lines up well with Tesla because the story is so tied to how far it can scale its top line rather than what drops into profits today. On this metric, the stock trades on a P/S of 14.6x, against an auto industry average of 0.5x and a peer group around 1.2x. That is a very large premium to both the wider sector and closer comparables.
Recent excitement around robotaxis in Austin, Tesla Assisted Driving in Europe and new energy storage projects helps explain why investors are giving the shares this sort of multiple. The fair-value model that blends Tesla’s growth profile, margins, market size and risk flags the current P/S as above the level that framework would usually attach to a business with these characteristics. The gap is wide enough that it reads more as a warning signal about how much optimism is already in the price than as a precise target. For anyone looking at the stock today, the key question is whether those AI, autonomy and energy narratives justify paying this kind of P/S premium. Explore the numbers behind Tesla's P/S valuation.
The Tesla Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Tesla's valuation puzzle leaves off and spell out which growth, margin and earnings paths would need to play out for the stock to look meaningfully cheaper or more expensive than US$382.70. Each scenario links its figure to a clear view on how Tesla's expansion, profitability and risk profile could evolve, giving you something specific to track on the Community page as fresh numbers and updates come through.
Community views on Tesla are sharply split, with one camp treating it as an emerging AI platform and the other seeing a stretched valuation story.
Bull case: 42% undervalued
"The valuation paradigm has shifted from hardware sales to ecosystem dominance. Just as the iPhone created the App Store economy, Optimus is poised to create the 'Labor Economy'…"
Discover why this Narrative puts Tesla at 42% undervalued.
Bear case: 1176% overvalued
"The company’s price-to-earnings ratio sits at around 330x. At current earnings levels it would take approximately 330 years for earnings per share to cover the price paid…"
Explore why this Narrative puts Tesla at 1176% overvalued.
Before you act on Tesla's valuation, there is one more lever to examine
Big numbers get the attention, yet the people setting Tesla's priorities, incentives and pay structures quietly shape how those numbers develop over time. See who runs Tesla and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com