


BlackRock (BLK) Could Be 18% Undervalued Following Earnings Optimism
Expectations are building around BlackRock (BLK) ahead of its 14 October earnings release, as analysts project higher quarterly revenue and profit and point to a recent pattern of earnings surprises and fee driven momentum.
Recent price action has been steady rather than spectacular, with a 4.47% three-month share price return and a slightly lower year-to-date share price. A one-year total shareholder return that declined 2.37% contrasts with a very large 84.37% gain over three years, suggesting longer-term momentum remains intact as BlackRock rolls out new ETF share classes, expands its role in institutional stablecoin infrastructure and prepares for the upcoming earnings release.
Scan how BlackRock’s mix of ETFs, private markets and fee income compares with other large listed asset managers by reviewing the curated list of solid balance sheet and fundamentals (25 results)
BlackRock now trades only slightly below one estimate of fair value, yet analysts’ targets sit far higher. Is that gap mispricing, or a reasonable cushion given recent ETF flows and fresh stablecoin exposure?
Most Popular Narrative: 17.9% Undervalued
Based on the most followed narrative for BlackRock, the fair value of $1,318.96 sits well above the recent $1,082.39 close. This reflects analysts’ optimism ahead of the earnings date.
BlackRock has evolved from “an indexed asset manager” into a global platform spanning technology, public markets, and private markets, with a more recurring earnings profile and increasing relevance as financial infrastructure.
See why 34 investors see BlackRock as 18% undervalued.
Result: Fair Value of $1,318.96 (UNDERVALUED)
Still, two pressure points could quickly challenge that upbeat BlackRock story: weaker ETF flows if markets turn risk off, and any setback in scaling higher margin tech or alternatives.
Find out about the key risks to this BlackRock narrative.
Another View On BlackRock’s Valuation
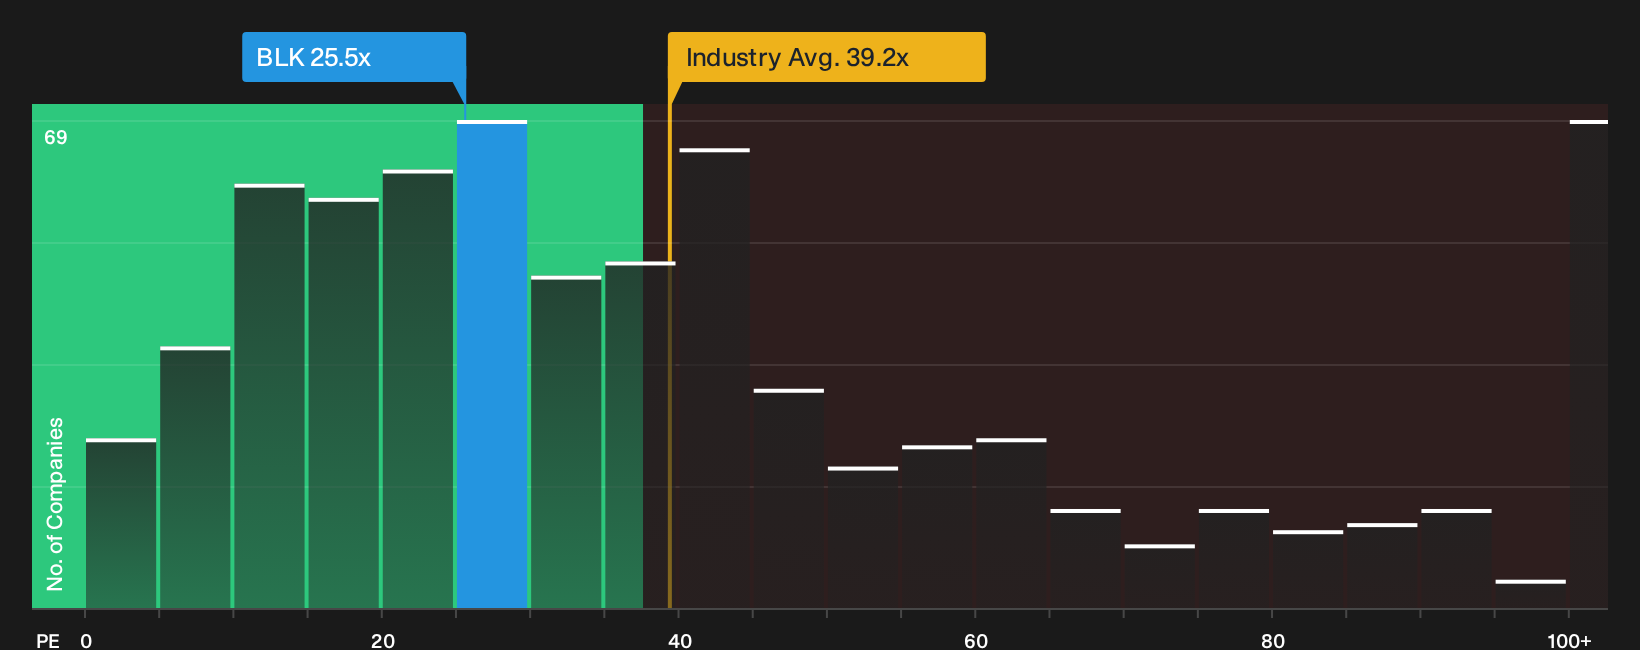
The popular narrative frames BlackRock as 17.9% undervalued based on a fair value of $1,318.96, yet the market is already paying a P/E of 25.5x. That is well above the 18.1x fair ratio and above peer levels at 21.1x, which points to real de-rating risk if expectations cool.
The trade off is clear for investors who follow BlackRock closely. They can either pay today’s richer multiple for the platform story, or wait to see if the share price drifts back toward the fair ratio as sentiment normalises.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around BlackRock is mixed enough that relying on a single storyline seems risky, so move fast, pull up the full dataset, and pressure test it against your own expectations. To see how the positives and negatives stack up in one place, review the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond BlackRock?
If BlackRock feels interesting but not sufficient on its own, broaden your watchlist with a few focused stock ideas that match different investing styles.
- Target more conservative opportunities by reviewing a 31 resilient stocks with low risk scores that aims to keep volatility in check while still giving your capital room to work.
- Hunt for potential mispricing by scanning a 28 high quality undervalued stocks that filters for stronger fundamentals at prices that may not fully reflect them.
- Lock in income-focused candidates by checking a 8 dividend fortresses designed for investors who want yield to do more of the heavy lifting.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com