


Viasat (VSAT) Slides In Sector Selloff, Is It Still 31% Below Fair Value?
Viasat (VSAT) fell 5.8% on Thursday in a broad selloff that hit communication equipment stocks, as investors pulled capital from the sector and punished peers like AAOI and ONDS as well.
The pullback comes after a powerful run, with Viasat’s year-to-date share price return of 91.36% and 1-year total shareholder return of 120.75% pointing to strong momentum. However, the more modest 90-day share price return of 2.11% suggests that pace has cooled slightly.
Scan beyond Viasat and see which communication equipment stocks are also catching strong sector flows with the hand-picked 28 high quality undervalued stocks.
Bulls view Viasat’s recent sector pullback as noise, especially after its 91% year-to-date surge, while bears point to the stock’s recent price cooling and ongoing losses. Which case does the current valuation actually support?
Most Popular Narrative: 31% Undervalued
Against Viasat's last close at $72.01, the most followed fair value estimate of $103.94 points to a sizeable gap that hinges on how effectively the business can turn spectrum, satellites and contracts into cash over time.
The focus on operational efficiency, portfolio review, and progressing integration with Inmarsat in addition to CapEx peaking with the ViaSat-3 program sets up Viasat for positive free cash flow inflection, deleveraging, and earnings improvement as major investment cycles wind down. Rising government and commercial interest in bridging the digital divide, especially in underserved and remote areas, provides a multi-year tailwind through subsidy programs and public/private contracts, supporting stable, recurring revenue streams and margin visibility.
See why 31 investors see Viasat as 31% undervalued.
Result: Fair Value of $103.94 (UNDERVALUED)
Still, the fair value story for Viasat relies heavily on the complex execution of ViaSat 3 and on spectrum disputes that could delay or reduce those cash flow expectations.
Find out about the key risks to this Viasat narrative.
Another View on Viasat’s Valuation
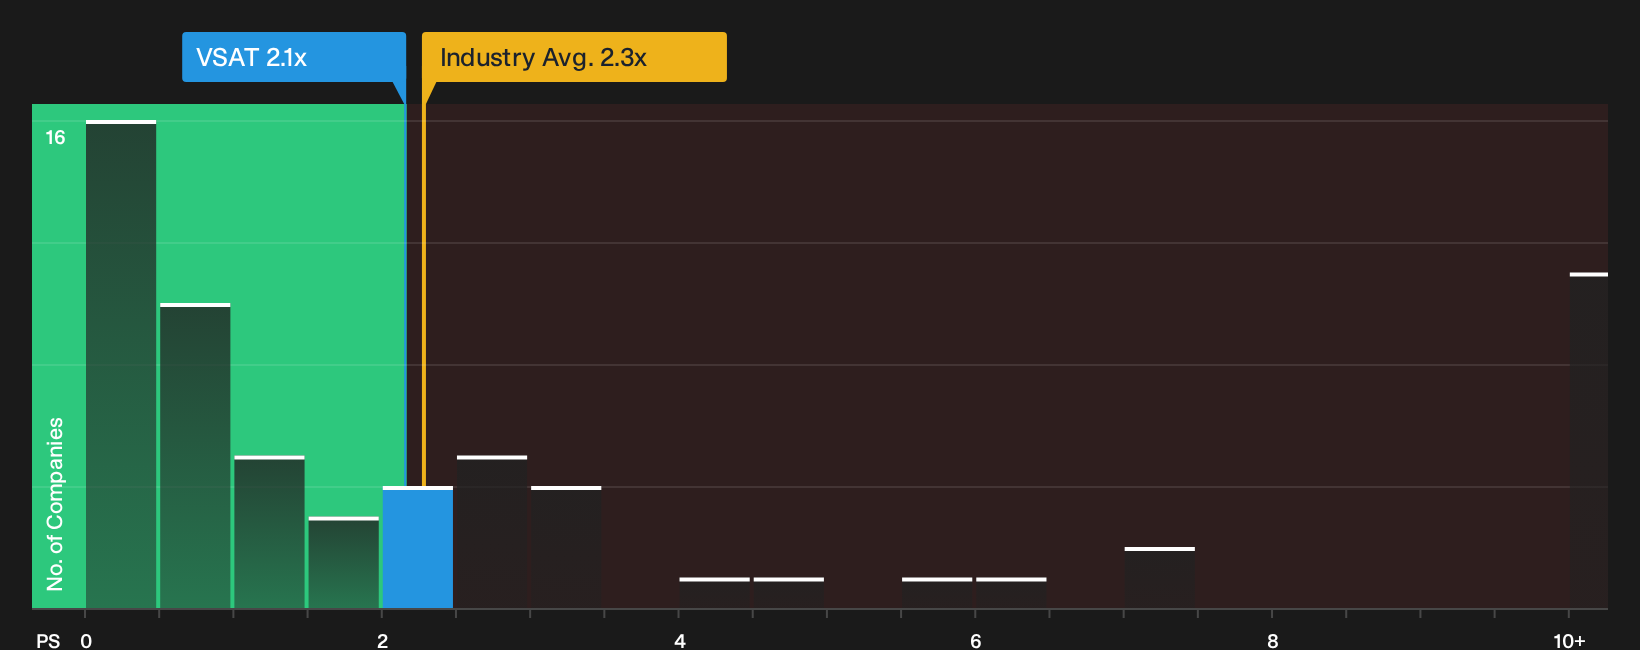
The analyst fair value of $103.94 leans on long term earnings potential and spectrum optionality. A simpler price tag tells a different story. Viasat trades on a P/S ratio of 2.1x, which is slightly below the US Communications average at 2.2x and far below peers at 8.3x, yet still a touch above its fair ratio of 2x. That mix hints at some downside risk if sentiment cools, but also room for upside if the market continues to favor revenue driven stories. Which part of that trade off matters most to you right now?
For a closer look at how this pricing stack compares and where the fair ratio might pull the stock over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by how bullish and cautious this Viasat story sounds at the same time? Move quickly, review the underlying data for yourself, and weigh the single biggest red flags with the 3 important warning signs.
Looking for more investment ideas beyond Viasat?
If Viasat has your attention, do not stop here. Broaden your watchlist, compare different risk profiles, and give yourself more than one way to be right.
Use the Simply Wall St screener to quickly surface focused lists tailored to different styles, so you are not relying on a single story or sector.
- Target higher yield potential with reliable cash generators by scanning the 8 dividend fortresses that may suit an income focused approach.
- Hunt for resilient balance sheets and solid fundamentals by running the list of solid balance sheet and fundamentals (25 results) before the crowd catches on.
- Spot future candidates early by checking the 20 high quality undiscovered gems that combine quality metrics with relatively low current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com