


Is Südzucker (XTRA:SZU) Cheap After Its Return To Profit?
Südzucker (XTRA:SZU) just moved back into profit, reporting second quarter net income of €28 million and first half earnings of €34 million after losses in the same periods a year earlier.
That swing back into profit has landed against a backdrop of firm share price momentum. Südzucker’s stock has a 34.43% year to date share price return and a 23.43% total shareholder return over one year. However, the 3 year total shareholder return is slightly negative, which hints that the recent strength is still rebuilding confidence rather than capping off a long winning run.
Spot opportunities similar to Südzucker’s profit rebound by scanning our hand-picked list of 174 high quality undervalued stocks with solid cash generation and balance sheets.Südzucker has turned loss into profit and the share price has already reacted. The real test now is whether the current valuation still leaves enough room for a rationally priced business story.
Most Popular Narrative: 2% Overvalued
Südzucker’s most followed valuation story puts fair value at €11.98, very close to the last close of €12.22, which leaves little implied discount in that framework.
The analysts have a consensus price target of €11.98 for Südzucker based on their expectations of its future earnings growth, profit margins and other risk factors. However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of €15.0, and the most bearish reporting a price target of just €9.0.
See why 9 investors see Südzucker as 2% overvalued.
Result: Fair Value of €11.98 (OVERVALUED)
Still, Südzucker’s story can change quickly if sugar prices weaken further in the EU or if higher production costs continue to pressure already thin segment profits.
Find out about the key risks to this Südzucker narrative.
Another View On Südzucker’s Value
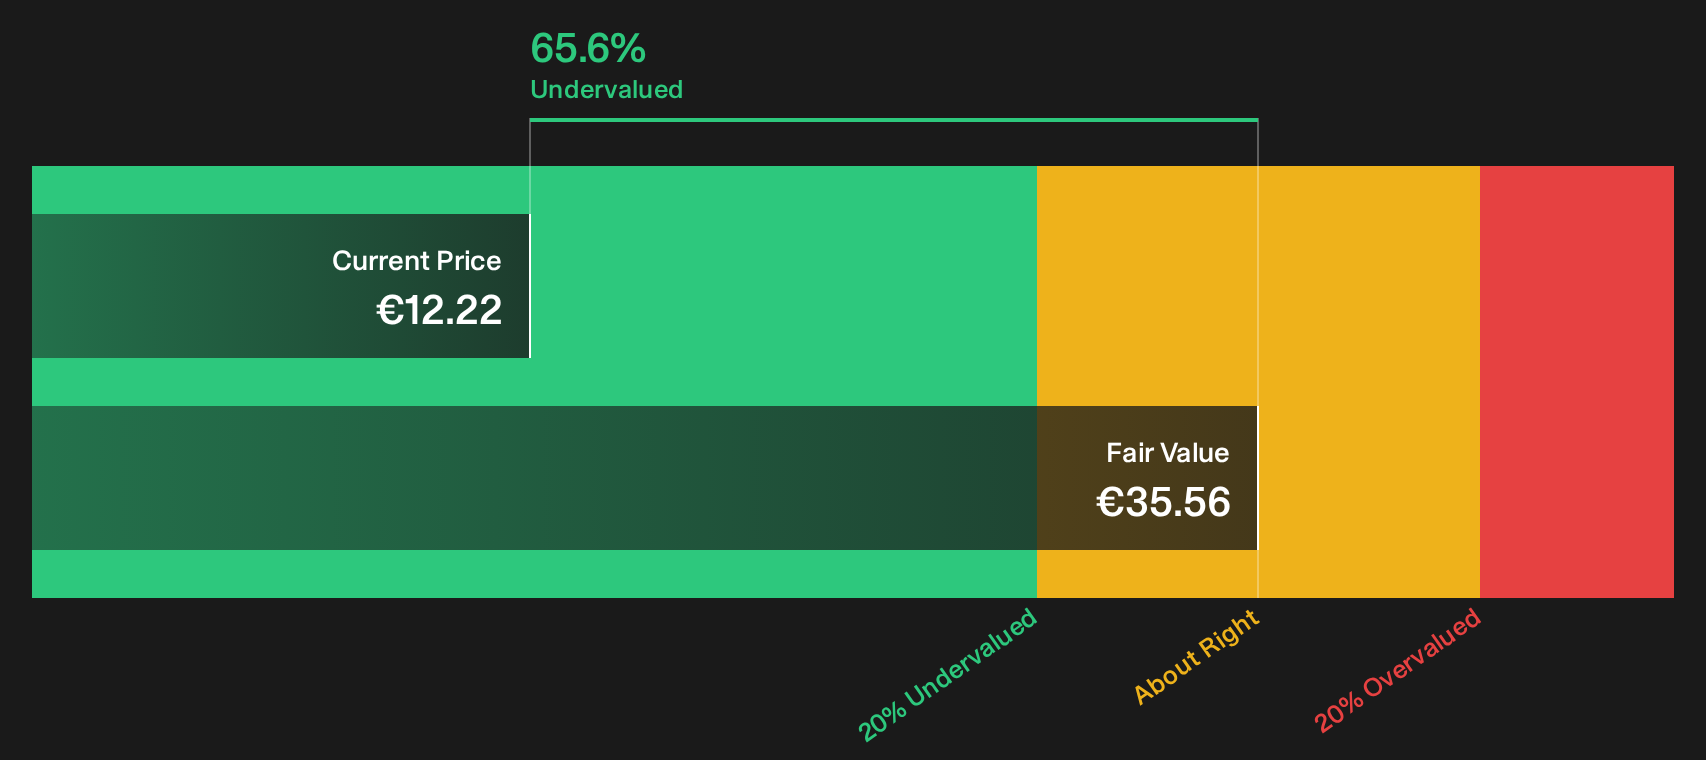
While the analyst narrative points to Südzucker as roughly fairly priced around €11.98, the SWS DCF model tells a very different story. That cash flow based approach puts future value at €35.56 versus a market price of €12.22, which implies a steep discount. Which version of “fair” do you trust more: a consensus target or a long term cash flow lens?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals or simply a reset in expectations for Südzucker? Act while the data is fresh by weighing both sides through 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Südzucker?
Round out your watchlist with a few fresh contenders that match your risk profile, income needs, and balance sheet standards while Südzucker’s story plays out.
- Target steadier potential returns by reviewing a 222 resilient stocks with low risk scores that may hold up better when sentiment turns.
- Boost your income focus by checking a 223 dividend fortresses that combines higher yields with disciplined payout histories.
- Hunt for tomorrow’s leaders early by scanning a 618 high quality undiscovered gems before they hit wider market radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com