


Revenue Outlook Raised Could Be A Game Changer For Insulet Stock (PODD)
- Insulet reported 23% year over year revenue growth to US$802 million, driven by Omnipod demand across US and international markets, and raised its 2026 revenue growth outlook to a range of 20% to 22% with stronger expectations for overseas sales.
- An important angle is Insulet’s effort to address weaker early retention among type 2 Omnipod users through expanded customer support, revamped sales incentives, and an upcoming closed loop system focused on this large segment.
- We will examine how Insulet’s investment narrative develops as strong Omnipod driven revenue growth intersects with more challenging type 2 retention dynamics.
Scan beyond Insulet and see how other diabetes and medical device players stack up in our hand picked list of 34 healthcare AI stocks.
Insulet Investment Narrative Recap
To own Insulet, investors would need to believe the Omnipod platform can keep adding users while early type 2 retention improves enough to support the recurring pod stream. The latest 23% revenue growth to US$802 million and higher 2026 growth outlook rely on that idea, particularly in overseas markets where guidance is stronger.
The key near term factor is whether type 2 users stay on Omnipod long enough for the model to be effective. Early churn in this group remains the biggest operational risk. Management’s revised 2026 guidance already reflects softer U.S. type 2 utilization, so the recent outlook change appears incremental rather than a major reset.
A relevant recent development is Insulet’s focus on type 2 diabetes, where more than 40% of U.S. new customer starts already come from this group and the automated insulin delivery market is described at about US$28 billion. The company is expanding customer support, refining sales incentives, and preparing a fully closed loop system for type 2.
These initiatives matter because an important potential catalyst is better early retention and pod utilization in type 2 without significant margin erosion. If the redesigned commercial approach and upcoming Omnipod 6 and closed loop offerings convert more of those new starts into multi year users, the larger addressable pool and recurring pod usage could become more tangible for shareholders.
What Analysts Are Building Into The Insulet Story
Insulet's narrative projects US$4.5b revenue and US$683.8 million earnings by 2029. That outlook rests on analysts assuming 14.1% yearly revenue growth and an earnings increase of about US$308.5 million from US$375.3 million today.
Uncover why Insulet's fair value indicates a 27% potential upside to its current price, which could narrow quickly.
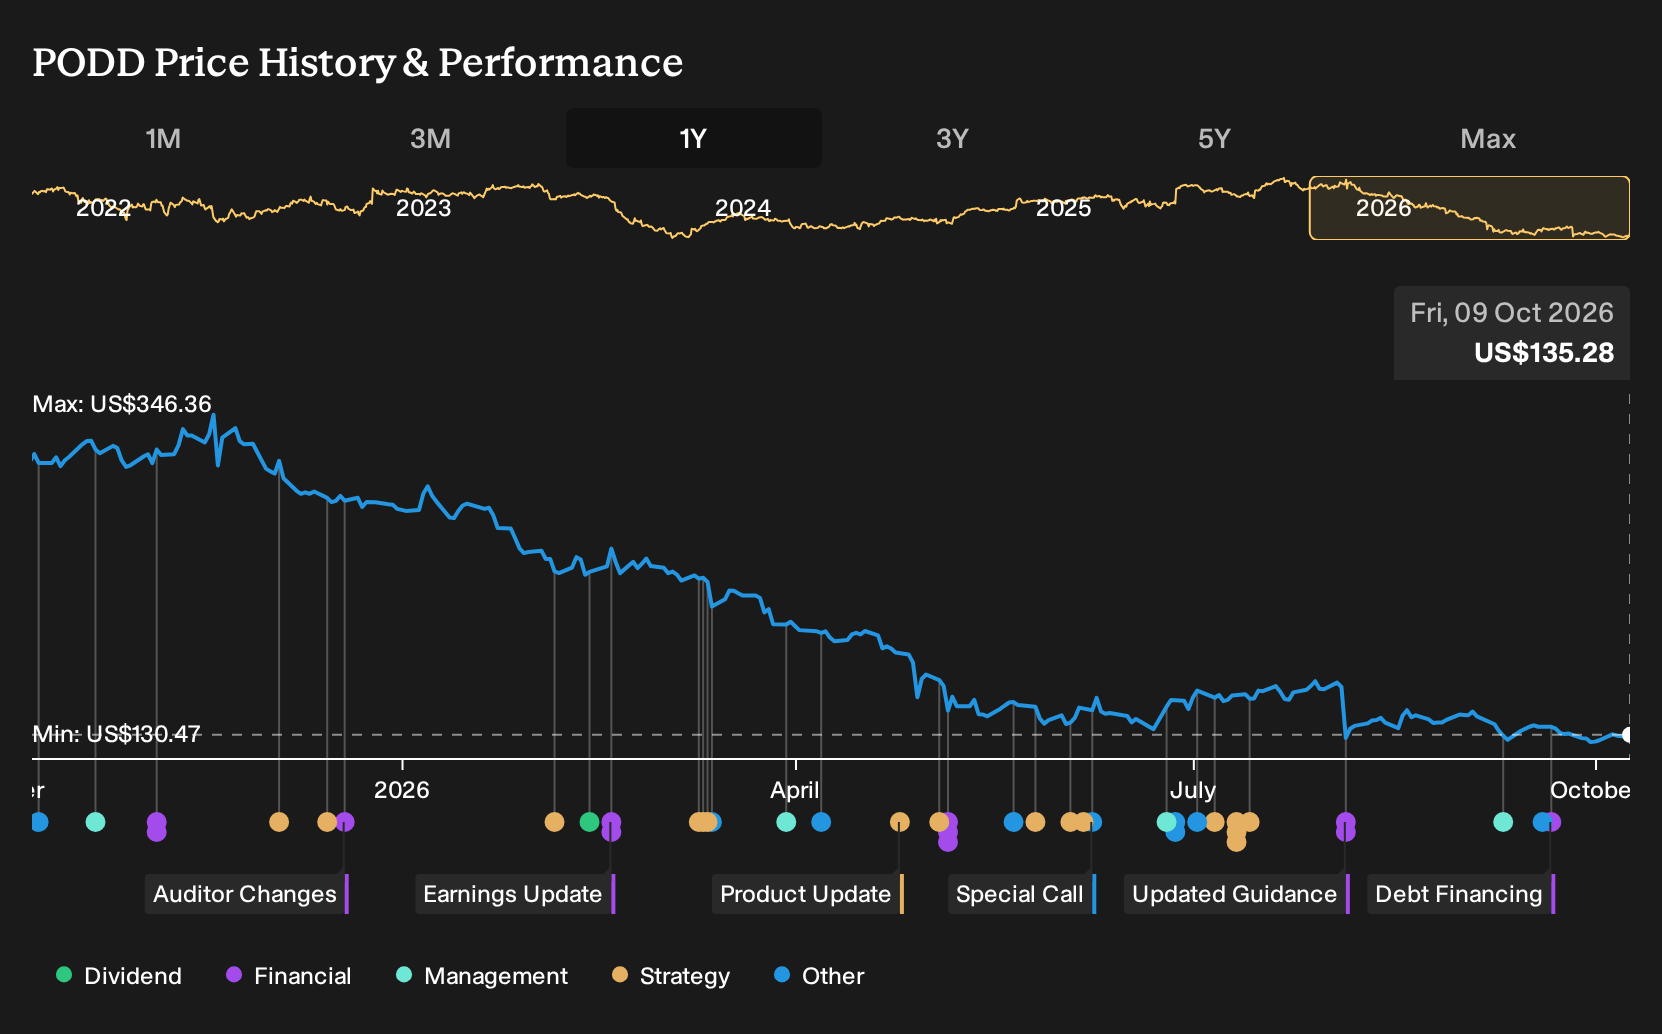
Exploring Other Perspectives
For a very different take on Insulet, some of the most optimistic analysts lean heavily on the large underpenetrated U.S. type 2 diabetes market as the real swing factor. Before this latest update, they were modeling revenue of about US$4.9b and earnings near US$748.2 million by 2029. That is well above consensus and shows how far views can stretch. The fresh Omnipod numbers and retention efforts may push those narratives in either direction, so treat this as a moment to compare assumptions and decide which story you find more realistic.
Explore 4 other Insulet fair value estimates, including one that suggests as much as 78% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Insulet research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Insulet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Insulet's overall financial health at a glance.
Looking For More Ideas Beyond Insulet?
If the Insulet story has sharpened your thinking and you want to stress test that framework on other opportunities, the Simply Wall St Screener can be a useful next step. Filter by the traits that matter most to you, then compare how different businesses stack up on quality, value, and resilience.
- If you want stronger pricing power and cleaner income statements, start with companies that pass a tight quality filter through a 20 high quality undiscovered gems.
- For investors who prefer steadier balance sheets over drama, focus on resilience and capital strength using a list of solid balance sheet and fundamentals (25 results).
- If capital preservation comes first and excitement second, narrow your search to companies with lower risk profiles via a 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com