


Is Travelers Companies (TRV) Fully Valued Following Its Strong Share Price Run?
Travelers Companies (TRV) has been drawing attention after recent share performance, with the stock closing at US$368.75 on 9 October 2026. Investors are weighing that price against reported revenue of US$48.98b and net income of US$8.24b.
Recent trading has been choppy rather than one way, with Travelers Companies slipping 0.4% on the day but still holding a 2.3% 7 day share price return and a 29.3% gain year to date. The 1 year total shareholder return of 38.6% and 5 year total shareholder return of 160.5% point to momentum that has been building over time.
Scan beyond Travelers Companies and see how it stacks up against 31 resilient stocks with low risk scores, which is built to highlight resilient business models and steadier return profiles.
After a near 30% year to date climb and a share price that now sits above some analyst targets, Travelers Companies forces a practical call. Is it better to commit at this level or wait for a softer entry before the valuation work?
Most Popular Narrative: 2% Overvalued
Travelers Companies is trading at $368.75 against a widely followed fair value estimate of $360.54, which puts the current quote slightly ahead of that narrative and raises the question of how durable recent returns really are.
The pattern of disciplined underwriting and conservative reserving, backed by 19 years with net favorable prior-year reserve development totaling US$15b pre tax and fresh favorable development across all segments in 2026, may keep supporting core ROE and net margins even if written pricing growth slows.
See why 29 investors see Travelers Companies as 2% overvalued.
Result: Fair Value of $360.54 (OVERVALUED)
Still, Travelers Companies carries real pressure points, particularly the risk of more severe catastrophe losses or worsening long tail casualty trends that could quickly challenge the current margin story.
Find out about the key risks to this Travelers Companies narrative.
Another View: Travelers Companies Through A Different Lens
The analyst narrative suggests Travelers Companies is close to fair value at $360.54, with the current $368.75 price described as about 2% above that level. The SWS DCF model presents a very different picture, with a future cash flow value of $766.42, which would imply the stock is materially undervalued instead.
These two approaches ask you to weigh a modest premium to one fair value against a large discount to another. The gap lies in the assumptions about future earnings pressure and required return. Which version of Travelers Companies' future you consider more realistic will depend on your own expectations for margins and capital returns.
Look into how the SWS DCF model arrives at its fair value.
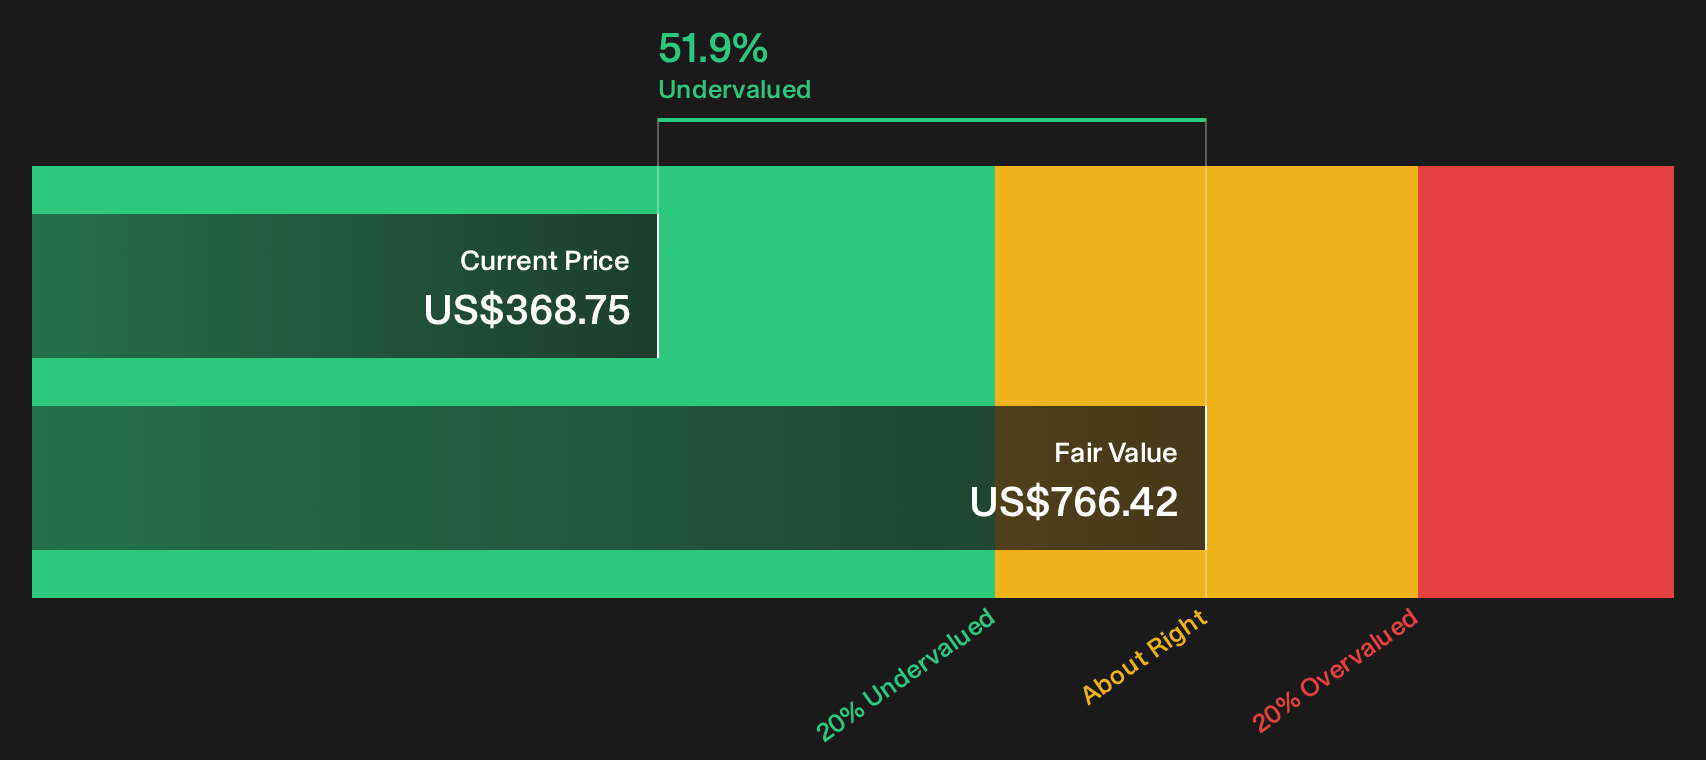
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Travelers Companies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Travelers Companies' value often create interesting opportunities. Move quickly, study the data for yourself, and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Travelers Companies?
If Travelers Companies has sharpened your focus on quality, do not stop here. Use the Simply Wall St screener to uncover opportunities you might otherwise miss.
- Target potential mispriced opportunities before the crowd by running a search built around 28 high quality undervalued stocks that already screen well on quality and fundamentals.
- Build a portfolio that aims for stability and toughness under stress by focusing on a list of solid balance sheet and fundamentals (25 results) tailored to your risk comfort.
- Get ahead of the market by searching for promising stories the broader market has not fully noticed using a focused set of 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com