


Is Chevron (CVX) Cheap On Hurricane Isaias And Higher Crude Prices?
Chevron (CVX) is back in focus after Hurricane Isaias forced the producer to halt some Gulf of Mexico output, just as a Gulf tanker attack and geopolitical risks pushed crude prices sharply higher.
For investors, the immediate spike in crude tied to Hurricane Isaias and Gulf security risks is landing on top of an already strong run in Chevron’s shares. The stock is up 35.97% year to date on a share price basis and has delivered a 47.97% total shareholder return over the past 12 months. The recent 20.17% 90 day share price gain points to building momentum, even as shorter term swings around storms and geopolitics reshape how the market is pricing both growth potential and risk.
Scan the energy patch beyond Chevron and focus on 28 high quality undervalued stocks, which could also be positioned to benefit when supply shocks push crude and fuel prices higher.
The question hanging over Chevron now is simple. Does a US$211.98 share price mostly reflect a stronger underlying business, or has sentiment sprinted ahead of what the current fundamentals support?
Most Popular Narrative: 4.8% Undervalued
Chevron’s most followed thesis pegs fair value at about $222.67 using a 7.24% discount rate, compared with the recent $211.98 close. That gap suggests the current price already reflects expectations for a solid business, while still leaving a modest cushion linked to execution on key projects.
Record production growth, especially in the Permian and from the Hess acquisition in areas such as Guyana and the Bakken, now sits on top of capital and drilling programs that aim to keep Permian volumes around 1 million barrels per day with lower CapEx per barrel, which supports future revenue and free cash flow.
See why 463 investors see Chevron as 5% undervalued.
Result: Fair Value of $222.67 (UNDERVALUED)
Still, the Chevron story frays quickly if long term energy demand shifts away from hydrocarbons faster than expected, or if analyst margin forecasts prove too optimistic.
Find out about the key risks to this Chevron narrative.
Another View: Chevron Through The Market’s Lens
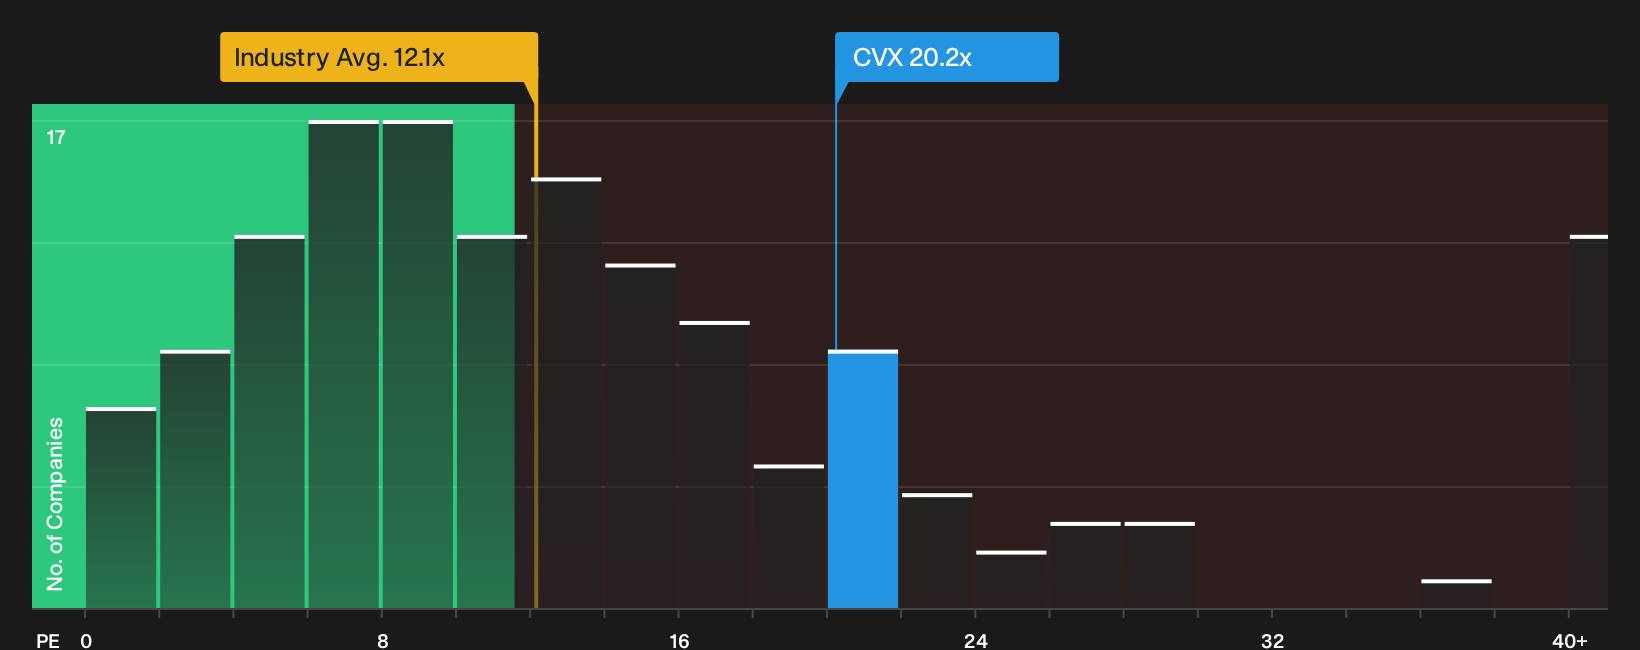
The first fair value story for Chevron leans on future cash flows, where the stock trades at a 39.8% discount to an estimated $352.14 future cash flow value and is described as undervalued. The market, though, is currently paying a P/E of 20.2x for Chevron, which is higher than the 17.8x peer average and well above the 12.1x wider US Oil and Gas group.
That premium sits just under the 21.3x fair ratio, suggesting investors already bake in a quality tilt but not a runaway bubble. For anyone weighing these signals side by side, the real question is simple: Are you more comfortable anchoring on cash flow forecasts, or on what comparable companies trade at today?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Chevron’s risk and reward profile will not resolve themselves. Review the data for yourself and quickly access the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Chevron?
If you only stop at Chevron, you miss a wider set of opportunities that match different return goals, risk levels, and income needs across the market.
- Target higher potential upside in smaller companies by scanning the 14 elite penny stocks with strong financials that pass Simply Wall Street’s filters for stronger financial profiles.
- Lock in income-focused opportunities by zeroing in on 8 dividend fortresses that already clear a 5% yield hurdle while aiming to keep payouts more robust.
- Dial back risk without stepping away from equities by filtering for 31 resilient stocks with low risk scores that combine sturdier balance sheets with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com