


Learn Why The Bull Case For Disney Stock Could Change Following Infinity Vision Rollout
- Walt Disney has already rolled out its Infinity Vision large format cinema standard and is pitching it to studios such as Paramount, Universal, Lionsgate and Sony as a premium big screen option that can sit alongside or substitute IMAX branding in hundreds of existing theaters.
- The push to badge third party blockbusters under Disney’s Infinity Vision banner ties exhibition quality directly to the company’s intellectual property and Experiences ecosystem, which could influence how value is shared between studios, format providers and theater owners over time.
- Now the focus shifts to how Walt Disney’s push behind the Infinity Vision premium format could influence the long term investment narrative.
Walt Disney Investment Narrative Recap
To own Walt Disney today, you need to believe its IP, Experiences, and streaming arms can work together to turn large audiences into higher quality earnings. The near term swing factor is execution on streaming profitability while keeping viewers engaged despite rising prices and growing dissatisfaction with subscription value across the sector. Infinity Vision adds another lever but does not change that core bet.
The biggest risk still sits in softer streaming ad markets and any renewed weakness at Asian parks, which could cap margin progress if pricing or volume cannot fully compensate. Infinity Vision looks more like an incremental opportunity than a material new threat or savior for the current earnings path.
The Infinity Vision rollout is the clearest recent announcement tied to this story. By pitching a Disney controlled premium format to Paramount, Universal, Lionsgate, and Sony, the group is trying to keep more of the economics and data around blockbuster viewing inside its own ecosystem. That plugs directly into the Experiences and content flywheel.
For investors, the key question is execution: can Walt Disney convince external studios and theater operators that an Infinity Vision badge drives ticket mix and marketing impact without the IMAX halo? If adoption remains modest, the main catalysts revert to Experiences performance, ESPN and live sports monetization, and tighter cost control in streaming while managing the legal and park demand risks already on the table.
Walt Disney's current analyst storyline points to revenues of US$113.7b and earnings of US$13.5b by 2029, based on an assumed 4.8% yearly increase in revenue and an earnings increase of about US$4.9b from US$8.6b today.
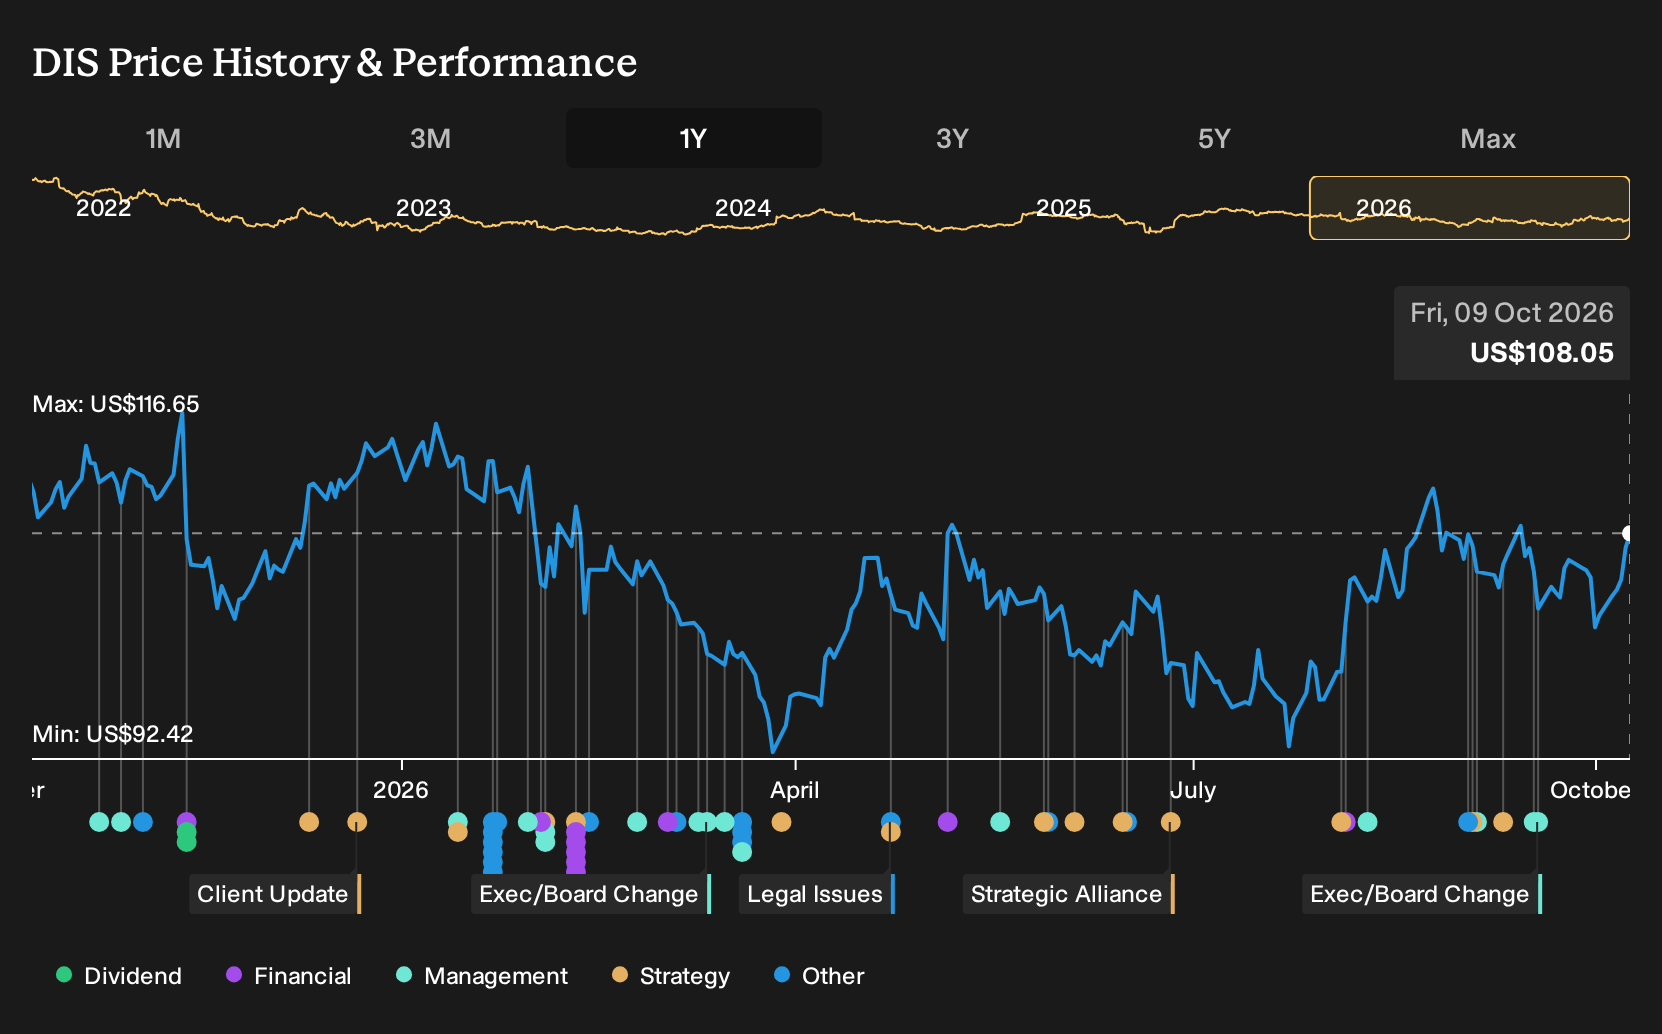
Uncover why Walt Disney's fair value indicates a 17% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Five fair value views from the Simply Wall St Community cluster between about US$123 and US$135, so retail investors there are largely grouped in a tight band on Walt Disney rather than split into extremes. Those opinions do not yet reflect Infinity Vision, ESPN momentum, or streaming ad risks; you are seeing yesterday's snapshot, not today's debate.
Explore 4 other Walt Disney fair value estimates, including one that suggests as much as 25% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Walt Disney research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Walt Disney. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Walt Disney's overall financial health at a glance.
Looking for more investment ideas beyond Walt Disney?
Once you have a handle on Walt Disney, it can help to widen the lens and compare it with other businesses that fit different risk and income profiles using the Simply Wall St Screener.
- For investors hunting for resilient balance sheets and steadier fundamentals, review our list of solid balance sheet and fundamentals (25 results) to focus on financial strength first.
- If capital preservation and smoother rides matter more than chasing every swing, scan the 31 resilient stocks with low risk scores to see which companies line up with a lower risk profile.
- For those willing to do extra homework in return for early stage potential, sort through the 14 elite penny stocks with strong financials which may offer high upside with equally high uncertainty.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com