


3 Regional Bank Stocks Built For Higher For Longer Rates
Fed officials are again talking about keeping rates higher for longer, and that puts the spotlight on companies that can live with more expensive money rather than rely on cheap credit. Investors watching this tension between inflation and policy risk missing chances if they tune it out. This article walks through three stocks exposed to this latest Fed commentary and explains how each might respond under tougher financial conditions.
The three companies in focus are only a starter pack, and the full screen on large U.S. banks and insurers surfaced 26 more businesses with equally compelling stories that are not covered below. To go straight to the source and identify, compare, and analyze potential higher conviction ideas, head into the US Financials – Large Banks and Insurance Benefiting from Higher-for-Longer Rates screener.
Bank7 (BSVN)
Overview: Bank7 is a regional U.S. bank holding company that earns mainly from lending and deposits, tying its fortunes closely to Federal Reserve interest-rate levels.
Operations: Bank7 generates about US$98 million in banking revenue, all from customers in the United States, giving it a focused, rate-sensitive domestic franchise.
Market Cap: US$529 million
Bank7 appears closely aligned with the higher-for-longer interest-rate theme, with U.S. banking revenue, net interest income and a growing dividend all moving in line with Federal Reserve policy. Forecast earnings and revenue growth above the wider market underline that link. A key uncertainty is how its net interest margin might respond if a single unseen pressure alters the balance between deposit costs and loan yields.
If you want to see whether that margin risk is already priced in or masking upside, review the DCF valuation analysis for Bank7 for the full context.
Arrow Financial (AROW)
Overview: Arrow Financial is a regional U.S. bank that collects deposits and lends to households and businesses, earning interest on that spread.
Operations: Arrow Financial generates about US$170 million from community banking in the United States, tying most revenue directly to domestic interest-rate levels.
Market Cap: US$686 million
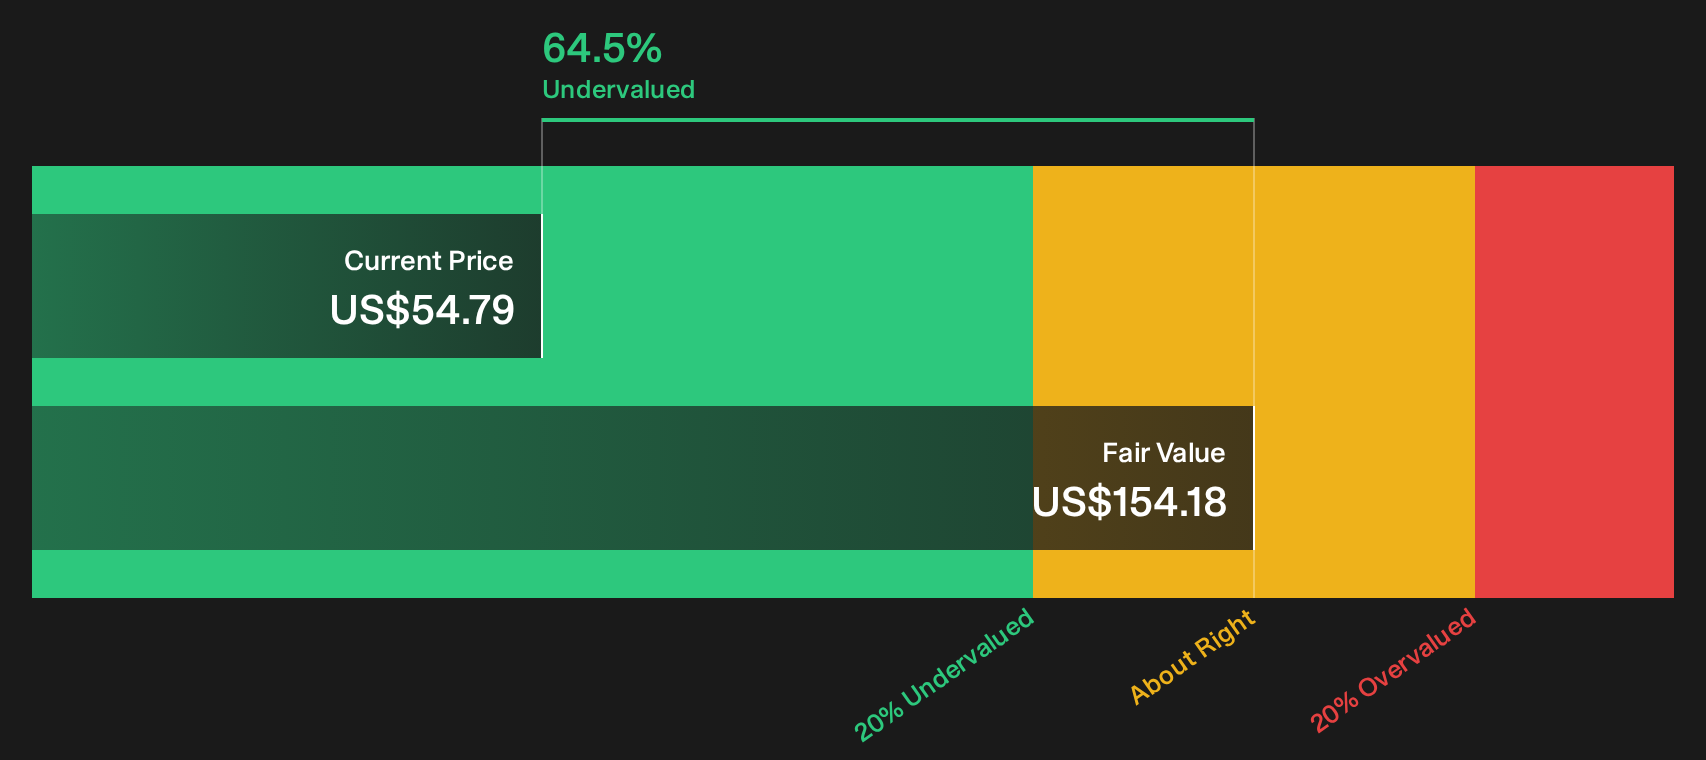
Arrow Financial is closely linked to the higher-for-longer theme in interest rates, with community banking income and a 3.3% dividend yield all connected to how net interest income behaves as Fed policy stays tight. The key unknown is how a shift in funding costs could reshape the current gap between earnings expectations and today’s valuation.
That potential gap is exactly where investors are asking questions, so use the DCF valuation analysis for Arrow Financial to see how Arrow Financial’s pricing lines up with those expectations.
Bank First (BFC)
Overview: Bank First is a Wisconsin based bank holding company that earns mainly from interest on loans funded by customer deposits.
Operations: Bank First generates about US$217 million from banking operations in the United States, with all revenue tied to domestic clients.
Market Cap: US$1.6b
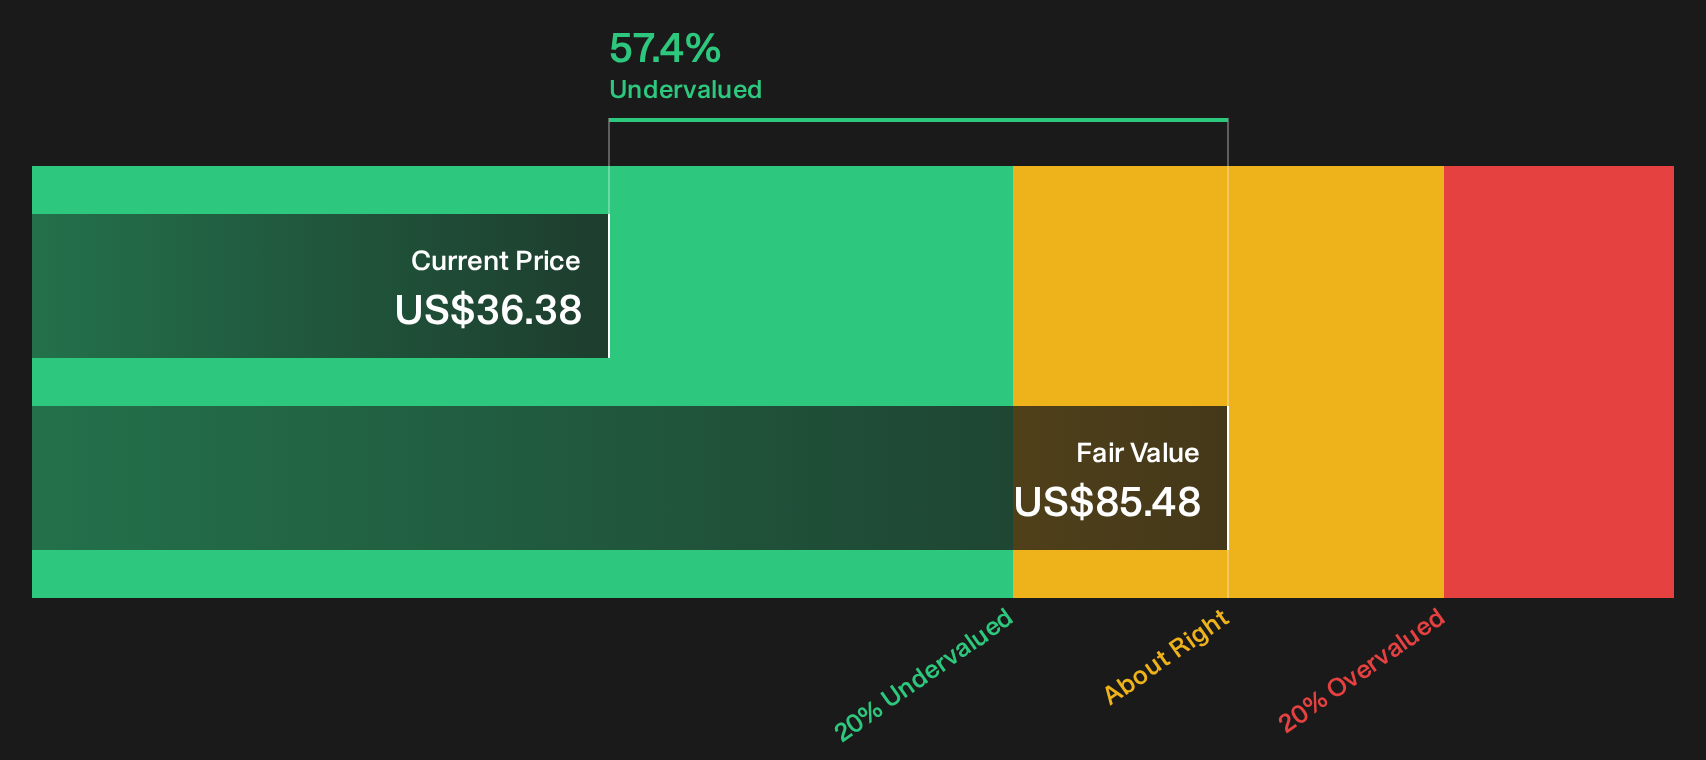
Bank First sits squarely in the higher for longer rates theme. Net interest income, a 37.1% profit margin and regular dividends all depend on its ability to earn more on loans than it pays on deposits. Investors drawn to that setup still need to weigh what happens if a single shift in funding costs changes how that gap looks.
That funding shift is exactly where things could get interesting for Bank First. To learn how that spread risk really stacks up, see the 3 key rewards and 1 important warning sign.

Curious About What You Might Be Missing?
Fresh opportunities can move from under the radar for now to full breakout momentum before most investors even notice. Scan these curated ideas while it matters and consider them early in your research process.
- Explore resilient payers and let income play a central role in your approach by reviewing a curated mix of high-yield candidates inside the 8 dividend fortresses.
- Look for potential early leaders in a fast-evolving field by reviewing the hand picked opportunities surfaced in the 92 AI infrastructure stocks.
- Monitor potential hedges when currencies wobble and sentiment swings by scanning producers highlighted in the focused 36 elite gold producer stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com