


What ZoomInfo Technologies Investors Missed Before A 61% Fall
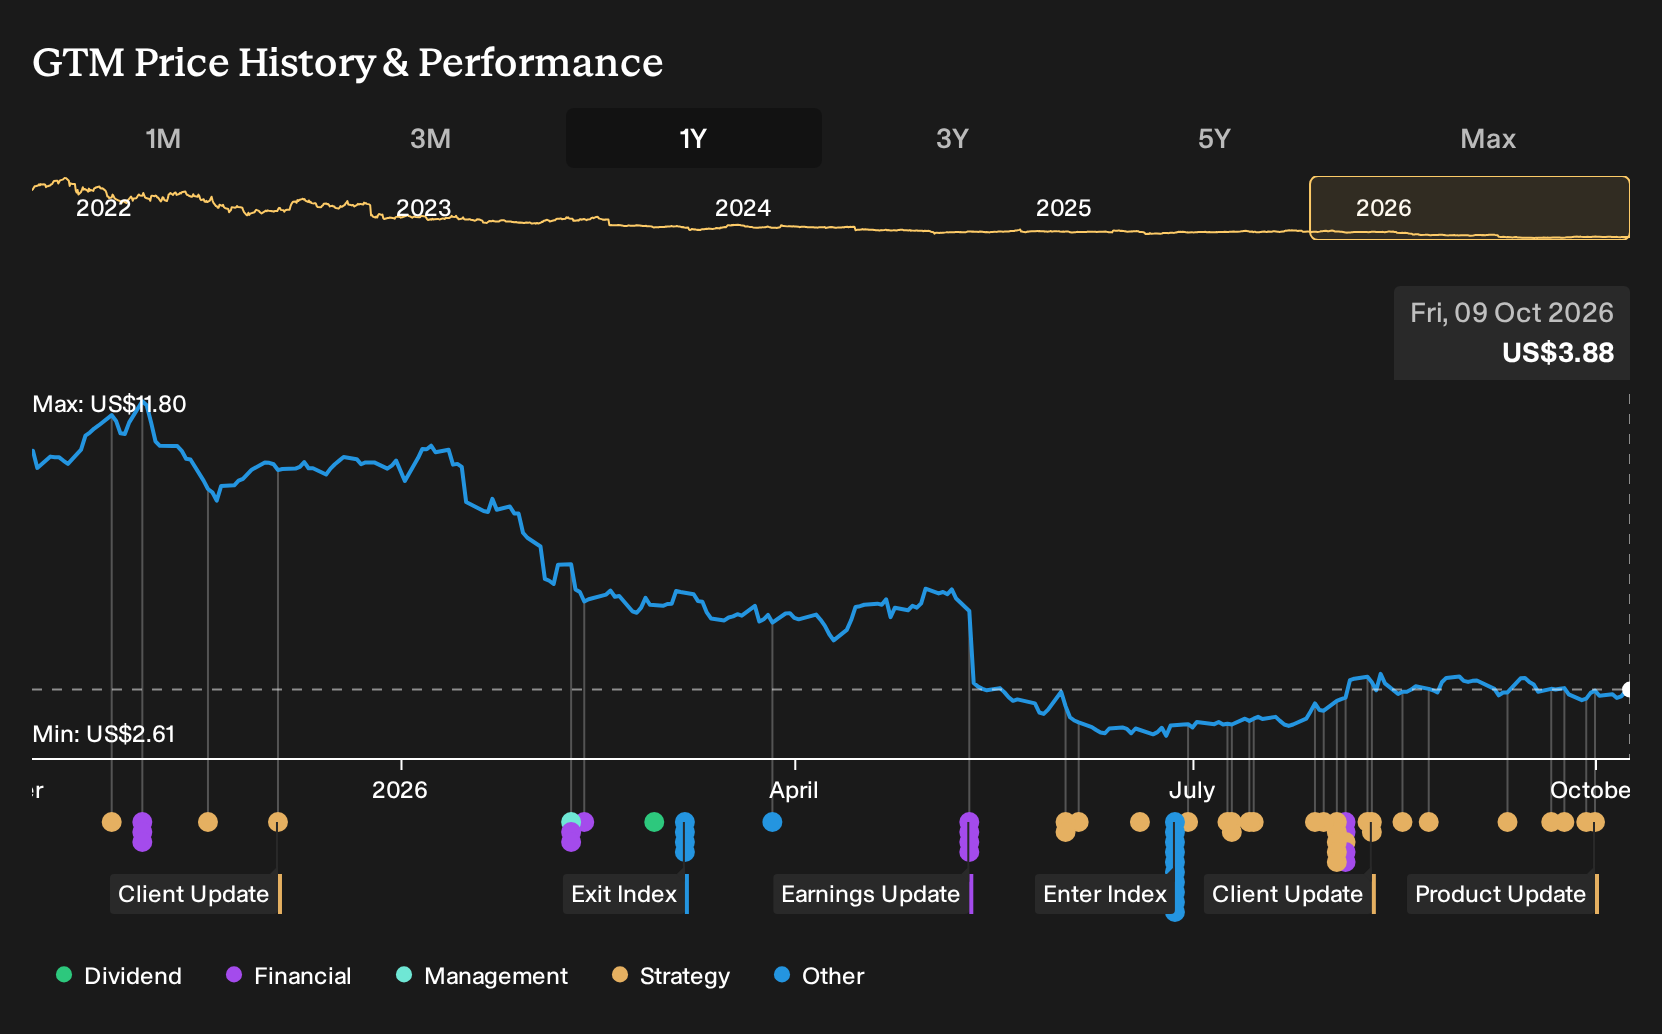
If you only glanced at ZoomInfo Technologies’ headlines, the story might have sounded constructive. Revenue was a little higher, AI products kept getting press, and the platform collected awards. Investors who held ZoomInfo Technologies over the past year are down 61.1%, including dividends. If you were weighing a position back in October 2025, what in the early signs of slowing software demand, SME weakness, and pricing shifts hinted that this kind of drawdown was possible?
The move put ZoomInfo Technologies in the middle of this trade. Scan 36 AI small caps for other companies exposed to it.
The Argument You Would Have Been Weighing Up On ZoomInfo Technologies
The shares cost US$10.44 at the start of the period, and investors in ZoomInfo Technologies had two clean stories on the table.
On the upbeat side, one camp saw a Fair Value of US$11.65, a price implied by a thesis built on 2.8% annual revenue growth and profit margins rising to 15.1% through AI led products and an upmarket tilt.
The cautious view pointed to a Fair Value of US$6.79, tied to SME softness, heavy spending, and concern that reliance on Copilot could pressure margins even if revenue kept moving.
What The Results Changed For ZoomInfo Technologies
ZoomInfo Technologies cut its 2026 revenue outlook and announced a roughly 20% workforce reduction, which supported the cautious case that shifting to a hybrid consumption model and relying on Copilot could strain execution. Reported figures reinforced that concern. Revenue in Q2 2026 was US$310.4 million compared with US$306.7 million a year earlier, while net income moved to a loss of US$643.7 million and net margin fell to 207.4% below zero, so the profitability part of the upbeat thesis remained unproven. Overall, the evidence supported the cautious view.
The lesson to apply to the next stock is straightforward. When a bullish story focuses on margin expansion, track net income and net margin immediately after management changes pricing or cost structure. If those figures move sharply against the story, treat any projected P/E or Fair Value as a hypothesis that still requires evidence.
What You Would Be Paying For In ZoomInfo Technologies Today
ZoomInfo Technologies now trades at US$3.88, and the selected Narrative’s Fair Value sits above that level based on its own assumptions. That view leans on a shift toward data led, non seat usage and AI agent integrations as the core of the longer term enterprise pitch.
For today’s drop to look like an opening rather than a warning, a buyer would need to believe that upmarket workflows, cost cuts, and capital returns can outweigh shrinking downmarket seats and softer net revenue retention.
"ZoomInfo Technologies is repositioning itself as a headless go to market context layer through GTM.AI, API access, and integrations into tools such as Replit, Slack AI, and Superhuman Go. This could widen its addressable usage beyond human sellers and support new data consumption revenue streams over time, with potential implications for revenue and gross margins."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Before The Next Story Makes Headlines
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 31% below our estimate - uses constrained offshore vessel fleets to negotiate longer, higher-priced contracts.
- Company 2 - 42% below our estimate - rides demand for large LED displays while emphasizing software-based recurring revenue.
- Company 3 - 46% below our estimate - integrates a recent banking acquisition to deepen client relationships and protect asset quality.
Three companies from the same screener. Open the full list of 28 companies trading below our estimate →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com