


How is the “RISC-V first share” Easway calculation (01256) valued?
RISC-V's first stock, Easway Computing (01256), has officially entered the Hong Kong stock market, and the company's high growth and scarcity are gradually becoming the main focus of market attention.
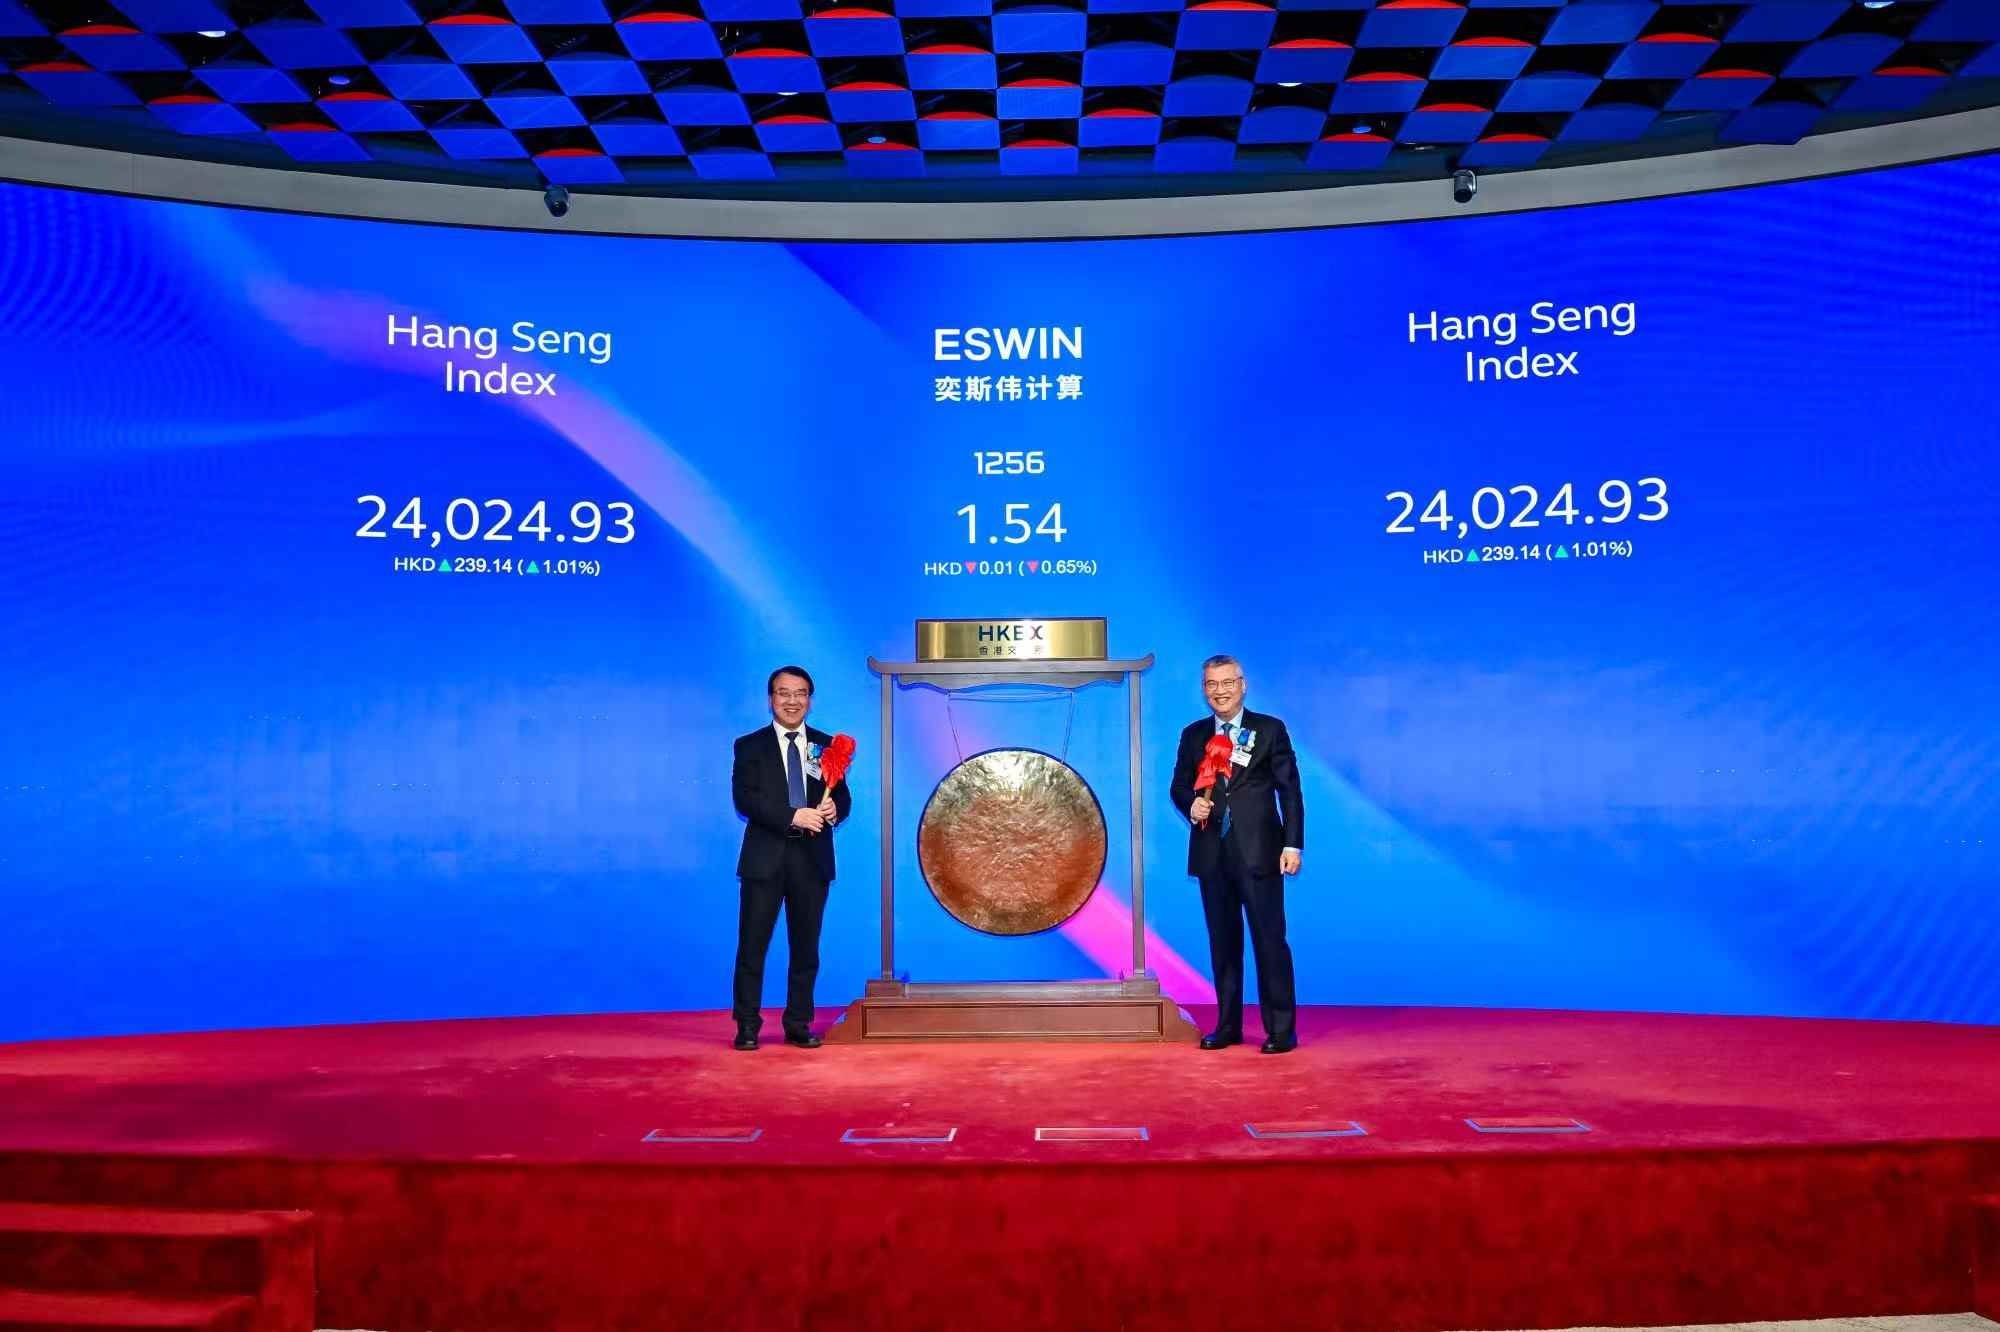
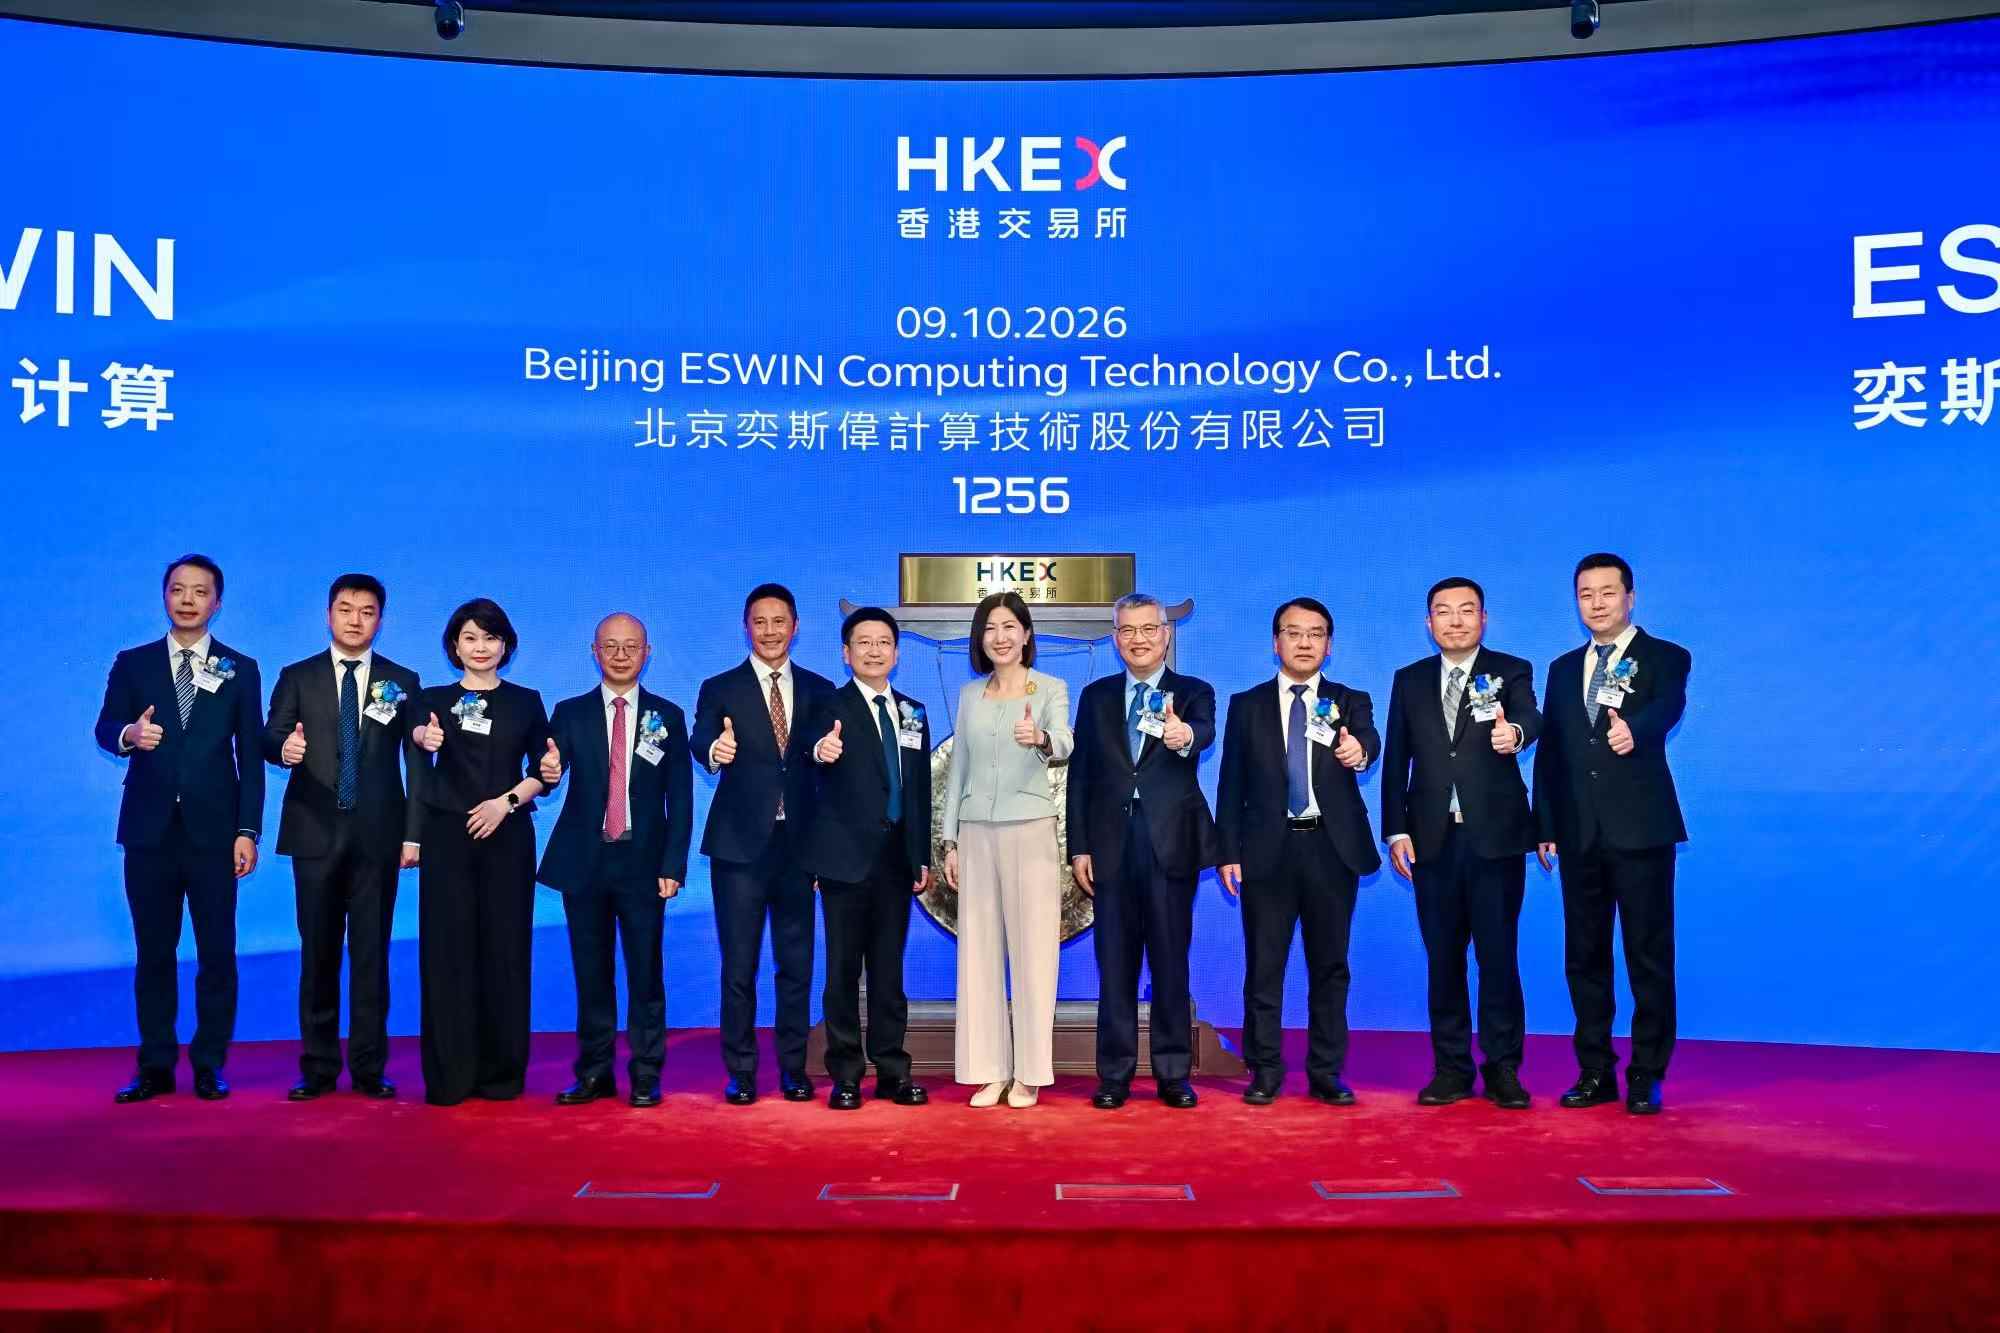
The Zhitong Finance App learned that Easway completed the stock offering on October 6, with an offering price of HK$1.55, a net raise of HK$2,386 billion from the global sale. The Hong Kong public sale received 9.09 times the subscription, and the international sale received 1.95 times the subscription. On October 9, the company successfully went public.
The listing of Easway Computing has filled the gap of pure RISC-V chip standards in the capital market, which is one of the core reasons why the company has received widespread attention in the market.
According to the purpose of fund-raising, about 35% of the capital will be used to develop and iterate chip products; 30% will be used to enhance the hardware and software capabilities of the RISAA platform and improve the open, flexible and interoperable R&D system; 15% will be used for potential strategic mergers and acquisitions to expand technical capabilities and product portfolios and enhance the company's global competitiveness; and 10% will be used to build and expand the marketing network to further promote the RISC-V ecosystem. With this listing on the Hong Kong Stock Exchange, the growth story of Easway Computing will also enter a new stage of development.
It has received long-term financial attention and has great potential for long-term valuation
From the subscription situation at the tender stage to the dark market and the steady performance on the first day of listing, the market's attention to Easway's calculation is gradually shifting from short-term prices to long-term value. There are two main reasons: first, investors are highly optimistic. The “RISC-V first share” superimposes the double scarcity attributes of AI, making the company a core target of capital layout that cannot be circumvented; second, the company's valuation is still at a low level, attracting long-term investment institutions and large investors to enter the market to obtain long-term benefits.
In terms of market pricing, the PS valuation price for AI+ circuits with high prospects and high quality standards is generally 20 times or more. For example, the smart spectrum of enterprise general AI model circuits and Insilicon intelligence in the field of AI pharmaceuticals, the PS value is still as high as several hundred times; in the field of AI+ chips, PS is over 80 times higher.
Let's also look at the valuation calculated by Easway. Based on the closing price of HK$1,535 on the first day, the total market value of the company is about HK$33.8 billion, which is about 11.8 times PS based on 2025 revenue. Compared to other targets, the market price is low. However, it should be noted that market pricing amplifies beta values in the short term, and the core logic of long-term improvement is that the company's strength and development potential continue to attract long-term investors, thereby driving the continuous implementation of valuations and performance.
According to Frost & Sullivan, according to 2025 revenue, the company is China's largest domestic smart terminal human-computer interaction chip provider. In the “RISC-V+AI” direction, Easway Computing has become the company with the most comprehensive patent, IP and product coverage in the world.
The company will focus on raising capital to invest in the integrated development of “RISC-V+AI” to enhance software and hardware technology capabilities. It will also carry out strategic mergers and acquisitions to stabilize its competitiveness and leading position in the industry. According to Frost & Sullivan data, China's RISC-V main control chip market size is 37.7 billion yuan in 2025, and the compound growth rate will reach 139.5% in 2021-2025. It is expected to reach 219.4 billion yuan by 2030, and the compound growth rate will still be as high as 36.2% from 2026 to 2030.
Driven by R&D to create a clear growth curve
Looking at overall performance, Easway's computing performance grew strongly. In 2023-2025, revenue increased from 1,752 billion yuan to 2,431 billion yuan, a compound growth rate of 17.8%. In 2026, Q1 revenue was 494 million yuan, an increase of 18.4% over the previous year.
The company is an R&D-driven high-tech enterprise, and R&D requires a large upfront investment, which is the core reason why Easway Computing is still losing money. In 2026, Q1's R&D expenses rate was 51%. Compared with the same period, it is mainly due to the release of R&D results and entering the harvest cycle, and the company's profit space is expected to open up further.
Easway Computing has built a RISAA (RISC-V+AI) ecosystem technology platform, deeply integrated the RISC-V computing architecture with AI technology, and built multiple self-development capabilities covering CPU cores, NPUs, bus interconnection, security, software tool chains, and AI compilers. In terms of ecological adaptation, the company's intelligent computing products have completed certifications for enterprise-level operating systems such as Ubuntu and RedHat, and have reached cooperation with Canonical and RedHat to solve the “core and soulless” pain point of RISC-V in high-end applications. As of March 31, 2026, the company has launched more than 150 software and hardware collaboration products to serve 220 customers around the world, including many of the world's top technology companies.
Multiple factors such as the rise of AIAgent, automobile intelligence, and the acceleration of industrialization of embodied robots have jointly driven the development of RISC-V, making it an important technology route in the global chip field, and the RISC-V ecosystem has entered a stage of definitive rapid growth. According to public research, shipments of RISC-V related chips have exceeded 10 billion units, and will continue to grow rapidly in the next few years.
Taken together, Easway Computing's current listing has filled the gap in the genuine RISC-V standard in the capital market. Relying on solid fundamentals and a diversified product matrix created by R&D accumulation, the company's profitability has a foundation for continuous improvement. The interconnection and computing chip product business is accelerating, and demand for multiple scenarios continues to explode, which also supports high performance growth. In the long run, as business logic is implemented and performance continues to be released, the company's valuation is expected to reach a new level.