


Higher for Longer Rates Put These US Regional Bank Stocks In Focus
Higher mortgage rates, stubborn inflation expectations and weaker consumer confidence are reshaping where money can work hardest, or do the most damage, in your portfolio. When borrowing costs stay elevated for longer, some businesses gain extra income from interest while others feel more pressure from cautious households. This article walks through three stocks that screening tools suggest could be exposed to this higher for longer rate story, so you can judge whether they deserve a closer look or a wider berth.
The stocks covered below are just a sample pulled from this theme, and the full screen surfaced 10 more banks and insurers with equally compelling higher for longer narratives that are not broken down in the article. If you want to identify, compare and analyze the candidates that best match your own risk and income goals, go straight to the US Banks and Insurance Companies Positioned to Benefit from Higher-for-Longer Interest Rates screener.
Farmers National Banc (FMNB)
Overview: Farmers National Banc is a traditional Ohio-based bank holding company that provides lending, deposit, trust and financial management services to households and businesses.
Operations: Farmers National Banc generates about $161.9 million from its bank segment, $15.9 million from trust and retirement services, plus $40.7 million of other revenue, all in the United States.
Market Cap: US$901 million
For a higher for longer rate theme, Farmers National Banc offers a straightforward loan and deposit model, strong net profit margins near 30% and a 4.54% dividend yield that fits the screener’s income focus. However, recent dilution and higher charge offs leave one unresolved pressure that could shift how much of those richer margins reach shareholders.
Those charge offs and fresh shares raise questions that only a closer lens can answer, starting with the Farmers National Banc financial health report before those margin pressures bite harder.

Dime Commercial Bancshares (DCOM)
Overview: Dime Commercial Bancshares is a New York based bank holding company focused on commercial banking, lending and deposit services across the United States.
Operations: Dime Commercial Bancshares generates about US$439 million in revenue from community banking activities, all within the United States.
Market Cap: US$1.7b
Higher for longer rates matter directly for Dime Commercial Bancshares because its core business is turning low cost deposits into interest earning loans. As a result, the screener flags a bank whose earnings profile closely tracks where funding costs and loan yields settle next.
"The scheduled repricing or maturity of about US$2.5b of fixed and adjustable-rate loans at an average rate of 4.25% over the next 18 months provides a clear path for higher earning asset yields, which is expected to feed into net interest margin and earnings over the next several years."
What happens when that repricing power meets one unresolved pressure on profitability will likely matter more than any headline rate move.
That crossroads between repricing power and pressure is exactly where the story gets interesting, and the full narrative for Dime Commercial Bancshares maps how that tension could translate into either accelerating earnings or stalled returns.

HBT Financial (HBT)
Overview: HBT Financial is a regional bank holding company offering traditional lending, deposit, and wealth services to consumers, businesses, and municipalities in Illinois and Eastern Iowa.
Operations: HBT Financial generates about US$265.9 million in community banking revenue, all from customers across the United States.
Market Cap: US$1.3b
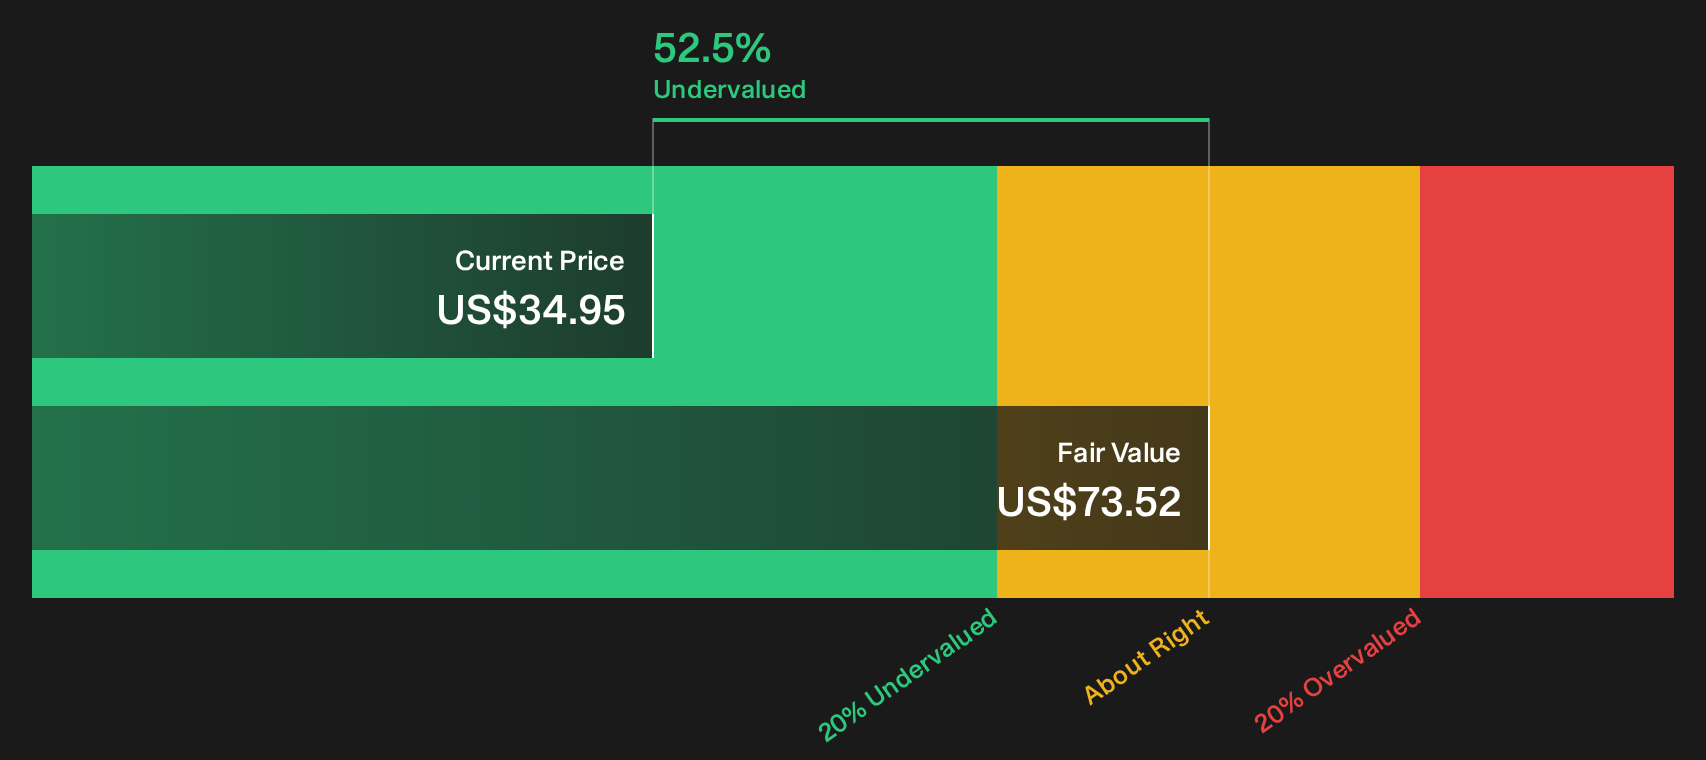
HBT Financial is aligned with the higher for longer theme, with a traditional loan and deposit engine, US$265.9 million in community banking revenue and earnings forecasts that are ahead of the broader market. The stock trades at a premium P/E and appears below estimated fair value, so a lot rests on how one unseen pressure shapes future net interest margins.
If that unseen pressure has you weighing how much faith to put in HBT Financial, start with the 3 key rewards and 1 important warning sign to see what may be hiding in plain sight.
Seeking Fresh Alternatives Before They Fly
Market narratives move fast and the best setups rarely wait. Spot fresh ideas with real momentum while they are still under the radar for now.
- Explore income-focused candidates built to keep paying with a curated batch of 8 dividend fortresses before yields adjust as prices move.
- Look for under-the-radar quality where balance sheets appear sturdy and cash flows are a key focus using a targeted list of solid balance sheet and fundamentals (25 results) while it still remains less widely followed.
- Review potential infrastructure-related opportunities by scanning a hand picked pool of 43 power grid technology and infrastructure stocks before grid upgrades attract broader attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com