


Is Earnings Preview Altering The Investment Case For Goldman Sachs Stock (GS)?
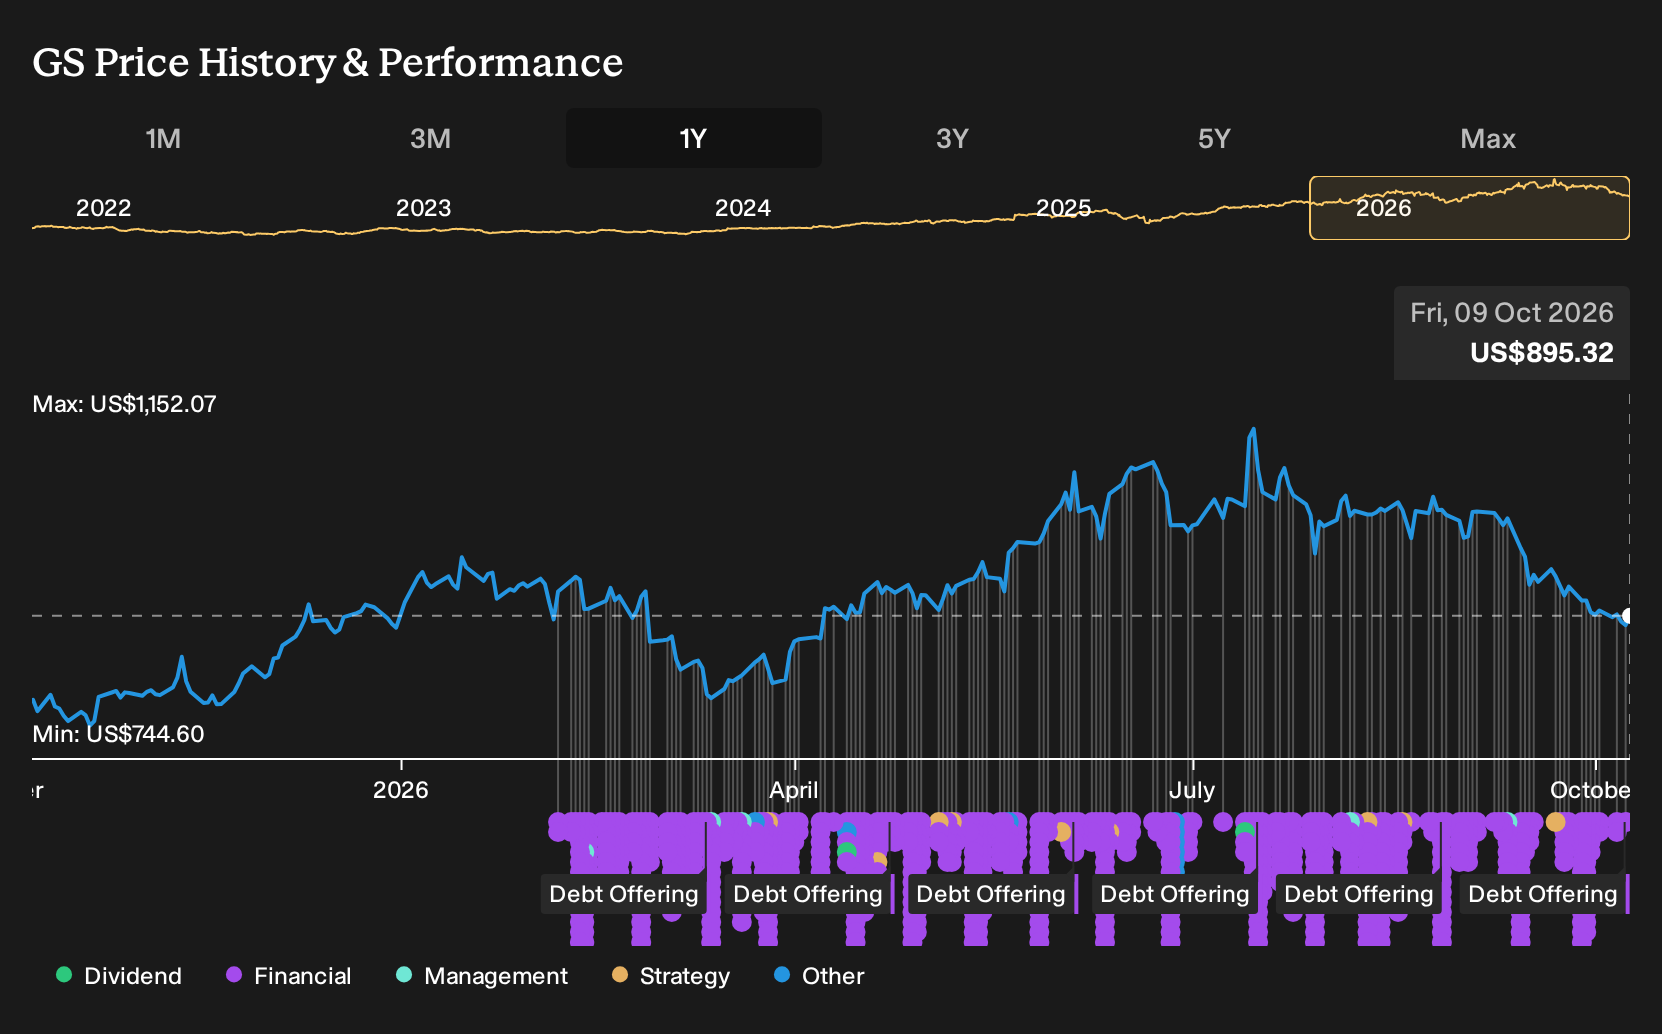
- Goldman Sachs Group has recently issued a series of fixed income securities, including multiple callable senior and unsecured fixed coupon notes across different currencies, maturities, and sizes, as well as a zero coupon Euro MTN in Mexican pesos.
- Alongside this funding activity, investors are weighing an upcoming earnings report in a softer fixed income trading and dealmaking backdrop, while large executive equity awards tie management incentives closely to long term share performance and capital returns.
- We will look at how Goldman Sachs Group's investment narrative interacts with heavy recent bond issuance and earnings expectations.
Scan how Goldman Sachs Group’s bond funding spree compares with other large financials, and see which issuers are gathering quiet momentum across our hand picked list of solid balance sheet and fundamentals (25 results).
Goldman Sachs Group Investment Narrative Recap
To own Goldman Sachs Group, you need to be comfortable with a bank-like investment firm that leans heavily on Global Banking & Markets and a growing Asset & Wealth Management arm, while pushing hard on technology and AI to keep costs in check. The near term swing factor is the upcoming earnings report, where investors want to see that higher non compensation expenses and softer fixed income trading are not eroding return on equity.
The main operational risk right now sits in that mix of higher costs and weaker FICC activity, set against a balance sheet that relies entirely on higher risk funding sources rather than customer deposits. The recent run of new fixed rate notes, much of it callable and medium term, looks more like regular funding than a game changer for the equity story. The more important test is still quarterly profitability and capital flexibility.
The most relevant recent development for this funding spree is the series of US dollar and peso fixed income offerings, including the 6.40% Notes due April 19, 2035 and the zero coupon Euro MTN in Mexican pesos. This cluster of callable medium term notes extends across maturities from 2027 out to 2051, with several senior and unsecured tranches at par pricing.
For an equity holder, these issues matter because they shape Goldman Sachs Group’s interest expense, capital structure and room to keep growing fee based businesses and financing lines while operating with a 4.3% supplementary leverage ratio. Execution risk arises if higher funding costs and heavier balance sheet usage compress returns just as non compensation expenses step up. That would test the thesis that technology and a richer advisory and asset management mix can support firm wide margins.
Goldman Sachs Group's current analyst script points to revenues of US$72.4b and earnings of US$21.1b by 2029, based on an assumed 2.3% yearly revenue growth rate and an earnings increase of about US$1.1b from US$20.0b today.
Uncover why Goldman Sachs Group's fair value indicates a 25% potential upside to its current price that could close sooner than you expect.
Exploring Other Perspectives
Some of the lowest Goldman Sachs analysts see the real story in digital disruption rather than funding costs. They were penciling in roughly flat revenue around US$67.9b and earnings of about US$18.9b by 2029 before this bond wave, a much more cautious script. Use that gap to stress test your own view as expectations adjust.
Explore 5 other Goldman Sachs Group fair value estimates, including one that suggests it could be worth just $1073.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so trust your own analysis.
- A great starting point for your Goldman Sachs Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Goldman Sachs Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Goldman Sachs Group's overall financial health at a glance.
Looking for more investment ideas beyond Goldman Sachs Group?
If the Goldman Sachs Group story has sharpened your thinking, use that momentum to size up a broader watchlist with companies that line up with your risk, income, and value preferences.
- For investors who want potential upside with strict quality filters, scan through a 20 high quality undiscovered gems that combine solid fundamentals with relatively low market attention.
- If capital preservation matters just as much as returns, narrow your focus to a 31 resilient stocks with low risk scores that screens for resilient balance sheets and lower overall risk scores.
- For those hunting for income ideas, sort through a 8 dividend fortresses that concentrate on higher yielding stocks which also aim for stability in their payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com