


Abbott Laboratories (ABT), Why Is Fresh Attention Building Around It?
Abbott Laboratories (ABT) has been back in focus after rolling out three new FDA-backed products in quick succession, spanning nutrition, digital heart failure management and blood-based colorectal cancer screening.
Despite these launches, Abbott Laboratories’ share price has had a mixed run, with a 6.04% 90-day share price return and a weaker year-to-date share price return of a 19.8% decline. The 3-year total shareholder return of 16.03% points to sturdier longer-run momentum than the past year’s 23.13% total return decline suggests.
Scan how Abbott Laboratories’ latest launches stack up against other health-focused players by reviewing the hand-picked list in 34 healthcare AI stocks that benefit from similar shifts toward tech-enabled care.
Abbott Laboratories is trading below the average analyst target after a sharp year-to-date slide, yet recent product launches have reshaped the story. Is the discount signaling opportunity, or is it flagging risks that the market is still pricing in?
Most Popular Narrative: 17% Undervalued
The most followed narrative on Abbott Laboratories pegs fair value at about $120, compared with the recent $99.60 close. This frames the current slide as a valuation gap rather than a sign that the story has completely broken.
Expansion of healthcare access in emerging markets, supported by 9% growth in the EPD business in both Q1 and Q2 2026 across India, Latin America and Southeast Asia, points to a larger addressable base for Abbott Laboratories products that can increase revenue and support earnings over time.
See why 187 investors see Abbott Laboratories as 17% undervalued.
Result: Fair Value of $120.26 (UNDERVALUED)
Still, Abbott Laboratories faces two clear swing factors: additional Nutrition legal costs that pressure margins and any reset in the rich P/E multiple analysts assume.
Find out about the key risks to this Abbott Laboratories narrative.
Another View: Cash Flows Point To A Richer Price
There is a catch. While the prevailing Abbott Laboratories narrative leans on a fair value of about $120 based on earnings and growth assumptions, the Simply Wall St DCF model points to a future cash flow value closer to $80.29 per share, which frames the recent $99.60 price as expensive rather than cheap. Which lens do you trust more when the signals conflict?
For readers who want to see how this cash flow view is built line by line and how sensitive it is to the inputs, Look into how the SWS DCF model arrives at its fair value..
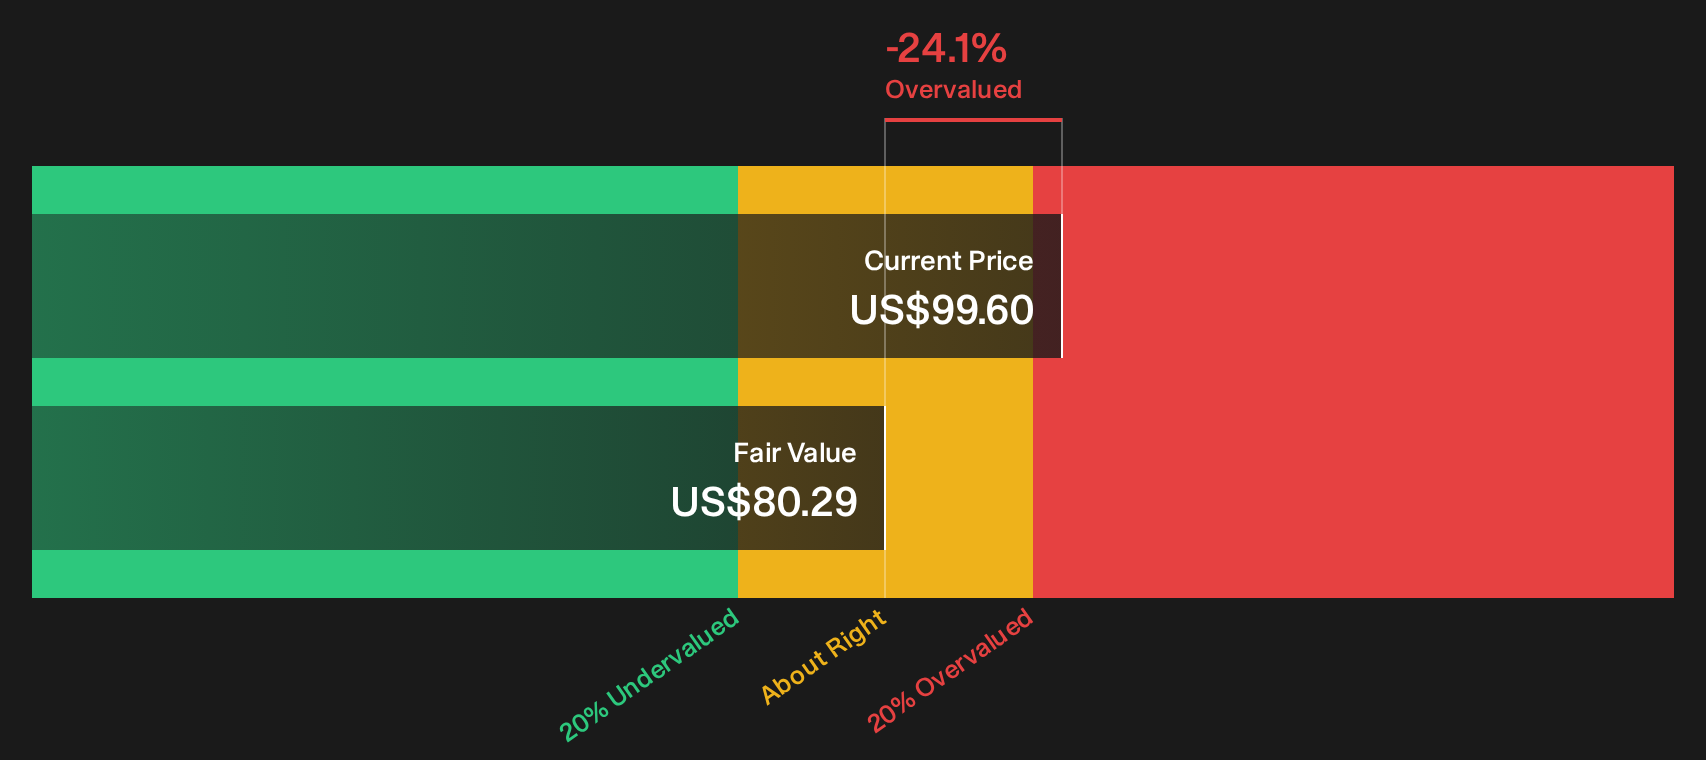
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Abbott Laboratories for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Abbott Laboratories can feel confusing, so move fast, review the numbers, and weigh both the upside and the red flags in 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Abbott Laboratories?
If Abbott Laboratories has your attention, do not stop here. Fresh ideas often come from looking just outside your comfort zone.
- Target consistent income by scanning sturdier payers through 8 dividend fortresses, which focuses on higher yields backed by solid financial profiles.
- Hunt for potential value opportunities using the 28 high quality undervalued stocks, which filters for quality businesses pricing in more caution than their fundamentals suggest.
- Prioritise peace of mind and capital preservation with the 31 resilient stocks with low risk scores, which highlights companies scoring well on resilience and downside protection.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com