


What Leonardo DRS Stock's UK Radar Expansion Means For Shareholders
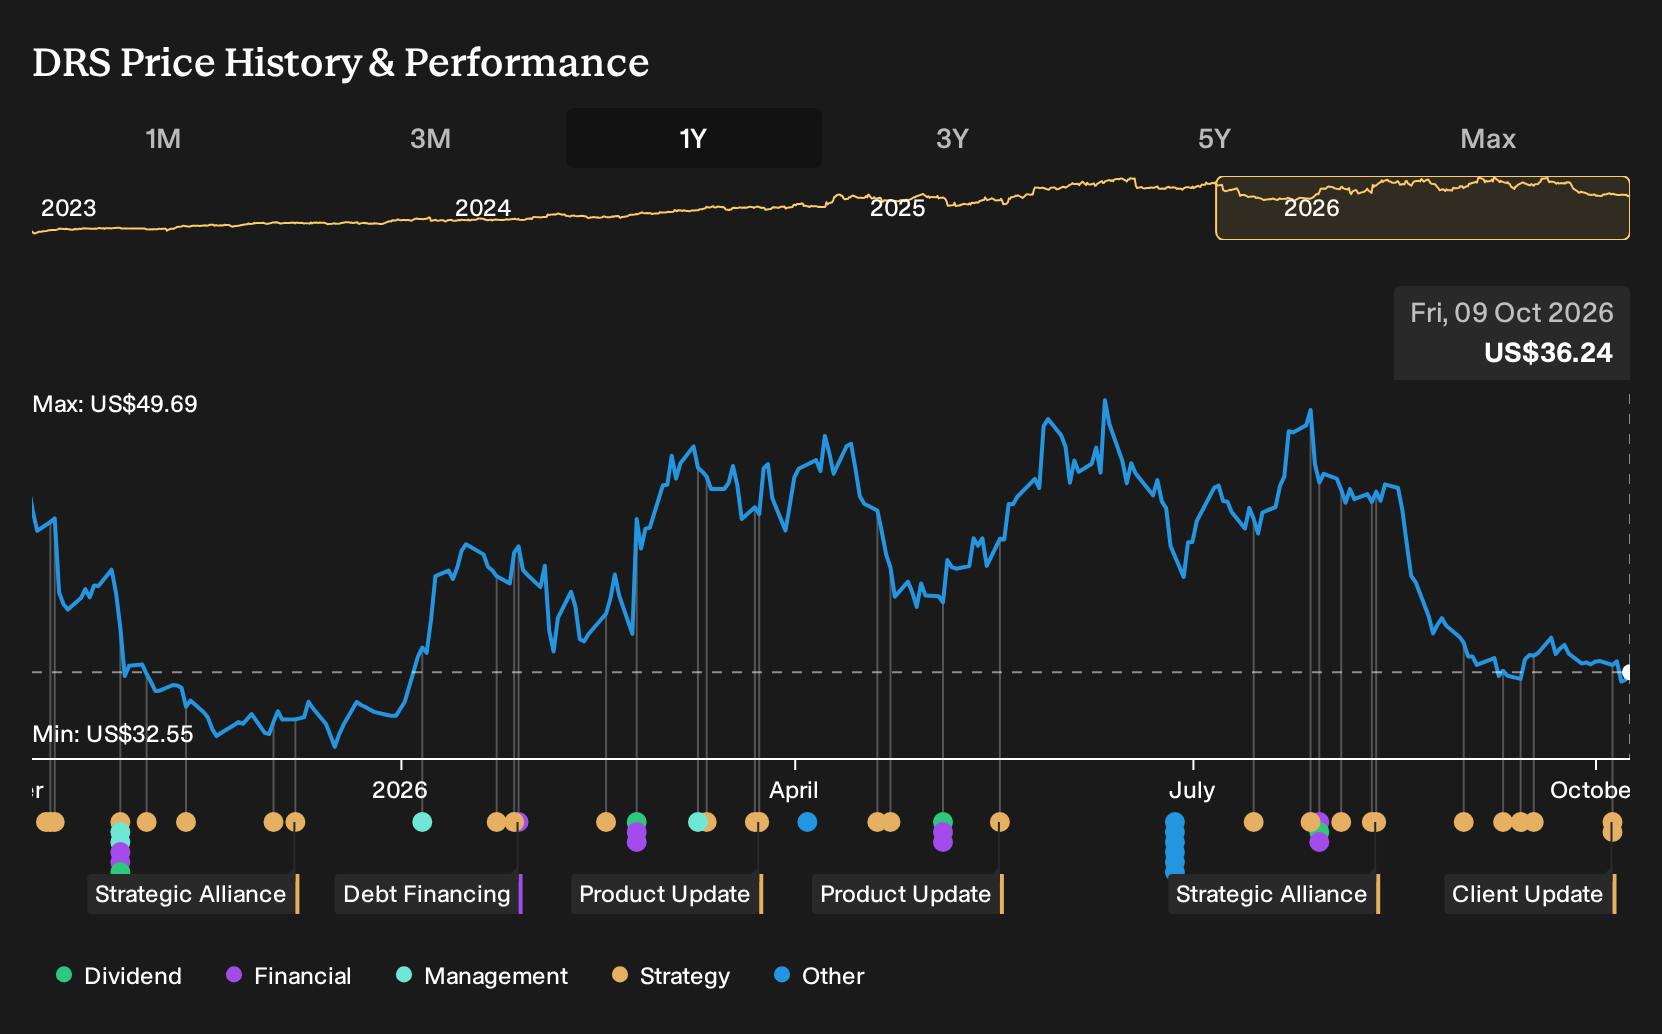
- Leonardo DRS recently completed final training and delivery of INOD Block III thermal weapon sights for the Australian Army and created DRS UK to begin local tactical radar production for defence customers in Britain and Europe.
- These moves show Leonardo DRS expanding further into allied export markets with fielded products in both advanced thermal sights and high-volume tactical radars.
- This article examines how Leonardo DRS’s investment narrative is influenced by UK radar production as a new regional operating base.
Compare Leonardo DRS’s defence-focused expansion with other contractors that screen strongly on balance sheets and fundamentals by scanning our curated list of solid balance sheet and fundamentals (25 results) today.
Leonardo DRS Investment Narrative Recap
To own Leonardo DRS, you need to be comfortable with a defence electronics specialist that leans heavily on execution in radars, infrared sensing and naval power programs, supported by elevated R&D and capex. The Australian INOD Block III delivery and creation of DRS UK both speak to one thing: management is still building around long term demand from U.S. and allied forces.
In the near term, the key positive catalyst many investors watch is the conversion of funded backlog and recent program awards into steady revenue and margin delivery. The main risk sits on the other side of that coin. If higher investment in areas like tactical radars and thermal sights fails to translate into sustained contract flow, cash generation and earnings could come under pressure.
The creation of DRS UK with local tactical radar production is the most directly relevant piece of recent news for this broader thesis. It links directly to the radar and counter UAS opportunity that analysts already highlight as an important potential growth driver, and it extends Leonardo DRS beyond its primarily U.S. revenue base of US$3.4b.
For you as a shareholder or potential shareholder, the UK radar facility looks like an execution test. Management now has to show it can ramp a new regional hub efficiently, support more than 10,000 already fielded radar panels with credible local presence, and win follow-on European work without letting rising R&D and capex dilute returns.
Leonardo DRS’ current analyst storyline points to revenues of US$4.6b and earnings of US$458.3m by 2029, built on an assumed 7.1% yearly revenue growth rate and an earnings increase of about US$136.3m from US$322.0m today.
Discover why Leonardo DRS' fair value indicates a 49% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle on Leonardo DRS focuses on the bullish radar and counter UAS catalyst. The most optimistic analysts were already modeling revenue of about US$4.9b and earnings near US$479.0m by 2029 before this Australia and UK news. You can use that spread in expectations to explore how views might now shift.
Explore 4 other Leonardo DRS fair value estimates, including one that suggests as much as 63% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Leonardo DRS research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Leonardo DRS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Leonardo DRS' overall financial health at a glance.
Looking For More Investment Ideas Beyond Leonardo DRS?
Once you have formed a view on Leonardo DRS, it can help to cross check that thinking against other businesses with different risk and return profiles using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, scan a curated set of 20 high quality undiscovered gems that might not yet be widely followed.
- If capital preservation is a priority, focus on resilience and balance sheet strength with a targeted 31 resilient stocks with low risk scores tailored to steadier profiles.
- If income matters to you, concentrate on cash returns by reviewing a focused group of 8 dividend fortresses built around higher yields.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com