


Did AI Software Expansion Just Shift Nissan's (TSE:7201) Investment Narrative?
- Applied Intuition announced it has expanded its work with Nissan Motor to deploy AI-powered Vehicle OS tools into Nissan's next-generation, scalable in-vehicle software platform, with joint teams in Japan and Silicon Valley supporting AI-defined vehicle development across multiple powertrains.
- This deeper software collaboration gives Nissan Motor a way to simplify in-car electronics, reduce engineering complexity, and reuse a common code base across different vehicle programs. This can influence long-term product economics and the role of software in future revenue streams.
- Investors may now assess how Nissan Motor's investment narrative could be affected by this push into AI-defined, software-centric vehicle development.
Scan how Nissan Motor fits into the wider shift toward AI-defined mobility by comparing it with 92 AI infrastructure stocks positioned to benefit from similar software centric trends.
Nissan Motor Investment Narrative Recap
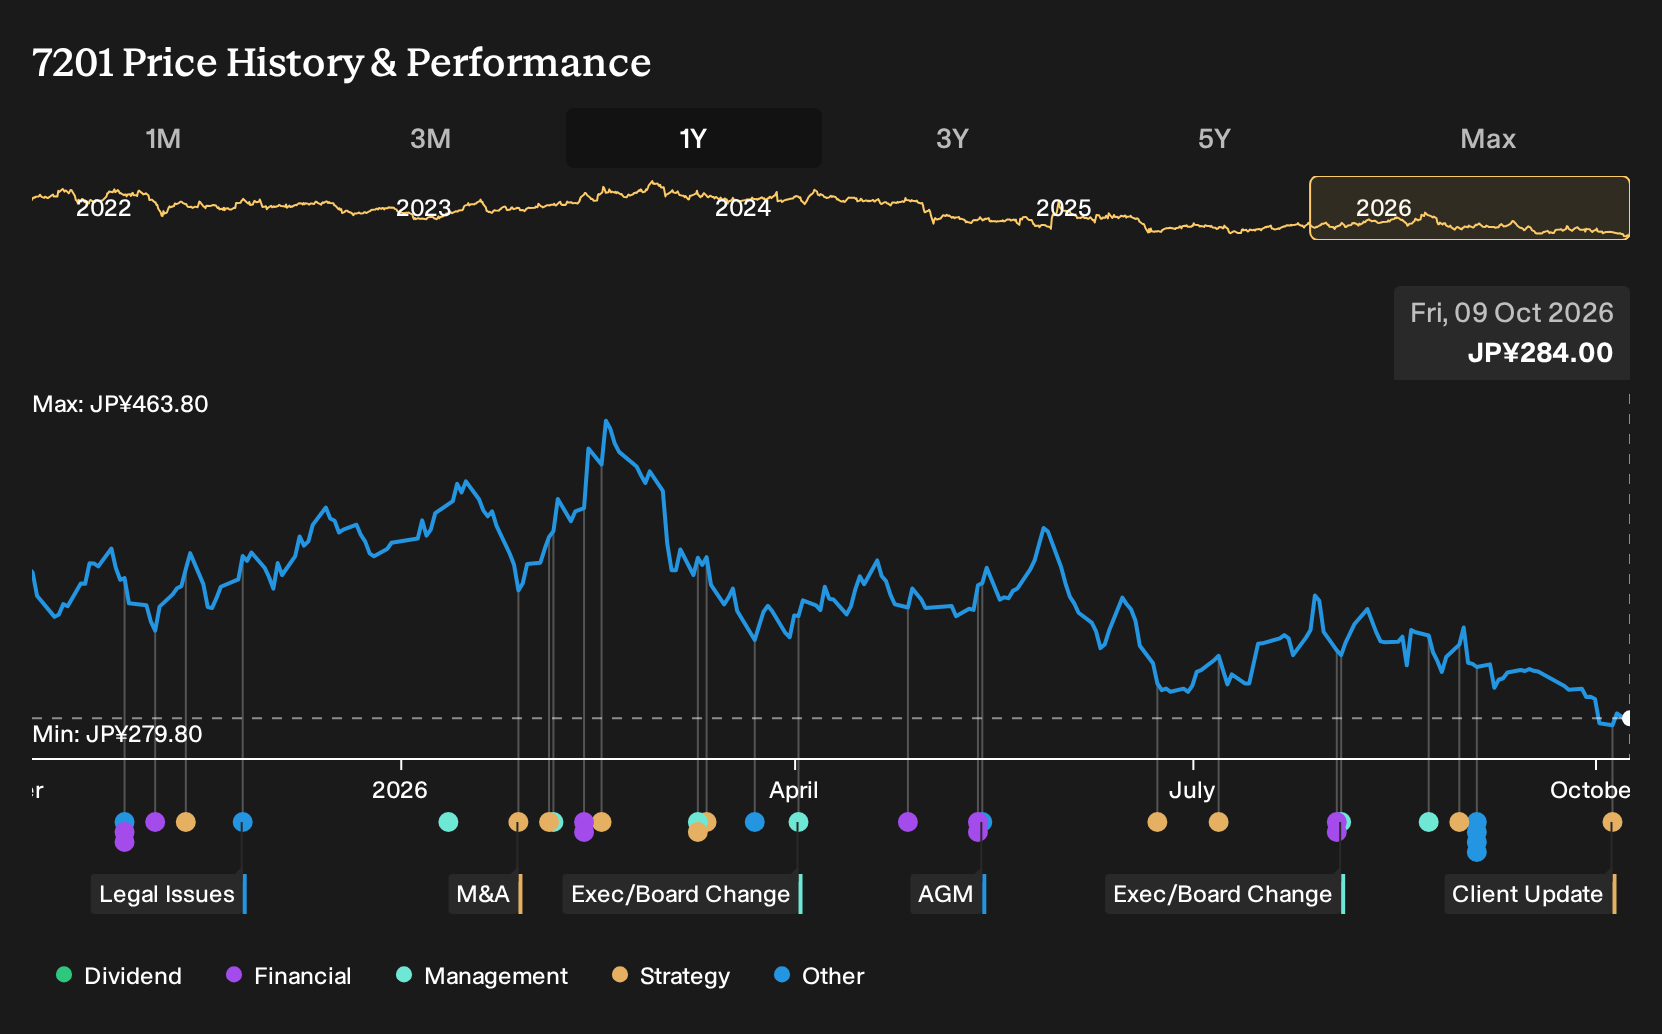
To own Nissan Motor, you need to believe the turnaround in product mix, cost base and technology can outweigh weak recent performance, including a share price that has fallen 53.7% over three years and ongoing losses. The big near term swing factor is whether restructuring plus new EV and higher margin models can stabilize volumes without draining more cash.
The sharp fall in China sales, negative free cash flow and operating losses keep liquidity and balance sheet resilience as the biggest risk. The Applied Intuition partnership may help software execution over time, but it does not immediately change pressure from price competition, FX headwinds and brand perception issues in key markets.
The expanded work with Applied Intuition on an AI defined, scalable in vehicle software platform ties directly into Nissan Motor’s push toward software centric EVs and higher margin models. If execution goes to plan, a common software stack across powertrains could support faster product cycles, lower engineering complexity and potentially more attractive economics on each future vehicle program.
This is still an execution story. Integrating Vehicle OS tooling, retraining engineering teams and managing legacy systems alongside new AI native workflows all carry delivery risk, especially while the group is restructuring plants and dealing with negative cash flow. For investors evaluating Nissan Motor, the key question is whether this software push can realistically support the existing catalysts around EV rollout, cost savings and alliance based scale before liquidity and China competition pressures intensify.
Nissan Motor Analyst Set-Up: What The Numbers Assume
Nissan Motor's current analyst blueprint is built on modest top line expansion and a sharp swing in profitability. Consensus assumes revenue will grow by 3.1% a year over the next three years, while profit margins move from a loss of 3.4% today to a positive 1.4% by 2029. Earnings are projected to shift from a loss of ¥413.6b today to ¥191.3b by 2029, which is an earnings change of about ¥605b. The same forecast period assumes the share count stays broadly flat, so any profit recovery would flow directly into earnings per share rather than being diluted.
Nissan Motor's narrative projects ¥13.4b revenue and ¥191.3b earnings by 2029. This requires 3.1% yearly revenue growth and an earnings increase of about ¥605b from a loss of ¥413.6b today.
Valuation work from the analyst group ties those forecasts to a P/E multiple and an implied fair value range. To align with the ¥384.12 consensus price target, the shares would need to trade on a P/E of 9.6x those 2029 earnings of ¥191.3b. This is compared with a current multiple that is based on loss making results and sits below the wider Japan auto sector at 11.9x. That framework bakes in 2029 revenue of ¥13,443.7b and uses a discount rate of about 11.1% to bring the future cash flows back to today.
There is wide dispersion around those headline numbers, which matters for anyone weighing the Nissan Motor story against the AI defined software roadmap. The most optimistic analysts see earnings at ¥603.6b and a share price of ¥700, while the most cautious expect ¥140.4b of profit and a ¥280 target. That spread reflects uncertainty around the speed and durability of margin repair, including whether software centric vehicles and cost cuts can offset pressure in China, foreign exchange hits and restructuring costs.
Uncover why Nissan Motor's fair value indicates a 35% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For a contrasting view on Nissan Motor, focus on the bullish catalyst around software and digitization. The most optimistic analysts were already pencilling in revenue of ¥14,812.4b and earnings of ¥605.8b by 2029, well above the baseline. The new Applied Intuition deal could prompt those narratives to shift again, in either direction.
Explore 4 other Nissan Motor fair value estimates, including one that suggests as much as 902% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nissan Motor research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nissan Motor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nissan Motor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nissan Motor?
If the Nissan Motor story has sharpened your view on risk, reward and execution, it can help to line it up against other opportunities that fit different profiles on value, quality and resilience.
- For investors prioritizing strong fundamentals at a sensible entry point, compare Nissan Motor with a 12 high quality undervalued stocks that combine cash generation with disciplined balance sheets.
- If capital preservation and steadier profiles sit higher on your list, broaden your watchlist using a 23 resilient stocks with low risk scores that screen well on financial strength and volatility checks.
- When you want to look beyond well covered large caps, widen your search with 74 high quality undiscovered gems that pair healthy metrics with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com