


Is Hitachi (TSE:6501) Undervalued Following Its Anthropic AI Cybersecurity Partnership?
Hitachi (TSE:6501) is stepping further into AI driven cybersecurity, joining Anthropic’s Critical Infrastructure Defense Program as a founding partner to apply Claude models across utilities, transportation and other operational technology systems.
Recent moves in AI security arrive on top of a strong run in the shares, with Hitachi’s 90 day share price return of 20.62% and year to date gain of 11.86% sitting alongside a 1 year total shareholder return of 29.83% and a very large 5 year total shareholder return of about 3.6x. This suggests momentum has been building as investors react to buybacks, cloud reliability wins and now the Anthropic partnership.
Scan AI driven security peers moving on similar themes to Hitachi in our hand picked list of 92 AI infrastructure stocks.
Bulls see Hitachi leaning into AI security and buybacks to justify a richer multiple. Bears see a mature conglomerate priced for too much. Which case does the current valuation support?
Most Popular Narrative: 14% Undervalued
Hitachi closed at ¥5,669 against a widely followed fair value of ¥6,600, so the prevailing narrative sees upside priced into execution on grids and digital platforms rather than deep value.
Strengthening global mandates for sustainability and decarbonization are resulting in very large order backlogs in energy transmission and control systems, with Hitachi Energy’s backlog increasing from about US$11b in 2020 to US$60b in 2025 and projected to exceed US$100b by 2030, which raises visibility on future revenue and supports disciplined pricing power.
See why 23 investors see Hitachi as 14% undervalued.
Result: Fair Value of ¥6,600 (UNDERVALUED)
Still, large grid capex that fails to earn its keep, and any prolonged tariff related investment freeze, could quickly weaken confidence in the Hitachi upside story.
Find out about the key risks to this Hitachi narrative.
Another View: Multiples Paint A Richer Picture For Hitachi
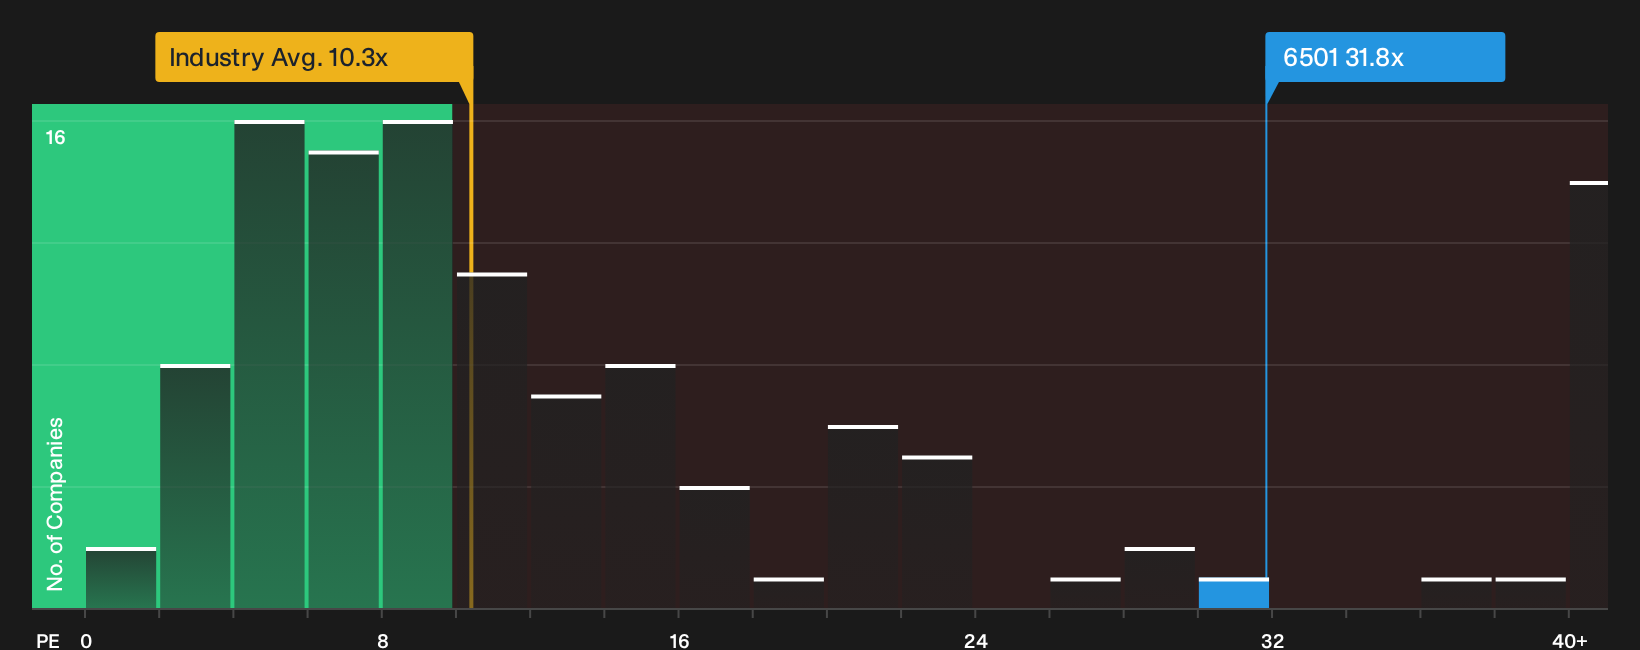
While the popular story has Hitachi trading below a ¥6,600 fair value, the current P/E of 31.8x is far above both Asian Industrials at 10.3x and closer peers at 12.7x. Even against a fair ratio of 32.1x, that leaves very little room for error. Is this really a margin of safety, or just paying up for a crowded theme?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Hitachi’s value case create room for debate, so move quickly, review the full data, and weigh up the 2 key rewards
Looking For More Investment Ideas Beyond Hitachi?
If Hitachi has you thinking harder about where to put fresh capital next, do not stop at one opportunity when a wider field is right in front of you.
- Target stability first and focus on businesses with stronger cushions against shocks using a 23 resilient stocks with low risk scores.
- Hunt for pricing power by scanning a 74 high quality undiscovered gems that combines quality fundamentals with quieter market attention.
- Prioritize financial resilience and shortlist companies with healthier funding profiles through a list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com