


Can Snap (SNAP) Justify Its Valuation After The Specs Stake Push?
Snap Inc. has seen its share price move around sharply in recent years, and that volatility puts a spotlight on a simple question for investors who care about valuation. Is the current US$6.23 price tag adequately supported by the sales Snap is generating today and what the business may realistically add over time?
- Snap’s share price has fallen 91.9% over the past 5 years, which puts the focus squarely on whether the revenue the company produces can support even the current, much lower, market value.
- The push from Blue Duck Capital Partners to sell a roughly 20% stake in the Specs augmented reality glasses unit at a proposed US$5b valuation can reshape how investors think about Snap’s future sales mix and the funding needed to pursue that opportunity.
- There is a second opinion on Snap worth weighing. See what analysts think Snap's shares could be worth.
The issue now is whether Snap’s current market price lines up with what its sales justify when set against the Fair Ratio benchmark.
If you want to balance Snap’s sharp swings with other ideas that meet clear, rules based criteria, a focused stock screen is a useful second starting point for research, such as 28 high quality undervalued stocks.
Does Snap Look Undervalued on Sales?
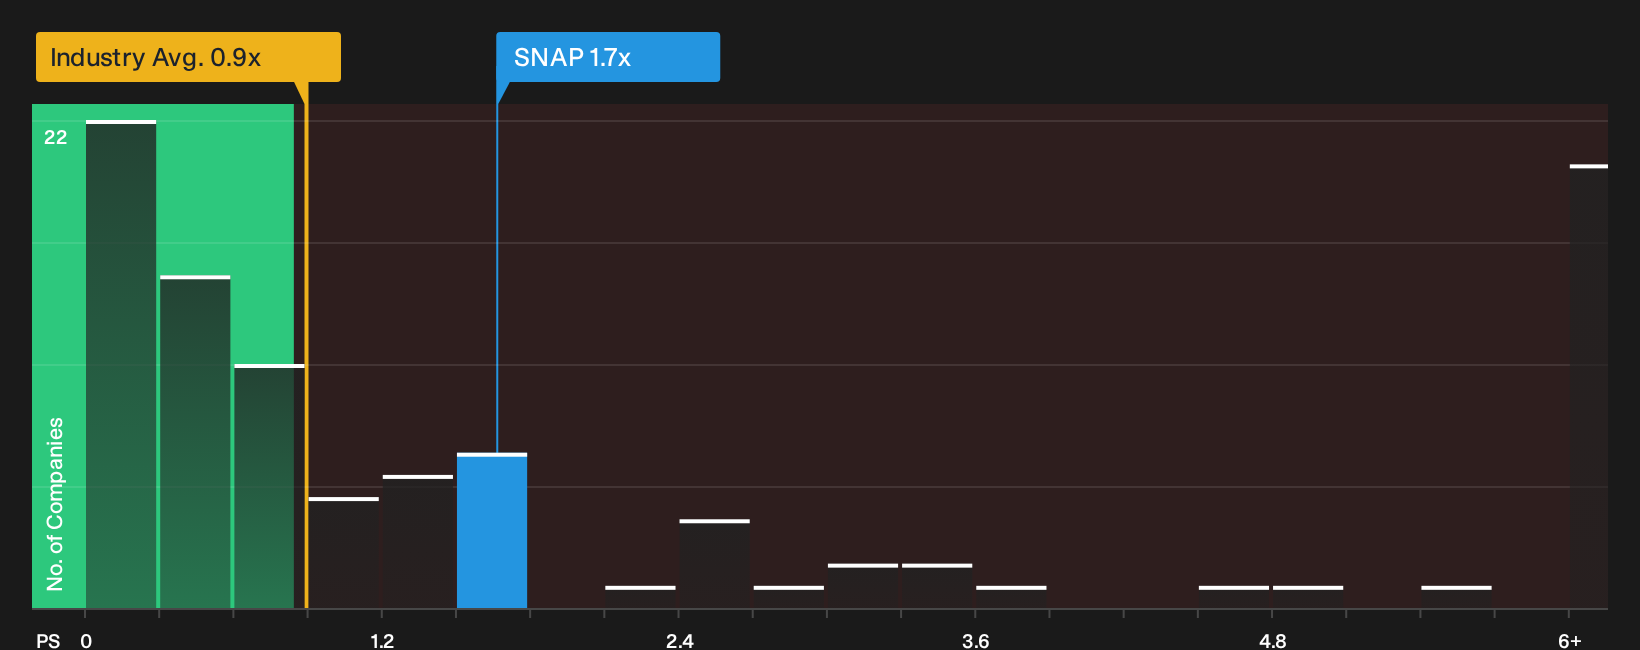
P/S suits Snap because investors are still weighing it more on revenue potential than on current earnings. On this yardstick, the stock trades on a P/S of 1.7x, compared with an Interactive Media and Services industry average of roughly 0.9x and a broader peer group closer to 7.6x. That leaves Snap priced at a premium to the typical industry player but below the level attached to faster growing or more profitable platforms in the wider peer set.
The Fair Ratio model, which adjusts the P/S level you might expect for Snap based on its margins, size, sector and risk profile, points to the current 1.7x as undervalued rather than stretched. Because the recent Blue Duck push highlights the option to ring fence Specs funding with outside capital, the market is still assigning a discount to the headline P/S that leaves room for different scenarios on how the AR business is financed and monetised. Explore the numbers behind Snap's P/S valuation.
The Snap Narrative: What Would Justify Today's Price?
Snap Narratives on Simply Wall St pick up where the valuation puzzle leaves off by explaining which future paths for growth, profitability and earnings power would need to hold for the stock to be worth materially more or materially less than today’s price. Each scenario assigns a fair value to a specific mix of potential catalysts and risks so you can track over time which version of Snap's story seems closest to reality on the Community page.
Community views on Snap are split between optimism about augmented reality and concern that advertising and user-related challenges continue to weigh on the company.
Bull case: 15% undervalued
"Monetization progress in subscription products such as Snapchat+ and Lens+, alongside growing engagement with Spotlight and creator-driven content, is diversifying Snap's revenue base."
Discover why this Narrative puts Snap at 15% undervalued.
Bear case: 25% overvalued
"Despite multibillion-dollar investments in augmented reality and cutting-edge hardware, the hardware market is nascent and unproven, exposing Snap to prolonged periods of high R&D and infrastructure costs."
Explore why this Narrative puts Snap at 25% overvalued.
One more piece of the Snap puzzle
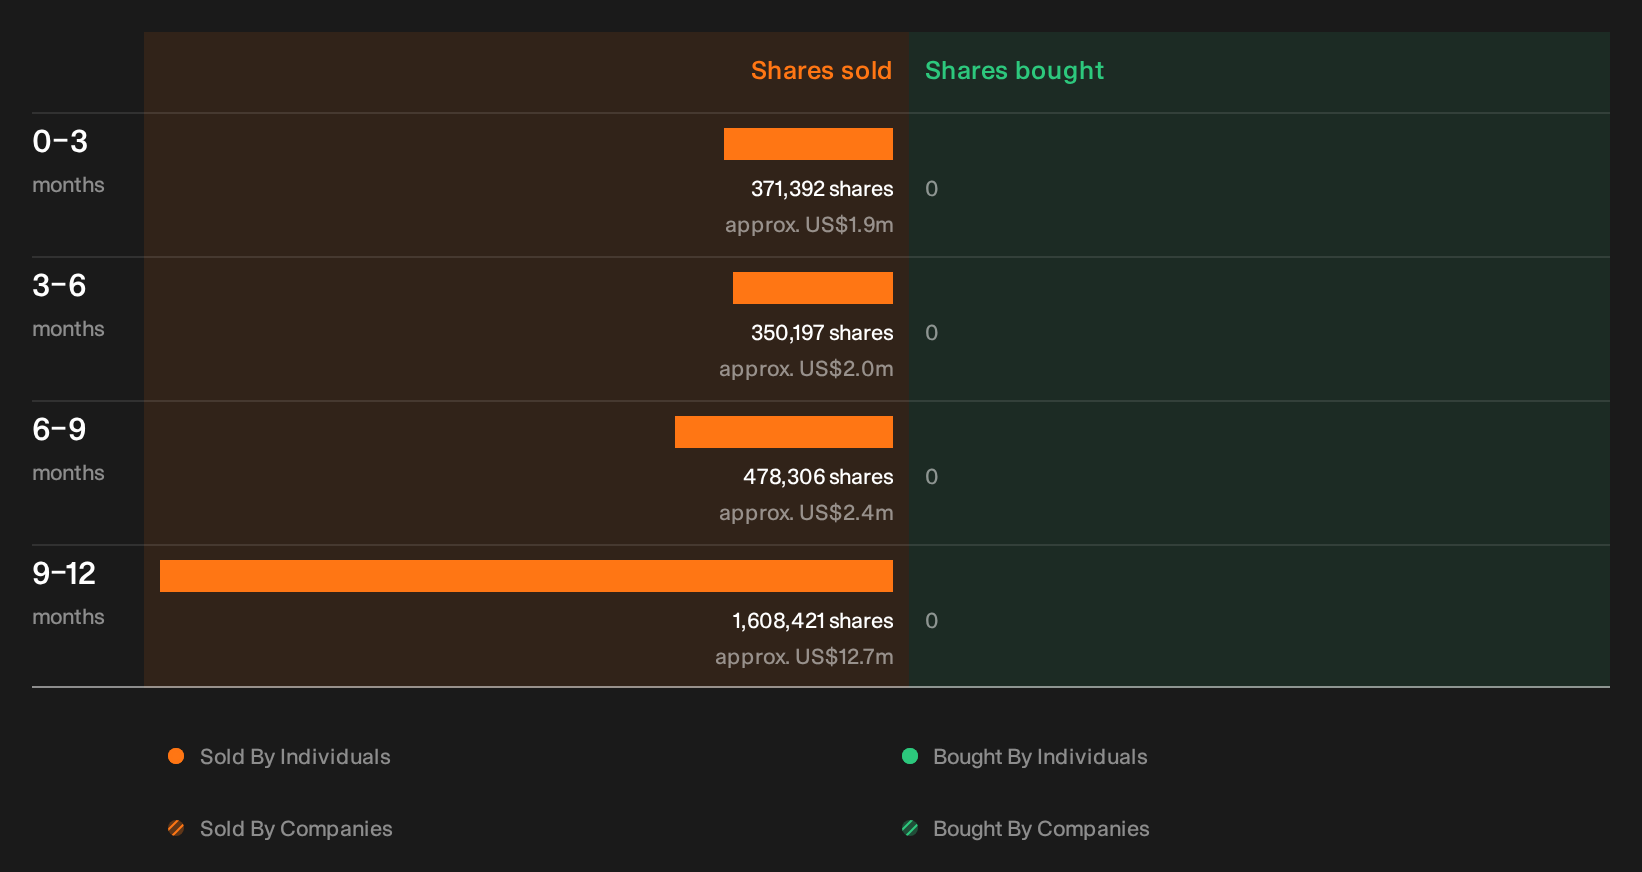
There is one corner of Snap that this review has not touched yet: recent share activity by people inside the business, and the specific sellers, volumes and possible signals are all there for you to unpack. See the recent insider selling flagged for Snap.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com