


CSW Industrials (CSW) Following Infrastructure Demand Narrative Looks Cheap Against Fair Value
CSW Industrials (CSW) drew investor attention after its recent share price performance, with the stock closing at US$286.62 and showing mixed short term moves over the past week and month.
Stepping back from the latest dip, CSW Industrials has seen the share price soften over the past month. However, the 90 day share price return is still in positive territory, and the 1 year total shareholder return of 20.01% points to stronger longer term momentum.
Scan beyond CSW Industrials and compare its recent momentum with a curated set of 27 high quality undervalued stocks that also combine balance sheet strength with positive total return profiles.
CSW Industrials has cooled off in the near term even after a strong 1 year run. This puts the focus squarely on whether most of the upside is already gone or if valuation still leaves meaningful room ahead.
Most Popular Narrative: 19% Undervalued
On the most followed view of CSW Industrials, the current share price of $286.62 sits below an estimated fair value of $351.86. This puts the focus on whether the underlying business performance and cash generation can justify that gap when discounted at 8.92%.
Sustained U.S. infrastructure upgrading and urbanization continues to expand the base of aging buildings needing renovation and maintenance, which underpins long-lived, recurring demand for CSWI's consumables and specialty construction products. This creates a stable and expanding revenue base with visibility for long-term earnings growth.
See why 2 investors see CSW Industrials as 19% undervalued.
Result: Fair Value of $351.86 (UNDERVALUED)
Still, the bullish CSW Industrials story hinges on acquisitions continuing to pull their weight, and on margin pressures from tariffs and mix not becoming a lasting drag.
Find out about the key risks to this CSW Industrials narrative.
Another View: CSW Industrials On Richer Market Multiples
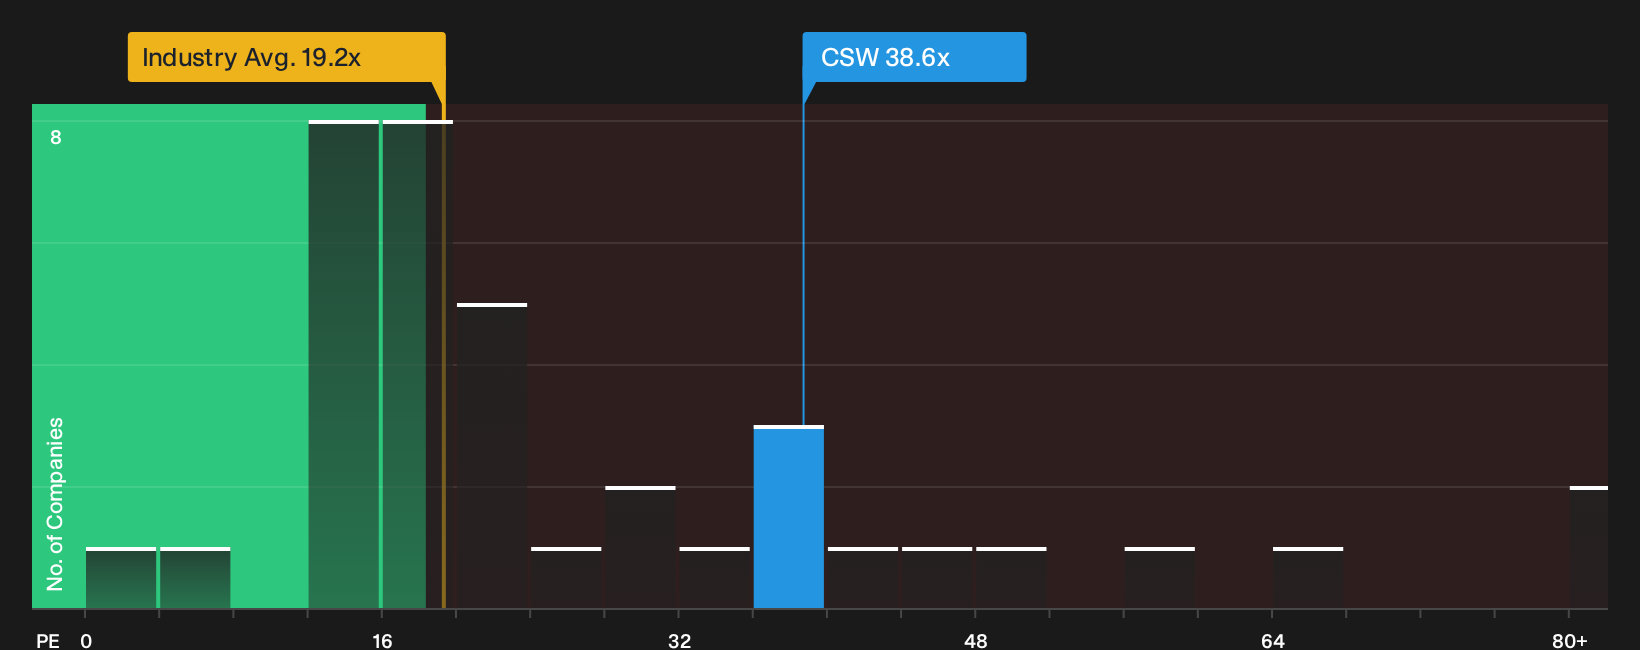
The SWS DCF model points to upside for CSW Industrials, yet the market is already paying a steep price on earnings. The current P/E of 38.6x is higher than both the peer average of 30.5x and a fair ratio of 22.4x, which implies meaningful valuation risk if sentiment cools.
That kind of gap can close in more than one way. It can happen through earnings catching up to the price, or through the share price drifting closer to that fair ratio. The question for investors is which path feels more realistic based on their own expectations for CSW Industrials.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on CSW Industrials so far. If you want to move beyond the headlines and judge for yourself, start with its 2 key rewards and 3 important warning signs.
Looking for more CSW Industrials sized opportunities?
If CSW Industrials has you thinking about what else might fit your portfolio, use the screeners below to pressure test ideas before you commit capital.
- Target reliable cash payers by scanning for income ideas across 8 dividend fortresses with yields that clear a meaningful hurdle.
- Hunt for resilient balance sheets and robust fundamentals with the list of solid balance sheet and fundamentals (25 results) so weak finances do not blindside your returns.
- Get ahead of the crowd by tracking 20 high quality undiscovered gems that pair quality metrics with relatively low investor attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com