


Plug Power (PLUG) Stock Looks Pricey Even After A 95% Slide
Plug Power has seen a steep share price slide in recent years, and that drop puts fresh focus on a simple question for investors who still follow the story: Is the current valuation of the hydrogen player adequately supported by its sales profile?
- Over the past 5 years the Plug Power share price has fallen 94.6%, which puts a lot of weight on whether the remaining market value lines up with the revenue it generates.
- The new partnership with Arcadia eFuels to supply more than 1 gigawatt of electrolyzers for e-SAF projects can shape how investors think about Plug Power's future revenue potential and the timing of any improvement in cash generation from its sales base.
- There is a second opinion on Plug Power worth weighing. See what analysts think Plug Power's shares could be worth.
The issue now is whether Plug Power's US$1.73 share price is justified by its sales when compared with a Fair Ratio benchmark.
If you want to stress test the same sales based valuation question across a wider field of companies, a good next step is to review the 27 high quality undervalued stocks.
Does Plug Power Look Pricey on Sales?
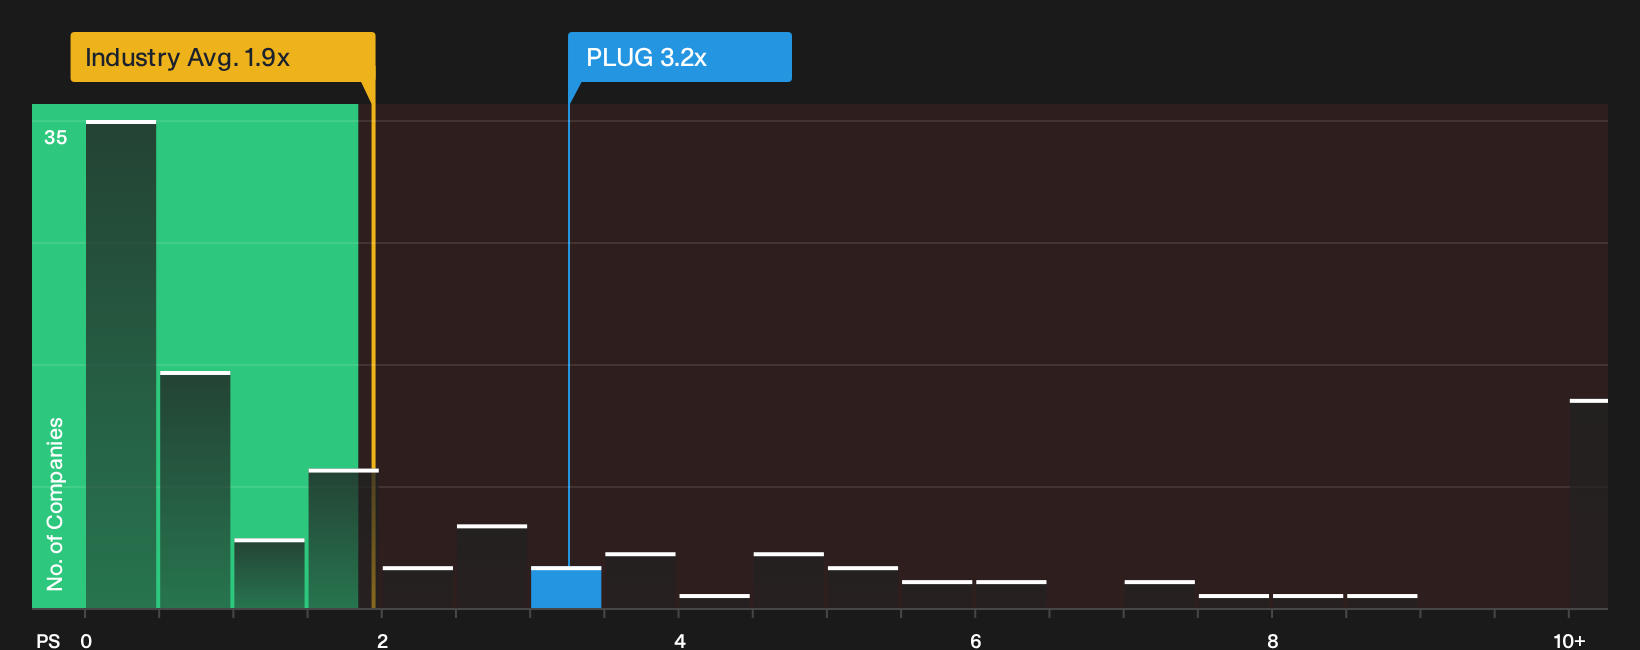
P/S suits Plug Power because investors are mainly weighing the value of its revenue stream rather than current earnings. On this measure, the stock trades at about 3.2x sales, compared with roughly 1.9x for the wider Electrical industry and about 1.9x for its direct peer group. That is a clear premium for every dollar of Plug Power revenue relative to many alternative hydrogen and electrical equipment plays.
The Fair Ratio, which adjusts the multiple you might expect for Plug Power given its growth profile, margins, size and risk, sits well below the current P/S so the shares screen overvalued on this framework. The model is heavily penalising the business for its recent free cash flow losses and risk factors, so the gap looks more like a warning flag about how full the valuation is than a precise target level. Despite the fresh Arcadia eFuels agreement giving the story new project visibility, the present 3.2x sales tag still prices the stock well above many peers on a simple revenue basis. Explore the numbers behind Plug Power's P/S valuation.
The Plug Power Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Plug Power valuation puzzle leaves off by spelling out which combinations of future growth, profitability and earnings power would need to play out for the stock to be worth meaningfully more or less than it is today. Each one treats fair value as a specific thesis about Plug Power's business that you can track over time on the Community page to see how it holds up.
Plug Power followers are currently split between those who see a turnaround story with policy tailwinds and those who focus on funding risk and tougher alternatives.
Bull case: 51% undervalued
"Operational improvements such as gross margin enhancements from Project Quantum Leap, restructuring, facility consolidation, and favorable hydrogen supply agreements are already yielding sharply better margins..."
Discover why this Narrative puts Plug Power at 51% undervalued.
Bear case: 131% overvalued
"Persistent negative operating cash flow, high working capital requirements, and the need for repeated access to external debt facilities signal continued risk of shareholder dilution..."
Explore why this Narrative puts Plug Power at 131% overvalued.
One more Plug Power angle that can change how you read the story
Share prices and revenue multiples only tell part of the Plug Power story, because the people steering the business and the way their pay is structured can heavily influence what happens next. See who runs Plug Power and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com