


Round One And 2 More Japanese Insider Owned Growth Stocks
Runaway US Treasury yields are pressuring global equities, so many investors are looking closer to home for growth that is closely aligned with owner interests. Fast growing Japanese companies where insiders hold meaningful stakes can offer that blend. Managements that think like shareholders often pay close attention to capital allocation and risk. This article highlights three such stocks from our screener and explains what makes each one worth a second look.
The three stocks covered below are just a sample, and the full screen surfaced 97 more fast growing Japanese businesses with high insider ownership and equally compelling stories that are not covered in this article. To identify and analyze your own highest conviction ideas from that wider universe, head straight into the Fast Growing Stocks With High Insider Ownership screener.
Round One (TSE:4680)
Overview: Round One runs indoor leisure complexes across Japan, combining bowling, arcades, karaoke, billiards, and Spo-Cha sports zones to capture entertainment demand.
Market Cap: ¥339.9b
Round One is expanding its amusement venues in Japan and overseas. Investors get a growth story backed by insider alignment and valuation support, yet everything hinges on how one unseen pressure shapes future venue economics.
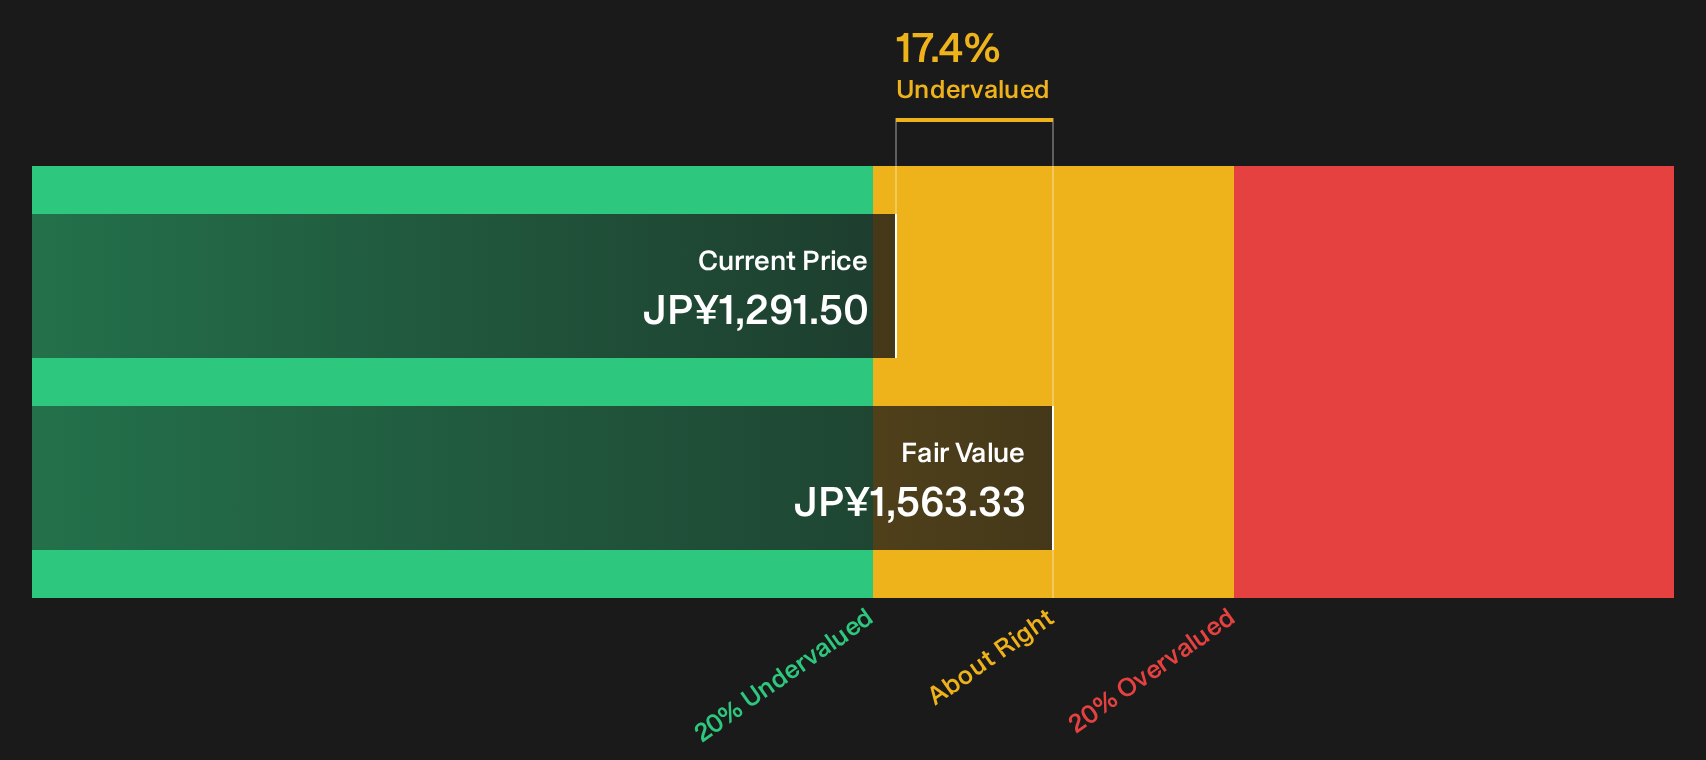
That pressure point is already baked into how management thinks, so go straight to the DCF valuation analysis for Round One to see how those venue economics could reshape the story.
Sansan (TSE:4443)
Overview: Sansan provides cloud-based contact, invoice, and contract management tools that help Japanese businesses manage relationships, documents, and sales workflows more efficiently.
Operations: Sansan generates about ¥46.8b from its Sansan and Bill One segment, with total sales of ¥53.8b almost entirely in Japan.
Market Cap: ¥267.5b
Sansan reported very strong earnings growth and higher margins on ¥53.8b of largely domestic SaaS revenue, while also adding Bill One and Contract One as additional growth levers. Investors who focus on expansion supported by aligned management may want to pay close attention to the potential impact if a single key assumption about SaaS demand and pricing power does not hold.
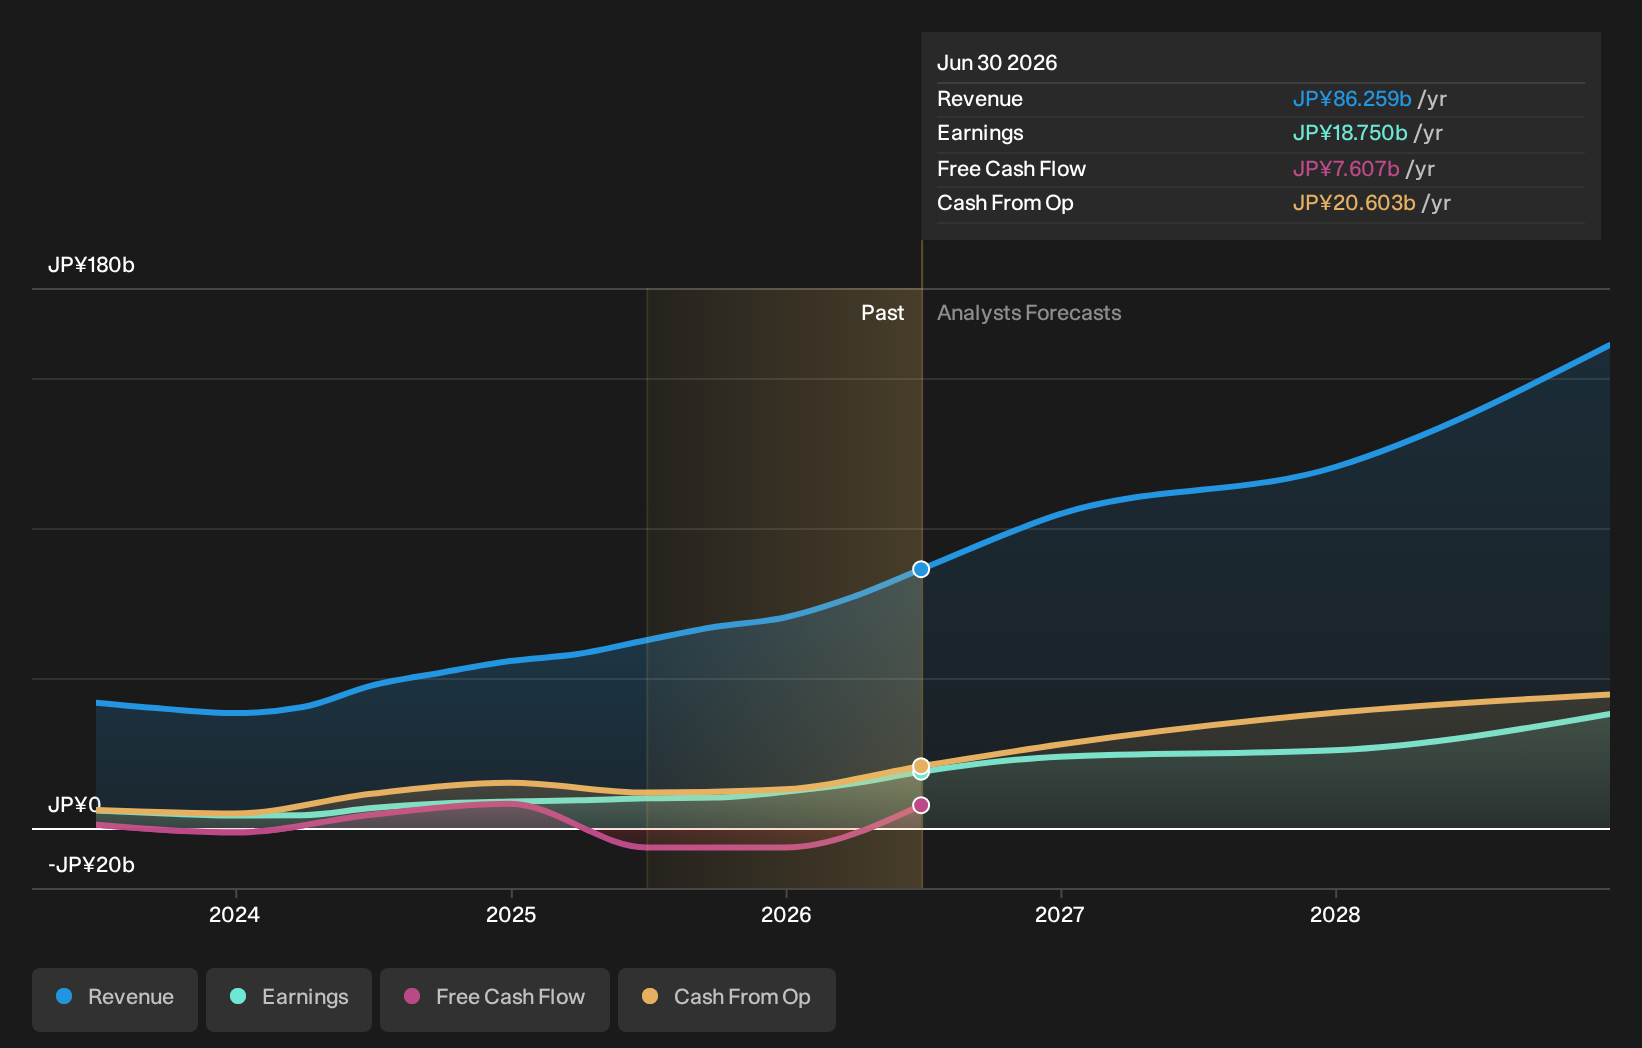
If that assumption is wrong or only partly right, the analyst forecasts for Sansan shows how expectations are shifting before the market fully prices the next chapter.

Micronics Japan (TSE:6871)
Overview: Micronics Japan develops and sells semiconductor test equipment and probe cards that support chip production, alongside body measurement and display inspection tools.
Operations: The business generates about ¥84,868m from its Probe Card Business and ¥1,391m from TE Business, with key sales in South Korea and Taiwan.
Market Cap: ¥632.7b
Micronics Japan combines high growth in semiconductor test equipment with guidance tied to memory demand, plus recent index inclusions that raise its profile. That mix fits a screen focused on fast expanding businesses where insiders are closely aligned and expectations are high. However, conditions could change if one key source of chip testing demand cools faster than management plans for.
If that chip testing demand cools faster than expected, the 2 key rewards and 1 important major warning sign shows where Micronics Japan’s upside and pressure points could be hiding.
Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. By the time every screen lights up with the same tickers, the easier entry points can be gone. Scan these curated lists before momentum gets caught by the crowd and act now.
- Ride potential early-stage breakouts by reviewing a curated group of 1 elite penny stocks with strong financials that pair smaller size with stronger financial footing than typical micro caps.
- Track where real earnings momentum meets AI buzz by working through 35 profitable AI stocks that aren't just burning cash focused on cash generating businesses, not just stories running on headlines.
- Focus on sturdier payouts by scanning a hand built pool of 28 dividend fortresses that combine high yields with balance sheets designed to handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com