


Is Lennar (LEN) Fully Valued As Its Affordability Push Pressures Margins?
Lennar (LEN) has put housing affordability at the center of its playbook, leaning into higher building volume to secure lower construction costs and faster build times while guiding to fewer deliveries and thinner margins next quarter.
The recent affordability update comes at a difficult time for Lennar. The 1-day share price return of 1.93% to US$77.60 only partially offsets a 7-day share price decline of 5.49% and a year-to-date share price fall of 25.54%. The 1-year total shareholder return is down 32.43%, which suggests that investors have been marking the stock down as they reassess both growth potential and margin risk associated with this volume-first approach.
Spot opportunities across the broader housing theme by scanning our hand picked list of solid balance sheet and fundamentals (25 results) that could handle affordability pressure with more resilience than Lennar.So the stock has already reset on worries about thinner margins and slower deliveries. Does that mark a reasonable entry point now, or does waiting for a deeper discount on Lennar make more sense?
Most Popular Narrative: 2% Undervalued
Lennar's most followed valuation view puts fair value at $79.00, only slightly above the latest close of $77.60. This frames today’s debate as a fine balance between margin risk and long term earnings power.
The analysts have a consensus price target of $79.0 for Lennar based on their expectations of its future earnings growth, profit margins and other risk factors. However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $120.0, and the most bearish reporting a price target of just $63.0.
See why 45 investors see Lennar as 2% undervalued.
Result: Fair Value of $79.00 (UNDERVALUED)
Still, higher mortgage rates squeezing Lennar’s first-time buyers and land banking costs pressuring margins could both challenge the idea that today’s modest discount is enough.
Find out about the key risks to this Lennar narrative.
Another Take On Lennar’s Valuation
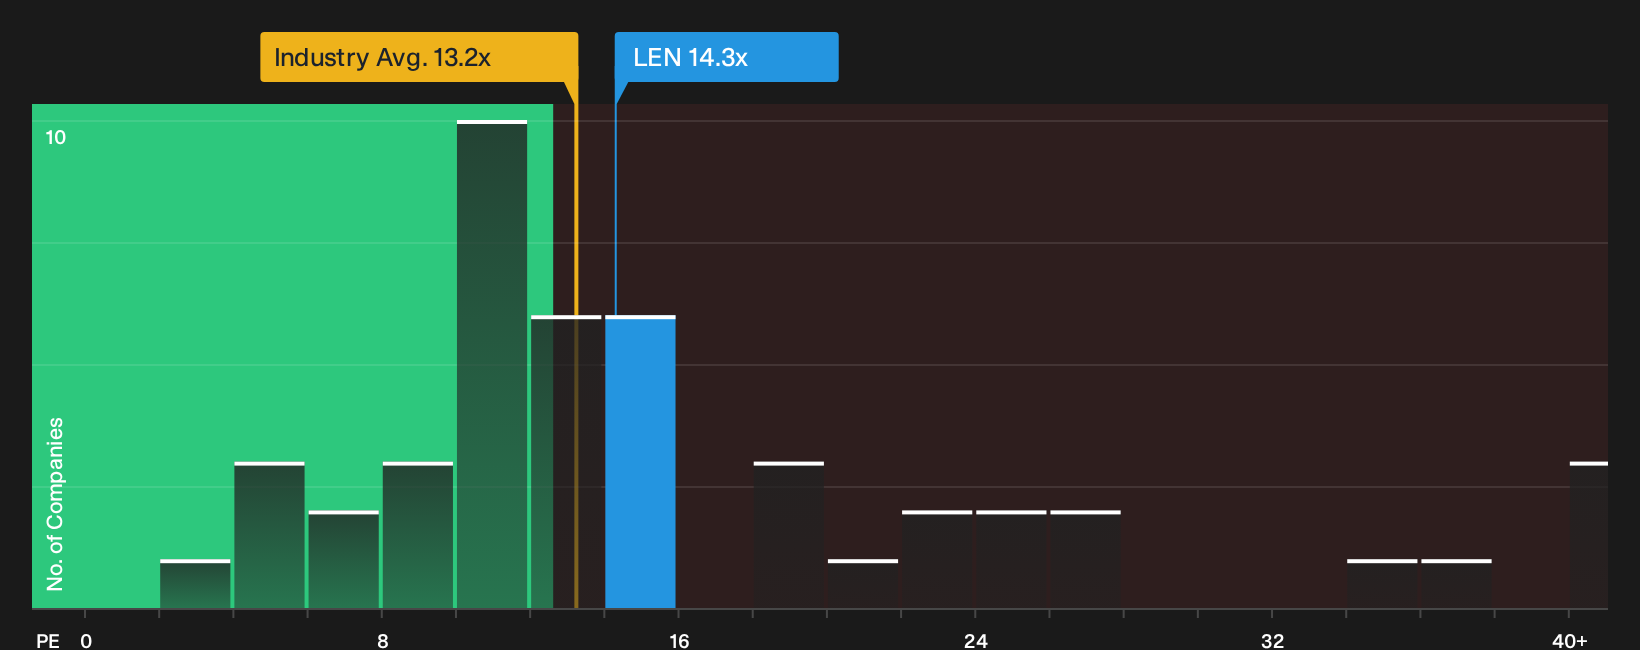
The first lens suggests Lennar appears about 2% undervalued at a $79.00 fair value. A simple P/E check presents a tougher picture. The stock trades at 14.3x earnings, which is higher than the US Consumer Durables sector at 13.2x and above the peer average at 12x, yet still below a fair ratio of 21.7x. That mix of trading at a premium to today’s group but at a discount to a modeled fair ratio raises a basic question for you: Is the market being cautious about Lennar’s margin and earnings track record, or is it underestimating how the story could change?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of pressure and potential around Lennar feels finely balanced, do not sit on the fence. Take a closer look at both sides of the story, then weigh up the 3 key rewards and 1 important warning sign.
Looking For More Ideas Beyond Lennar?
If Lennar has you rethinking where the best risk and reward might sit, use this moment to widen your hunting ground with a few focused stock lists.
- Target potential mispricings by scanning companies that combine quality with value through our 27 high quality undervalued stocks.
- Strengthen your defensive side by reviewing a 31 resilient stocks with low risk scores that prioritises resilience when conditions get tougher.
- Get ahead of the crowd by checking a 20 high quality undiscovered gems before other investors start paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com