


Omada Health (OMDA), Why Is The Stock Drawing Fresh Attention?
Omada Health Stock Reaction After Recent Price Moves
Omada Health (OMDA) has drawn fresh attention after recent trading, with the share price at US$20.82. The stock is down about 6% over the past month and 11% in the past 3 months.
Short term momentum around Omada Health has cooled, with the 30 day share price return down 6.13% and the 90 day share price return lower by 10.57%. The year to date share price return is up 39.73%, while the 1 year total shareholder return is down 14.07%, pointing to fading recent enthusiasm after a stronger start to the year.
Scan how Omada Health compares with other virtual care players by running through our curated list of 32 healthcare AI stocks that could be setting up their next big move.
After a strong start to 2026 but a weaker stretch in recent months, Omada Health now sits in a more complicated spot for new capital. Do the current valuation markers still tilt the risk reward in favor of buyers?
Most Popular Narrative: 27% Undervalued
On the most followed view, Omada Health screens as undervalued, with a fair value estimate of $28.42 against the current $20.82 share price. This leaves investors to weigh whether the gap reflects opportunity or execution risk around its virtual care plans.
Scaling GLP-1 prescribing alongside the existing GLP-1 Care Track positions Omada as a key coordinator for rapidly expanding obesity therapies, supporting higher average revenue per member and sustained revenue growth.
Deeper integration of AI tools like OmadaSpark, Meal Map and the care team platform should raise coach productivity and member engagement, improving operating leverage and supporting long term expansion in gross margin and EBITDA.
See why 7 investors see Omada Health as 27% undervalued.
The narrative leans on a discount rate of 7.24% to translate those projected cash flows back to today, and then lands on a fair value of $28.42 per share. Against the current price of $20.82, that implies a discount of roughly 26.7% based on that framework.
That story also builds in revenue growth expectations of 19.85% and a profit margin assumption near 7.96%, along with a future P/E of about 59.4x tied to earnings forecasts out to 2029. Analysts are broadly aligned on this outlook, with the lowest target at $22.00 and the highest at $35.00, and the current price sitting about 36.5% below the consensus mark.
For any investor looking at Omada Health today, the key judgment is how comfortable you feel with the combination of higher GLP-1 exposure, heavier 2026 investment plans, and the long run margin goals outlined at Investor Day. The more conviction you have in those elements, the more persuasive that $28.42 narrative fair value will likely look compared with the current share price.
Result: Fair Value of $28.42 (UNDERVALUED)
Still, Omada Health faces real pressure if heavy 2026 investment fails to lift pricing power, or if payer decisions curb appetite for its GLP-1 focused offerings.
Find out about the key risks to this Omada Health narrative.
Another View: Omada Health On Sales-Based Metrics
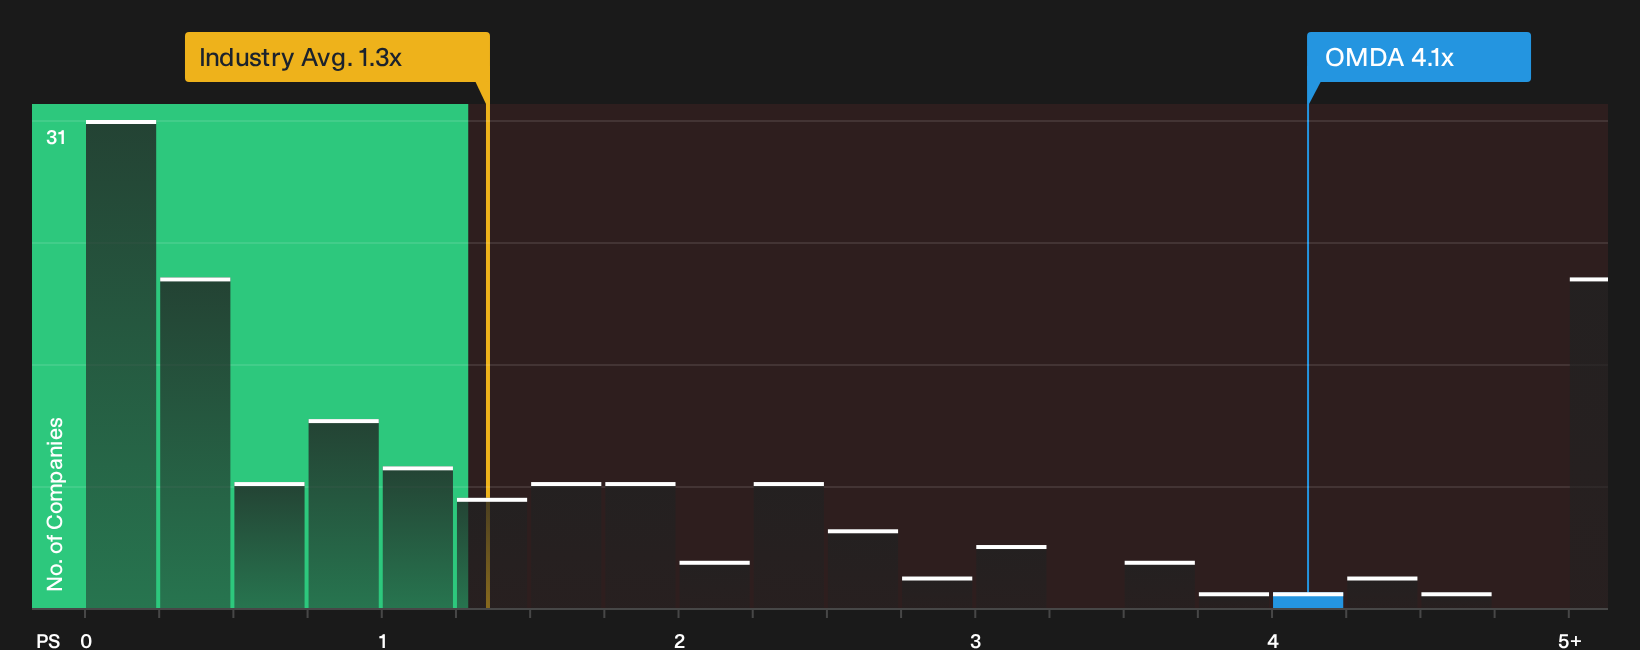
There is a catch. On a simple P/S check, Omada Health trades at 4.1x revenue, while direct peers average around 1.1x and the broader US healthcare group sits near 1.3x. Even versus a fair ratio of 3.9x, the stock screens as expensive. Is that premium a cushion, or a source of downside risk if expectations fade?
For a valuation cross check that leans on these sales multiples and where they could settle over time, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Omada Health can be hard to read, so move quickly from headline takes to your own view by weighing the 4 key rewards and 2 important warning signs.
Looking for more Omada Health investment ideas beyond this stock?
If Omada Health has your attention, do not stop at a single ticker. Put fresh ideas on your radar now so you are not chasing the next move after it happens.
- Target stronger upside potential by scanning companies that combine healthy fundamentals with discounted valuations through the 27 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with robust finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for underfollowed opportunities that the crowd has not piled into yet with the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com