


Should ChatGPT Travel Insurance Quotes Require Action From Manulife Stock Investors?
- Manulife Financial recently launched its first global ChatGPT plugin, the CoverMe tool, which helps eligible Canadian travellers obtain personalized travel insurance quotes in English and French.
- The move puts Manulife Financial’s AI-driven CoverMe plugin directly inside a widely used consumer platform, tightening the link between digital discovery, quote generation and potential policy sales.
- We will now look at how Manulife Financial’s AI powered CoverMe plugin inside ChatGPT could shape the broader investment narrative.
See how Manulife Financial is using AI in insurance, then size up other potential beneficiaries of this shift with our hand picked 6 healthcare AI stocks.
Manulife Financial Investment Narrative Recap
To own Manulife Financial, you need to be comfortable with a global insurer that leans heavily on Asia, retirement markets and fee based asset management. The big near term swing factor is how consistently those growth engines translate into earnings, especially as management pushes more capital light products and digital tools like the new CoverMe plugin to support productivity.
The key risk that sits opposite that thesis is earnings pressure from regulatory and credit factors outside Canada. The expected hit from Hong Kong's MPF centralization, combined with exposure to below investment grade loans and commercial real estate in the U.S., could make near term profit trends choppier even if underlying sales hold up.
The ChatGPT CoverMe launch fits neatly beside Manulife Financial's broader digital push, which analysts link to potential long term margin benefits. It is still a small operational move in dollar terms. The more important test is whether tools like this actually lower acquisition costs and keep customers inside the Manulife ecosystem instead of price shopping across providers.
Among prior developments, the acquisition of Comvest Credit Partners is most relevant here because it also targets fee based, capital light earnings. If Manulife can execute on Comvest integration while scaling AI powered distribution like CoverMe, that combination could support more stable fee income over time. Missed integration targets or weak adoption of digital tools would pull against that catalyst.
Manulife Financial's current analyst narrative points to CA$61.5 billion in revenue and CA$8.5 billion in earnings by 2029, based on an assumed 22.9% yearly revenue growth rate and an earnings increase of about CA$2.3 billion from CA$6.2 billion today.
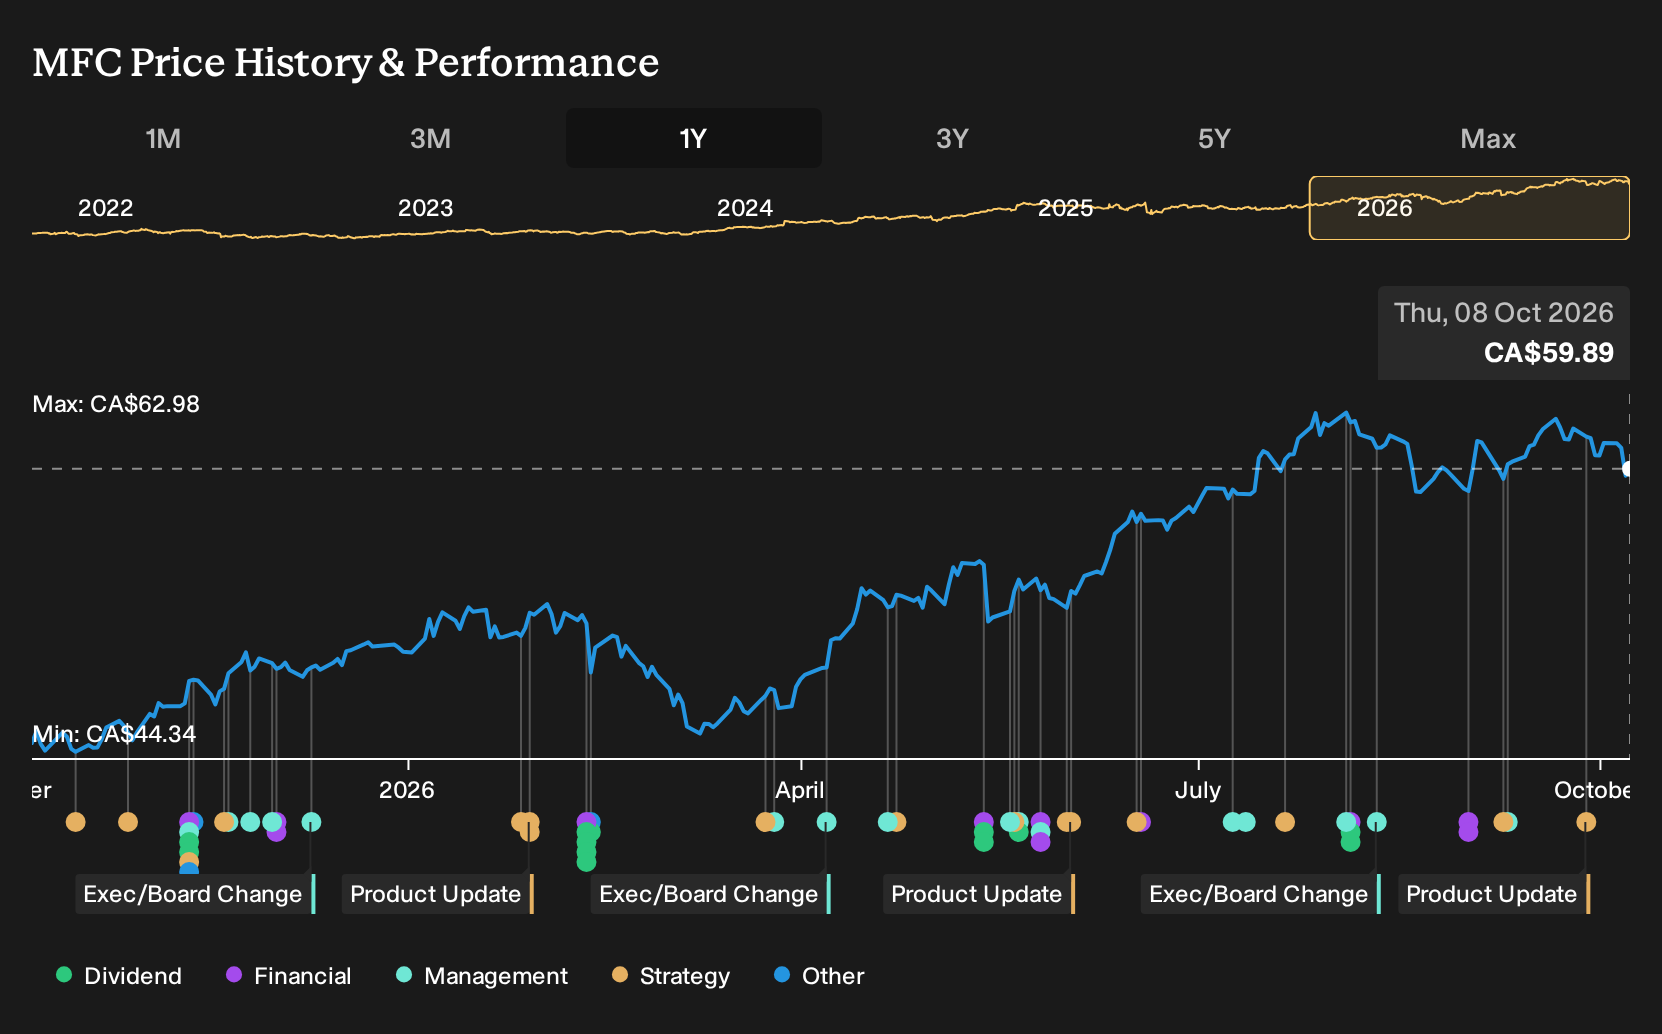
Uncover how Manulife Financial's fair value indicates a 9% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community span roughly CA$65 to more than CA$126 per share, so retail opinion on Manulife Financial is wide. Set that against risks like Hong Kong MPF margin compression and U.S. credit exposure, and you are looking at a story where it pays to examine several competing angles.
Explore 3 other Manulife Financial fair value estimates, including one that suggests it could be worth just CA$65.20.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Manulife Financial research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Manulife Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Manulife Financial's overall financial health at a glance.
Looking for more investment ideas beyond Manulife Financial?
Once you have a view on Manulife Financial, it often helps to compare it with other opportunities that suit different risk, income and balance sheet preferences. The Simply Wall St Screener is a quick way to scan for stocks that align with the type of portfolio you want to build.
- If you want potential growth with less balance sheet strain, start with a list of solid balance sheet and fundamentals (7 results). This may offer greater financial resilience through different cycles.
- For investors who care most about capital preservation and steadier risk profiles, consider filtering for 8 resilient stocks with low risk scores that line up with your comfort level.
- If you are hunting for overlooked opportunities with stronger fundamentals, the screener can surface 9 high quality undiscovered gems that are not yet widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com