


PolyPeptide Group (SWX:PPGN) As Samsung Biologics Bid Leaves The Stock Looking Fully Valued
UBS downgraded PolyPeptide Group (SWX:PPGN) to neutral after aligning its valuation view with Samsung Biologics' all cash tender offer. Attention now turns to deal completion and what that implies for the remaining upside.
PolyPeptide Group’s share price has been broadly anchored near Samsung Biologics’ cash offer, with a weaker 90 day share price return of 4.6% contrasting with a much stronger year to date share price return of 82.9%, as event risk around the bid and deal completion now dominates sentiment.
Scan how the Samsung Biologics bid for PolyPeptide Group compares with other potential event driven ideas by running through our hand picked 620 high quality undiscovered gems in a few minutes.
PolyPeptide Group looks like a solid peptide manufacturer on the surface, with recent share gains and a live cash bid in play. The real tension now is whether that strength is already fully priced into the stock.
Price-to-Earnings of 107.6x: Is it justified?
Valuation for PolyPeptide Group looks demanding at first glance, with a P/E ratio of 107.6x sitting well ahead of typical Life Sciences levels while the share price trades near Samsung Biologics' CHF43.9 cash offer.
The P/E multiple compares what investors are paying today for each unit of current earnings. For a contract development and manufacturing business like PolyPeptide Group, which serves pharma and biotech clients with peptide APIs and services, that ratio often reflects expectations for future profit growth, resilience of demand, and the quality of its client relationships.
Forecast data points to earnings growth of 38.5% per year and revenue growth of 13.5% per year. This helps explain why the market is willing to pay a high headline multiple. Yet the stock is described as expensive versus an estimated fair P/E of 35.5x, a peer average of 36.4x, and a global Life Sciences benchmark of 38.2x. Those comparisons suggest investors are currently paying a much richer price for each franc of earnings than both the modelled fair level and sector norms. This is a critical consideration now that the share price is anchored by a live cash bid.
Against that backdrop, PolyPeptide Group screens as expensive on its preferred valuation yardstick, with the P/E ratio far above both fair value estimates and industry averages.
Explore the SWS fair ratio for PolyPeptide Group.
Result: Price-to-Earnings of 107.6x (OVERVALUED)
Still, the Samsung Biologics deal could fall through or face delays, and any change in bid terms might quickly test how much conviction remains in PolyPeptide Group at this valuation.
Find out about the key risks to this PolyPeptide Group narrative.
Another View on PolyPeptide Group’s Valuation
Price looks stretched when using the P/E ratio, yet the SWS DCF model arrives at an estimated future cash flow value of CHF19.97 per share versus the current CHF43.90. That points to PolyPeptide Group trading well above this framework, so how much weight should you really give to a single model?
Look into how the SWS DCF model arrives at its fair value.
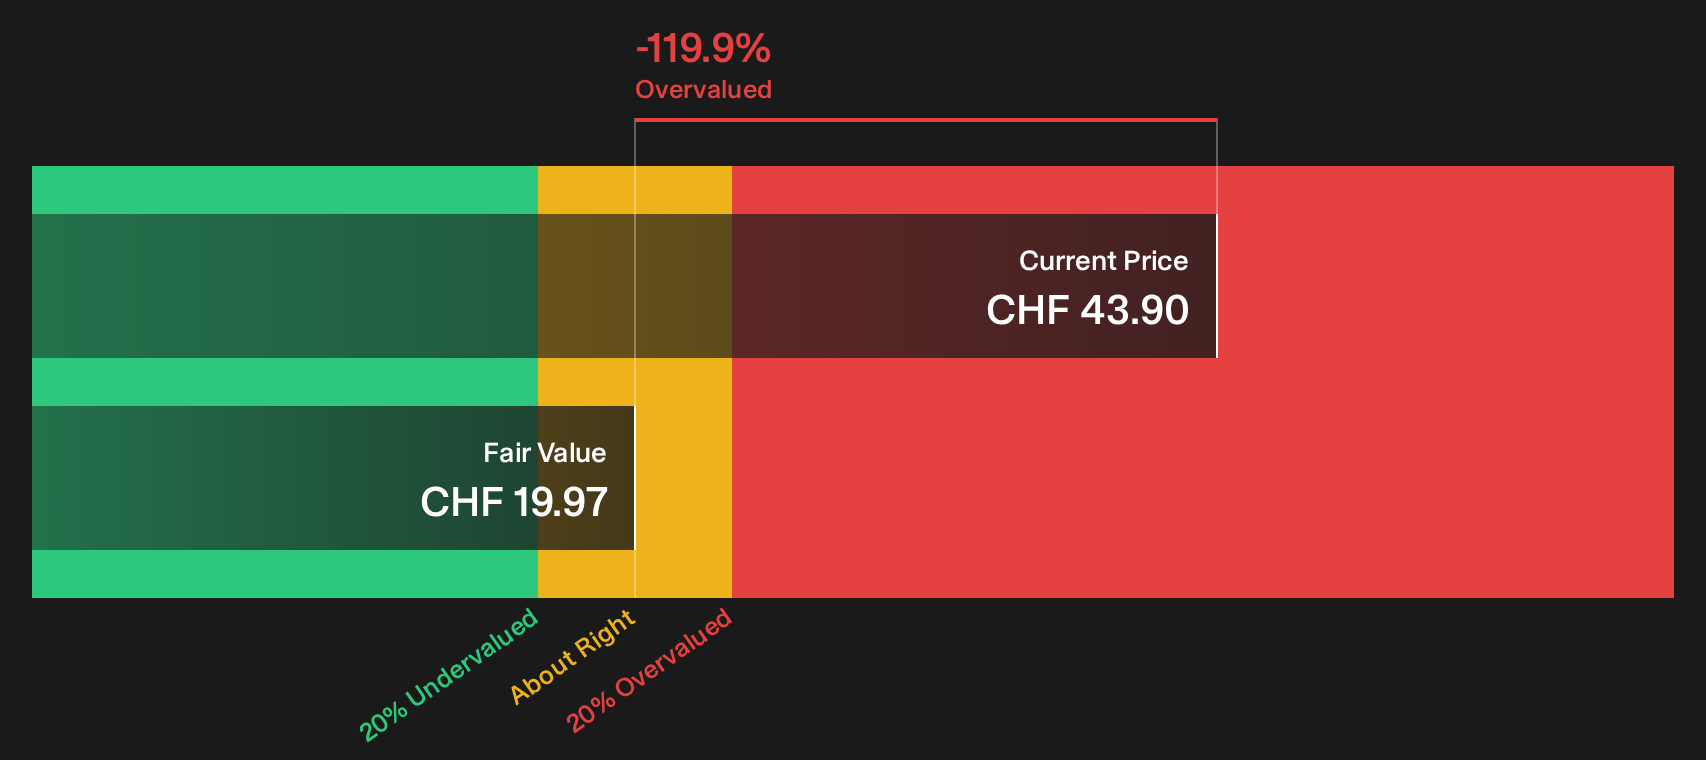
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out PolyPeptide Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment split between a rich P/E and a live cash offer for PolyPeptide Group, it makes sense to check the underlying data yourself and move quickly while the numbers are fresh. To see what the optimistic side of the market is focusing on, review the 2 key rewards
Looking for more investment ideas beyond PolyPeptide Group?
Do not stop your research with PolyPeptide Group. Use the Simply Wall St screener to uncover other potential opportunities before the market spots them.
- Target stronger balance sheets by scanning a curated list of solid balance sheet and fundamentals (206 results) that filters for financial resilience and healthier fundamentals.
- Hunt for better value by reviewing a focused 179 high quality undervalued stocks that highlights companies pairing quality fundamentals with discounted prices.
- Prioritise stability and income by checking a hand picked 225 dividend fortresses that points to companies offering higher yields with robust backing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com