


How Boiler Growth At A. O. Smith Stock Has Changed Its Investment Story
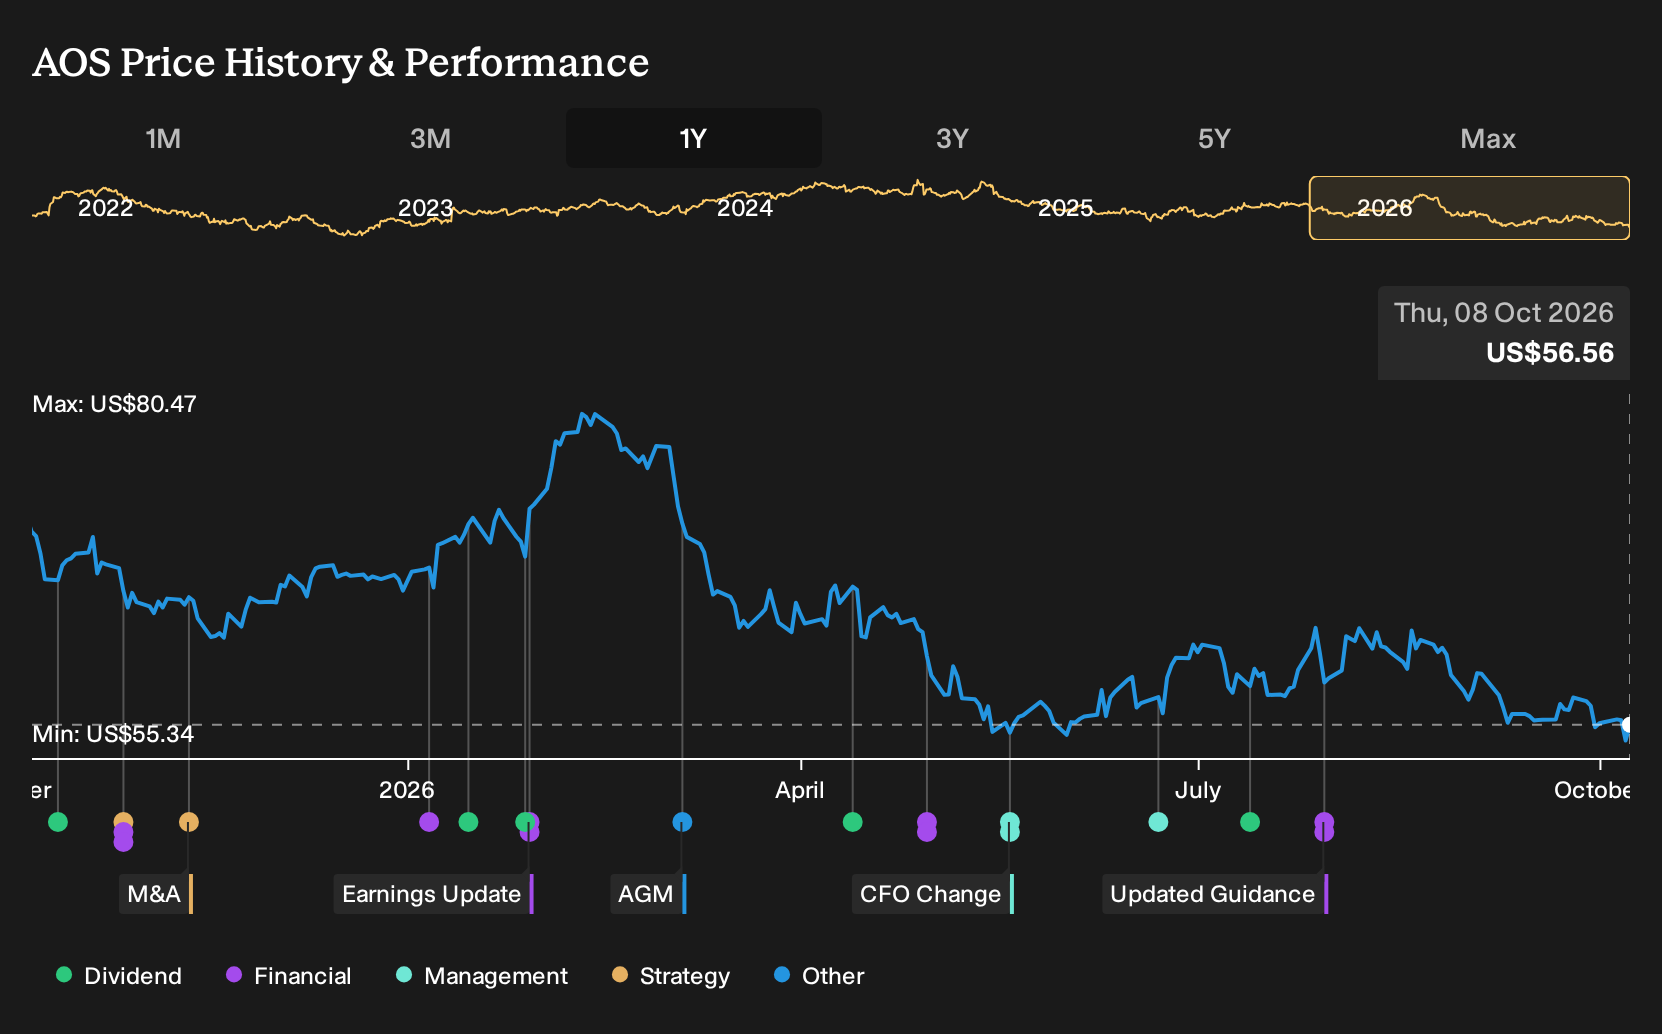
- A. O. Smith recently highlighted strong momentum in its North America boiler business and outlined plans for further 2026 sales growth, supported by the Leonard Valve acquisition, while noting weaker conditions in its Rest of the World operations, especially China.
- The combination of robust North America demand, higher dividends and an expanded buyback program, alongside softer China sales, shows how A. O. Smith is relying on its strongest region to support capital returns while reassessing underperforming markets.
- We will now look at how A. O. Smith’s investment narrative could evolve as North America boiler strength helps offset pressure in China.
A. O. Smith Investment Narrative Recap
For A. O. Smith, the big picture you need to buy into is that a strong North America boiler and water heating franchise can carry the story while the Rest of World segment, especially China, remains under pressure. The recent update reinforces that view. Momentum in North America and the Leonard Valve acquisition underpin the near term operating outlook.
The key near term catalyst is execution in high efficiency boilers and related products in North America, where demand has been described as strong, together with any traction from new commercial offerings. The biggest risk is that China weakness or broader Rest of World profitability issues deepen from already low margins. The latest news does not remove that risk.
The most relevant recent move is A. O. Smith increasing its dividend and expanding the share repurchase program alongside the Leonard Valve deal. Those actions sit on top of first half 2026 free cash flow of US$233 million and a leverage ratio near 25% debt to total capital, which gives the group room to fund both investment and capital returns.
For you as an investor, the important link is how that capital allocation interacts with the operating catalysts. Stronger North America boilers and higher efficiency products could support earnings and cash generation that fund ongoing dividends and buybacks, while any further deterioration in China or higher input costs would test how resilient that cash engine is over the next few years.
A. O. Smith's current earnings are $500.3 million and analysts project earnings of $605.5 million by 2029, which implies an increase of about $105 million. That outlook sits alongside an assumed 4.2% yearly revenue growth rate and a revenue forecast of $4.3 billion in 2029, so the narrative ties together both top line expansion and higher profitability into a single earnings step up.
Uncover why A. O. Smith's fair value indicates a 24% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on A. O. Smith focuses on how far high conviction analysts lean into premium products as a catalyst. Before this news, the most optimistic group was modeling revenue reaching about US$4.4b and earnings of roughly US$646.3 million by 2029. Those projections sit well above consensus and could shift again as the North America boiler story and China pressure evolve.
Explore 4 other A. O. Smith fair value estimates, including one that suggests as much as 51% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your A. O. Smith research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for A. O. Smith. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate A. O. Smith's overall financial health at a glance.
Looking For More A. O. Smith Style Ideas?
If the A. O. Smith story has you thinking about balance sheets, cash generation and how different regions pull their weight, it makes sense to broaden the watchlist using screeners built around the same themes.
- If you want companies that combine financial resilience with low headline risk, start by scanning 31 resilient stocks with low risk scores that already clear strict balance sheet and risk checks.
- For investors who care most about getting more value for every dollar paid, filter the market using 27 high quality undervalued stocks and focus on businesses where fundamentals and pricing look out of sync.
- Income focused readers who like the idea of being paid while they wait can review 8 dividend fortresses that meet a minimum 5% yield hurdle and still aim for stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com