


Did Q3 Production Results Just Shift Fortuna Mining's (TSX:FVI) Investment Narrative?
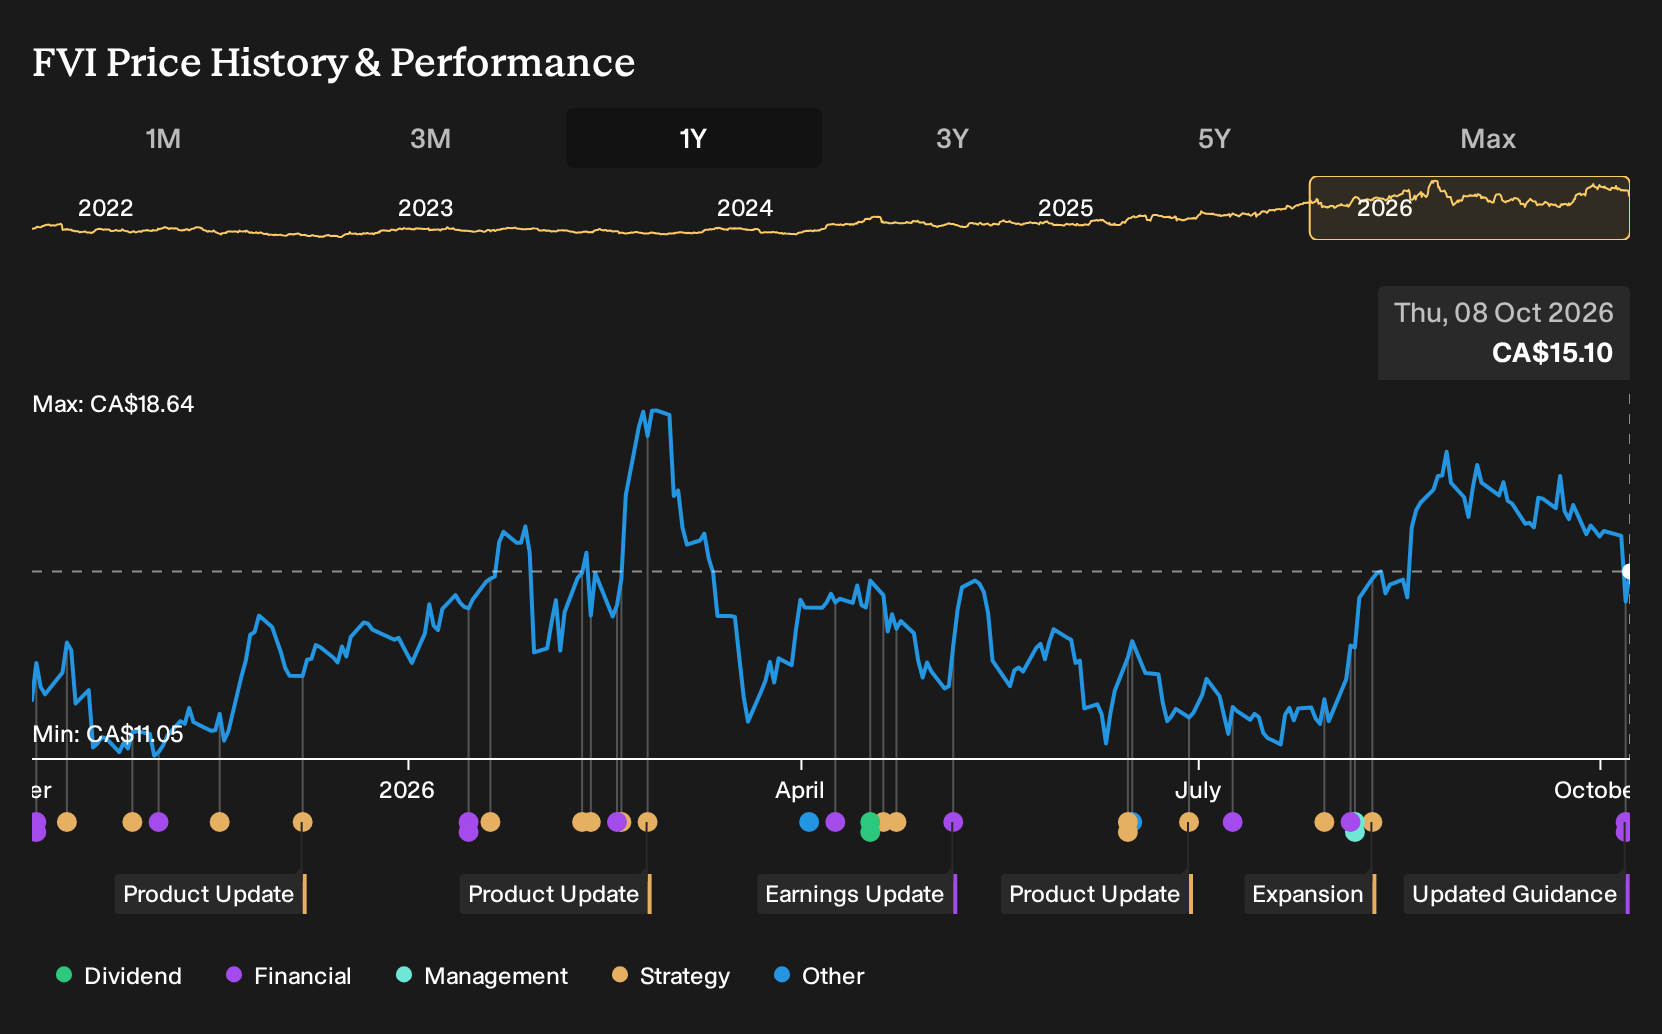
- Fortuna Mining Corp. reported third quarter 2026 production of 69,665 gold equivalent ounces and 214,754 GEO for the first nine months, and reiterated its full year production guidance range of 281,000 to 305,000 GEO.
- Management paired the guidance confirmation with plans to expand the Séguéla processing plant and the Bambadji exploration acquisition, signaling a focus on sustaining volumes while building a longer term project pipeline in West Africa.
- This article examines how Fortuna Mining's investment narrative is influenced by confirmed 2026 guidance alongside the third quarter production outcome.
Fortuna Mining Investment Narrative Recap
To own Fortuna Mining, you need to trust that a concentrated set of assets can sustain output while high all in sustaining costs are worked lower over time. The reiterated 2026 guidance of 281,000 to 305,000 gold equivalent ounces suggests management still sees the current mine plan as intact, so the short term production catalyst has not materially changed.
The bigger near term risk remains execution on a smaller portfolio after selling San Jose and Yaramoko. Any operational hiccup at core sites, permitting delay or inflation pressure on costs would hit both volumes and cash generation faster than before, given fewer producing hubs to offset issues.
The most relevant update for this picture is Fortuna Mining confirming that 2026 production guidance is still on track after reporting 69,665 gold equivalent ounces in the third quarter and 214,754 ounces for the first nine months. That combination indicates that the key operational question right now is less about growth and more about simply delivering the plan.
For catalysts, the focus is essentially on quarterly production relative to that 281,000 to 305,000 ounce range, along with any disclosure on all in sustaining costs and project execution at Séguéla and Diamba Sud. Missed tonnage or rising unit costs would feed quickly into the existing risk narrative around concentration and capital intensity.
What Analyst Forecasts Imply For Fortuna Mining
Fortuna Mining's narrative projects revenue of $2.2b and earnings of $831.5 million by 2029. That path assumes revenue growth of 22.8% per year and an earnings increase of about $453 million from $378.2 million today.
Uncover why Fortuna Mining's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community range from about 17.8 to 85.5, so views on Fortuna Mining sit on a very wide spectrum. That spread meets fresh realities. Production guidance is reaffirmed, yet higher all in sustaining costs and project concentration mean you should compare these opinions and stress test several alternative viewpoints.
Explore 4 other Fortuna Mining fair value estimates, including one that suggests it could be worth just CA$17.82.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own research and judgment.
- A great starting point for your Fortuna Mining research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fortuna Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fortuna Mining's overall financial health at a glance.
Looking For More Investment Ideas Beyond Fortuna Mining?
If Fortuna Mining has prompted you to rethink how concentrated producers fit in your portfolio, it can help to line it up against a wider set of opportunities using the Simply Wall St Screener.
- For investors who want quality at a discount, scan a curated pool of companies that currently screen as 7 high quality undervalued stocks.
- If income is your priority, focus on resilient payers by reviewing a selection of 3 dividend fortresses that aim to pair yield with balance sheet strength.
- For those who care most about capital preservation, start with a universe of 8 resilient stocks with low risk scores and compare their profiles to Fortuna Mining to see how your risk mix stacks up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com