


Should Labor Deal Ratification Require Action From Metro Stock Investors?
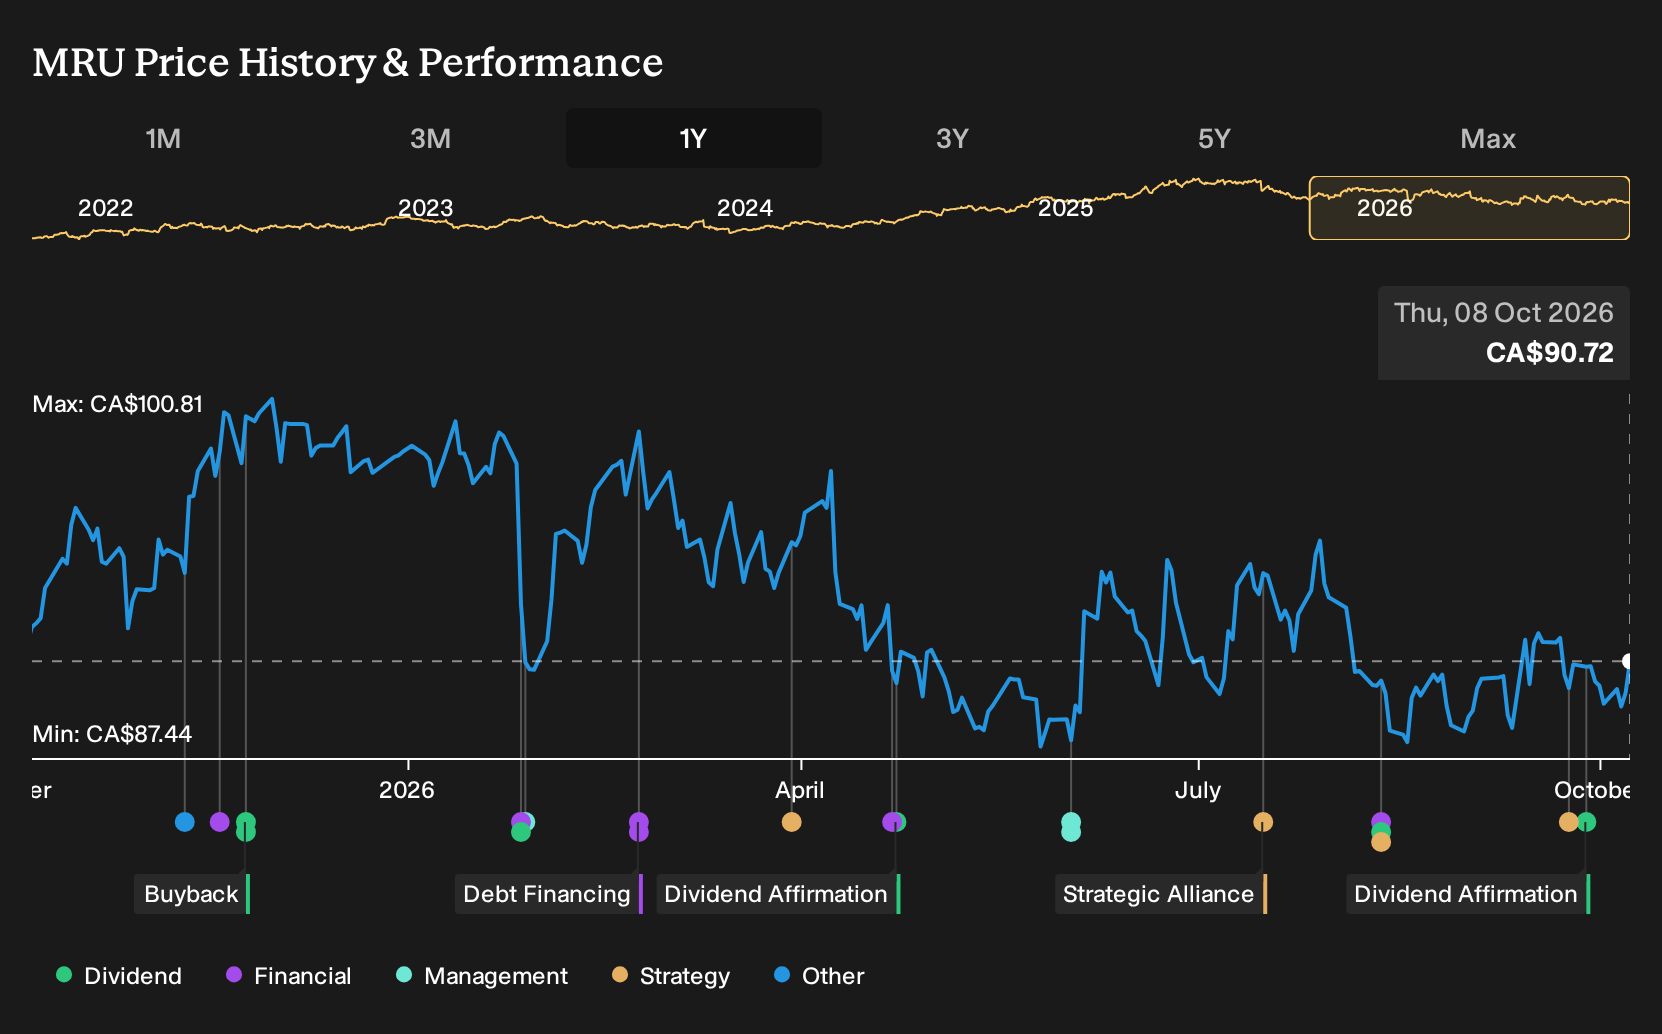
- Metro Inc. has resolved a months long labour dispute after unionized employees ratified a five and a half year collective agreement. The board also declared an unchanged quarterly dividend of $0.4075 per common share, payable on November 10, 2026, to shareholders of record on October 22, 2026.
- The long dated labour agreement gives Metro clearer visibility on wages and operating conditions, which can influence cost planning, distribution efficiency, and how confidently management pursues automation and e commerce projects.
- We will now look at how Metro's investment narrative is affected by long term labour stability from the new collective agreement.
Metro Investment Narrative Recap
For Metro, the investment case still hinges on a fairly simple belief. You want a grocery and pharmacy operator that converts everyday food and health spending into consistent cash, then feeds that back into store upgrades, automation, and a steady dividend. The new five and a half year labour deal and unchanged payout mainly reinforce that picture rather than transform it.
The key short term catalyst is the upcoming Q4 2026 earnings release, where you will see how quickly distribution operations normalize and what that means for margins after the dispute. The biggest current risk remains pressure on profitability from wage commitments, automation related SG&A, and intense discount competition in Quebec and Ontario.
The most relevant fresh datapoint is the reaffirmed quarterly dividend of CA$0.4075 per share. That decision signals that Metro’s board is comfortable keeping cash returns to shareholders steady while the business absorbs higher labour costs and continues to invest in supply chain automation and e commerce capabilities.
For you as a shareholder, the dividend affirmation connects directly to catalysts and risks. It keeps income visibility intact going into the November 18 results, yet it also raises the bar on execution. Management now needs to show that distribution efficiencies, private label strength, and growing pharmacy demand can offset competitive pricing, commodity cost pressure, and higher fixed expenses.
Metro's current analyst narrative points to CA$24.6b in revenue and CA$1.1b in earnings by 2029, based on a 3.5% yearly increase in sales and an earnings uplift of about CA$116m from the CA$983.7m reported today.
Uncover why Metro's fair value indicates an 11% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about $100 and $134 per share, so retail opinions on Metro already span a wide range. Those views were formed before the labour truce and dividend affirmation. You now need to weigh that spread against risks around discount competition, automation costs and regional concentration.
Explore another Metro fair value estimate, including one that suggests as much as 48% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Metro research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Metro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Metro's overall financial health at a glance.
Looking for more investment ideas beyond Metro?
If you want to stress test your thesis on Metro and broaden your watchlist at the same time, the Simply Wall St Screener lets you scan for other businesses with the mix of quality, income, and resilience that suits your own playbook.
- If downside protection comes first for you, you can start with a basket of resilient companies using our 8 resilient stocks with low risk scores to see which ones have historically carried lower overall risk on the fundamentals.
- If income is a key part of your plan, you can check out reliable payers by scanning the 3 dividend fortresses and seeing which stocks currently combine higher yields with a focus on stability.
- If you want to hunt for under followed opportunities, you can broaden your search to quality operators in less crowded corners of the market through the 9 high quality undiscovered gems and see what else matches your criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com