


Is Take Two Interactive Software (TTWO) Fairly Valued After Its New Xbox Deal?
Take-Two Interactive Software (TTWO) is back in focus after signing a new long-term XBOX Publisher License Agreement with Microsoft and drawing fresh attention to Grand Theft Auto 6's non AI development approach.
These announcements have landed during a mixed period for Take-Two Interactive Software’s investors, with the share price up 2.63% on the day to US$209.37 and a 7 day share price return of 2.82%. Year to date, however, the share price return is down 16.78%, while the 1 year total shareholder return is down 18.43% and the 3 year total shareholder return is up 47.84%. This suggests that recent momentum has softened even as the longer run story has remained more constructive.
Scan beyond Take-Two Interactive Software and see how other gaming and media players with solid fundamentals are setting up for the next move through our curated 20 high quality undiscovered gems.
The latest bounce in Take-Two Interactive Software sharpens the dilemma. Should investors lean into today’s reset after a weak year, or hold fire and wait in the hope that the valuation offers a cleaner entry soon?
Most Popular Narrative: 24% Undervalued
On the most followed view, Take-Two Interactive Software is worth about $276.97 per share, compared with the recent close at $209.37. That gap anchors a thesis that current pricing does not fully reflect the Grand Theft Auto 6 launch cycle and the broader content pipeline, even with recent share price weakness.
GTA V’s online ecosystem, which is now 13 years old, generated revenue for over a decade and continues to do so. If GTA VI online follows a similar trajectory, the long tail value of this single title is almost incalculable on a conventional near-term model.
See why 93 investors see Take-Two Interactive Software as 24% undervalued.
The most followed narrative, according to Clive_Thompson, builds that $276.97 fair value using a discount rate of 8.98%, along with an assumed profit margin of 12.31% and a revenue growth rate input of 47.09%. That framework leans heavily on Grand Theft Auto 6 as a multi year content engine, while still recognising Take-Two Interactive Software's broader portfolio across console, PC, and mobile titles.
There is a clear tension inside this narrative. On one side, analysts in aggregate see scope for the share price to move higher from here, with the price target cited in the data set at $286.44. On the other, the internal Simply Wall St fair value model is far more measured, with the stock only trading about 1.4% below that estimate. The author emphasises that the upcoming release and its online ecosystem could reshape the financial profile for years, which is what drives the much larger 24.4% discount to fair value in this storyline.
Investors weighing this narrative against the latest trading data can see how it tries to reconcile a few conflicting signals. The share price is down 18.43% on a 1 year total return basis yet up 47.84% over 3 years, revenue in the company data is $6.69b, and the group is still reporting a net loss of $320.4m. The argument is that these mixed signals reflect a business in transition, where current GAAP profitability and recent share returns sit uncomfortably beside expectations for earnings to move materially higher over the next few years as major titles land.
That disconnect is also visible in how different valuation lenses treat Take-Two Interactive Software. The narrative pegs fair value at $276.97 with a strong upside skew, while the SWS DCF output in the statements section marks the stock only slightly below a future cash flow value of $212.27, and the internal fair value summary describes it as trading at 1.4% below that mark. The narrative effectively asserts that conventional cash flow and current loss making status struggle to capture the potential long tail from GTA VI and the mobile portfolio, which is why it points to a far wider discount.
For readers trying to make sense of this spread, the key is to separate what is present in current accounts from what is embedded as expectation. Today, Take-Two Interactive Software is unprofitable, carries a negative return on equity of 8.88%, and has a value score of 2, while also operating a diversified set of franchises and a seasoned management team and board. The popular narrative leans into that combination and assigns a premium to the idea that upcoming launches and recurring in game spending will eventually validate a higher valuation than either the current share price or the more conservative DCF output might imply.
Result: Fair Value of $276.97 (UNDERVALUED)
Still, the fair value gap can close quickly if Grand Theft Auto 6 underwhelms or if Take-Two Interactive Software continues to post net losses.
Find out about the key risks to this Take-Two Interactive Software narrative.
Another View: What Multiples Say About Take-Two Interactive Software
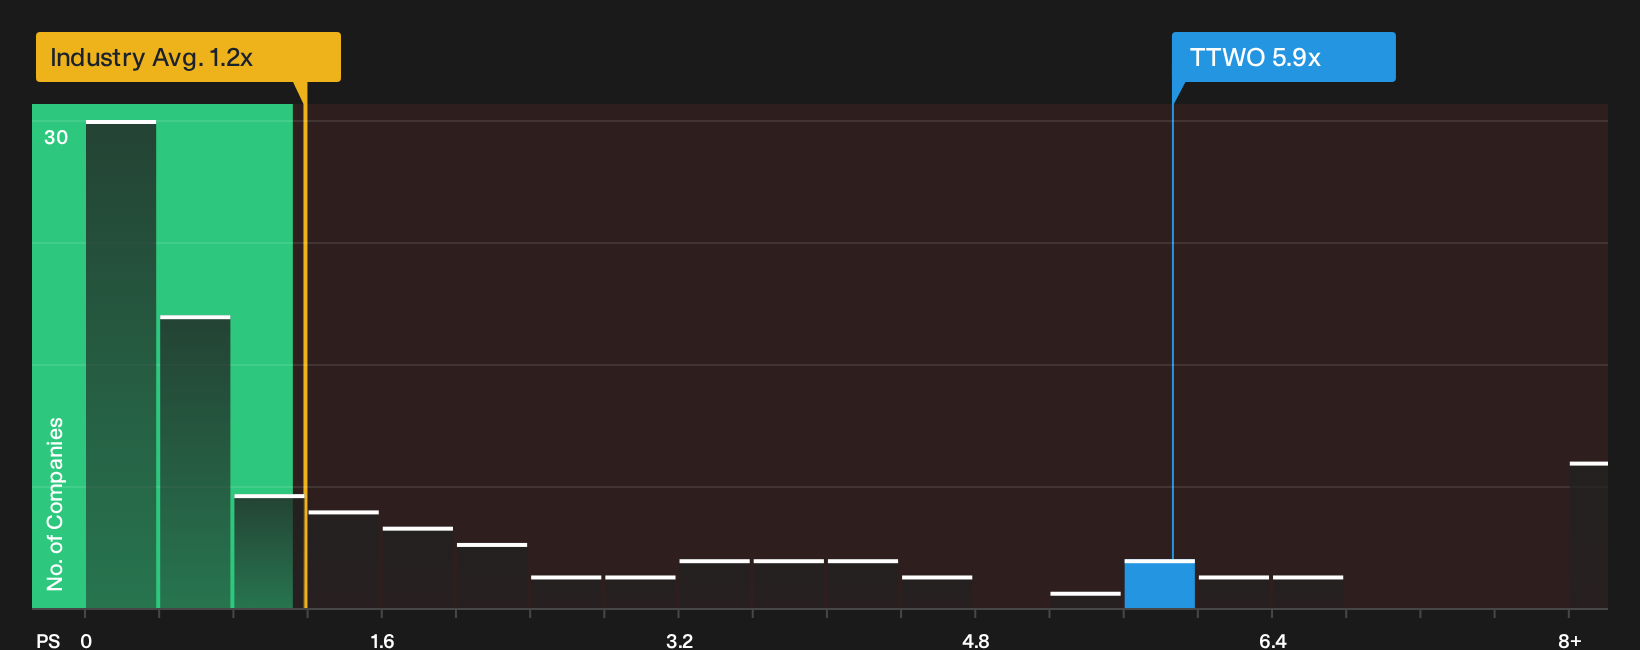
There is a very different message when you look at Take-Two Interactive Software through its P/S ratio. The stock trades at 5.9x sales, compared with 2.3x for peers and 1.2x for the wider US Entertainment group, while the fair ratio sits at 3.5x. That gap points to meaningful valuation risk if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or clear message? Either way, move quickly to review the full data set, weigh both the concern and the optimism, then ground your own decision in the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Take-Two Interactive Software?
Do not stop with Take-Two Interactive Software. The same tools that surface this narrative can help you uncover other opportunities that fit your own playbook and risk tolerance.
- Target steady wealth building by scanning companies that combine quality fundamentals with attractive pricing through the 26 high quality undervalued stocks.
- Prioritise sleep at night stability and focus on businesses with stronger balance sheets and healthier financial profiles using the list of solid balance sheet and fundamentals (25 results).
- Spot potential mispriced stories early and review a curated pool of fundamentally robust smaller players through the 11 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com