


Target Hospitality (TH) Could Be 27% Undervalued Following Its Recent Pullback
Target Hospitality (TH) has drawn fresh attention after recent share price swings, with the stock roughly flat over the past 3 months but showing sizable gains year to date. Investors are weighing that move against current fundamentals.
Recent trading has cooled, with a 7 day share price return down 10.5% and a 30 day share price return down 9.5%. This contrasts with Target Hospitality’s year to date share price return of 126.3% and 1 year total shareholder return of 140.9%, which indicates stronger longer term momentum despite short term profit taking and changing risk appetite around the company.
Compare Target Hospitality’s sharp year to date move with a curated 20 high quality undiscovered gems that may be earlier in their rerating journey.
Target Hospitality’s sharp rise over the past year now runs into a spell of softer trading, which raises a simple tension. Are investors rethinking the story, or has sentiment drifted away from what the business is worth?
Most Popular Narrative: 27.3% Undervalued
Target Hospitality’s most followed narrative puts fair value at $25.20 per share, comfortably above the recent $18.33 close. This frames the recent pullback as a question of patience rather than a broken story.
Heavy WHS focused capital spending of about US$490m to US$510m in 2026, supported by customer advances and a larger US$660m credit facility, is front loaded into the current build phase and could leave Target Hospitality with a larger revenue producing asset base while growth capex is expected to slow after 2026.
See why 2 investors see Target Hospitality as 27% undervalued.
Result: Fair Value of $25.20 (UNDERVALUED)
Still, the heavy WHS capex plan and the recent net loss underline a simple risk for Target Hospitality if new contracts or utilisation fall short of expectations.
Find out about the key risks to this Target Hospitality narrative.
Another View on Target Hospitality’s Valuation
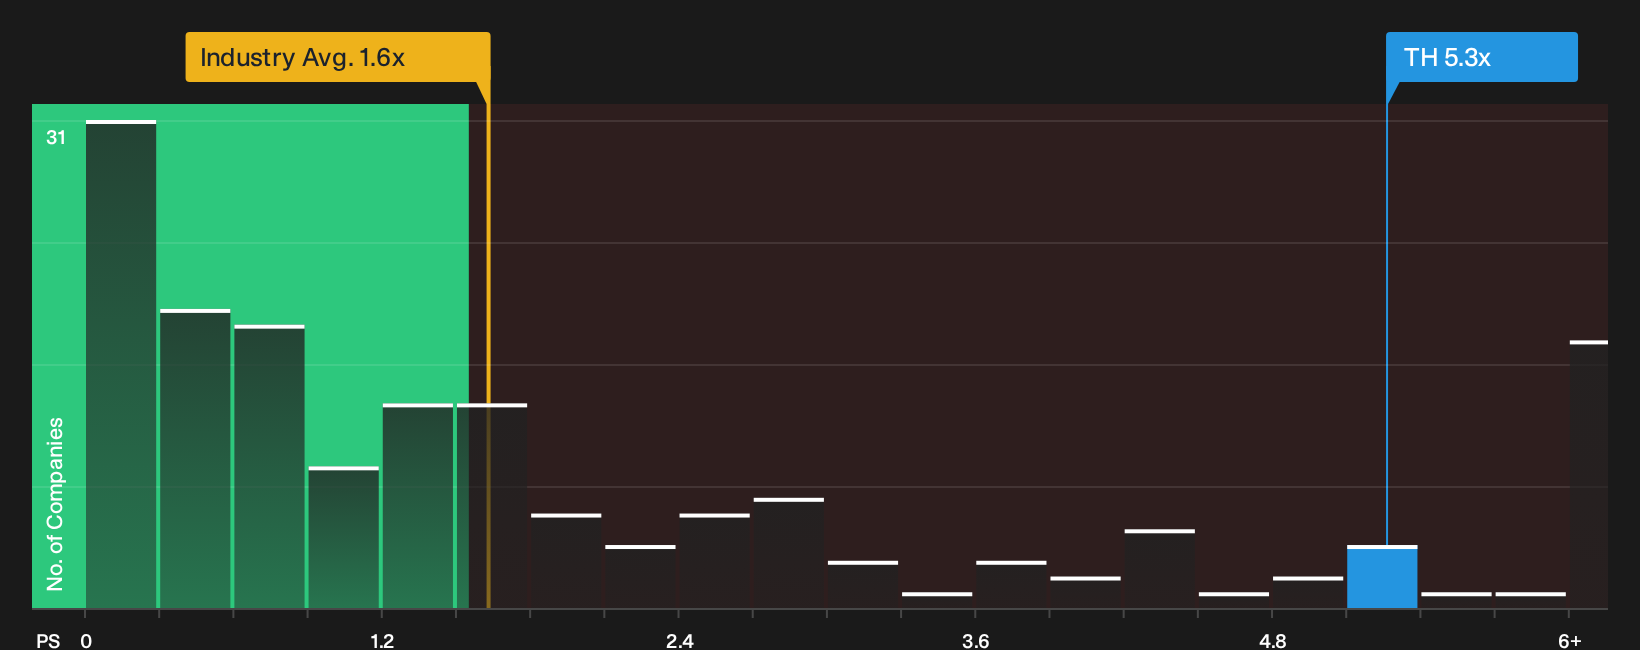
The story around Target Hospitality looks very different once the price tag is measured against its sales. The stock trades on a P/S ratio of 5.3x, compared with 1.6x for the wider US Hospitality industry and 1.3x for peers. The fair ratio is 3.3x, which points to a richer tag and raises the question of how much future execution risk you are comfortable paying for.
For a deeper breakdown of what that pricing gap could mean in practice, have a look at See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Target Hospitality is clearly split, so it helps to move fast and test the story against your own thresholds. To weigh those positives for yourself, start by checking the 3 key rewards.
Looking for more investment ideas beyond Target Hospitality?
If Target Hospitality has sharpened your focus on where capital goes next, do not stop here. Fresh opportunities often show up where you are not currently looking.
- Target fresh upside potential by scanning a 12 elite penny stocks with strong financials that filters for smaller companies with stronger balance sheets and real businesses behind the ticker.
- Prioritise quality and price together by running through a 28 high quality undervalued stocks that highlights financially solid companies trading on cheaper metrics than their fundamentals might suggest.
- Steady your portfolio with a 8 dividend fortresses that focuses on income ideas offering higher yields backed by underlying cash generation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com