


Ingram Micro Holding (INGM) Just Gave Investors Something To Think About
Why the Opengear distribution deal matters for Ingram Micro Holding
Ingram Micro Holding (INGM) just secured a pan European distribution agreement with Opengear, expanding access to network resilience products for resellers and end users across multiple additional markets.
The deal broadens Ingram Micro Holding’s reach beyond existing Opengear territories such as the UK, Ireland, Spain, Germany, Italy, France, Belgium and Luxembourg, and into countries including Switzerland, Hungary and the Czech Republic.
Recent trading tells a mixed story for Ingram Micro Holding. The share price has eased over shorter windows, with the 30 day share price return down 2.75% and the 90 day share price return down 5.02%. However, the year to date share price return of 29.52% and 1 year total shareholder return of 28.99% still point to solid underlying momentum around the US$27.60 level as investors weigh news like the Opengear agreement against earlier concerns about growth and cash generation.
Scan 20 high quality undiscovered gems that share Ingram Micro Holding's role in critical tech infrastructure but may still be flying under most investors' radar.Ingram Micro Holding looks like a vital plumbing business for global IT, and the Opengear deal underlines that role. The real question now is whether US$27.60 already reflects that strength.
Most Popular Narrative: 17% Undervalued
Ingram Micro Holding closed at $27.60, while the most followed narrative pegs fair value closer to $33.17, so the gap between price and story is already clear before looking at what is driving it.
Expanding AI centric GPU, server and storage demand, even at lower unit margins, positions Ingram Micro at the center of next generation infrastructure spending. This is expected to support top line growth and drive returns on invested capital that align with long term earnings expansion.
See why 1 investors see Ingram Micro Holding as 17% undervalued.
The narrative uses a 10.74% discount rate and blends together assumptions for revenue, earnings and margins, then arrives at a fair value estimate of $33.17, which sits above both the current $27.60 price and the $32.62 analyst target. The implied upside in that framework leans heavily on AI infrastructure demand, earnings of $678.6 million by around 2029, and a P/E of 14.5x on those future profits, which is below the 31.6x multiple applied to the wider US Electronic industry in the same dataset.
This view also assumes revenue can rise from $55.98b today to $61.4b, while profit margins shift from 0.8% to 1.1%. As a result, the thesis is sensitive to relatively small changes in execution, mix and working capital. For anyone weighing the Opengear agreement and similar deals, the key question is how much they help close that gap between current margins and the profitability baked into the most popular narrative.
Result: Fair Value of $33.17 (UNDERVALUED)
Still, the Ingram Micro Holding story could be knocked off course if low margin GPU and server deals crowd out higher margin work, or if elevated working capital needs start to squeeze cash generation.
Find out about the key risks to this Ingram Micro Holding narrative.
Another View: Cash Flow Paints A Tougher Picture For Ingram Micro Holding
The popular narrative around Ingram Micro Holding leans on earnings, margins and P/E comparisons to argue the stock looks undervalued. A different lens tells a cooler story. The SWS DCF model, which values the business on future cash flows, points to a fair value of about $17.35, well below the current $27.60 price. This raises the question of whether earnings based optimism is running ahead of the cash actually coming through the door.
Look into how the SWS DCF model arrives at its fair value.
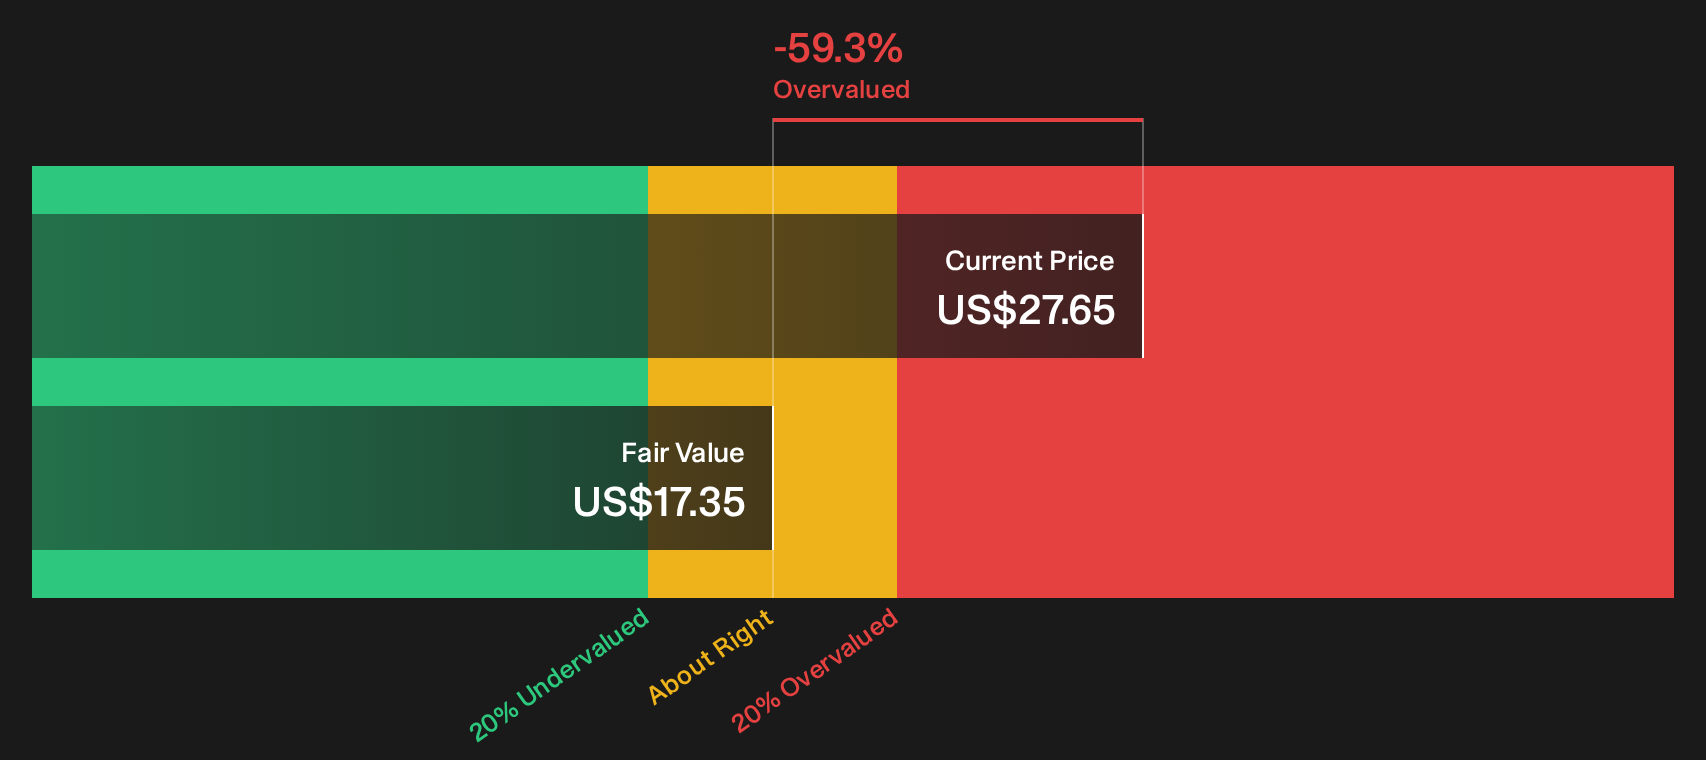
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ingram Micro Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty in this article points in different directions, which is exactly why you should move quickly and weigh the full mix of risk and upside for Ingram Micro Holding. To pressure test that view against the data, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Ingram Micro Holding?
If Ingram Micro Holding has sharpened your thinking, do not stop here. Fresh ideas often come from comparing quality, risk and income across very different businesses.
- Target reliable compounding by scanning companies with steady fundamentals and conservative balance sheets through the 31 resilient stocks with low risk scores.
- Hunt for mispriced quality by focusing on businesses where fundamentals and valuation look out of sync using the 28 high quality undervalued stocks.
- Strengthen your watchlist with firms that pair durable finances with clean balance sheets using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com