


3 Australian Dividend Stocks With Yields Over 4%
Powerful AI demand is reshaping global trade, with shipments of AI related hardware helping to keep goods flowing even as conflicts and tariffs bite. That kind of resilience has investors hunting for reliable income from Australian dividend stocks that do not depend on perfect economic conditions. This article walks through three higher yielding dividend payers from a quality focused 3%+ income screen that may appeal to long term income seekers.
The dividend ideas covered next are only a small sample, with the wider screen surfacing 36 more income focused companies with equally compelling stories that are not unpacked here. To see the full Dividend Powerhouses list, identify opportunities that fit your own risk profile, and analyze payout strength directly in the Dividend Powerhouses (3%+ Yield) screener.
Medibank Private (ASX:MPL)
Overview: Medibank Private is an Australian insurer that earns recurring premiums from private hospital and ancillary health cover under its Medibank and ahm brands, with additional health services and smaller insurance products supporting this core dividend focused engine.
Operations: Medibank generates about A$8.6b of revenue from Health Insurance and A$635m from Medibank Health, almost entirely within Australia.
Market Cap: A$12.6b
Medibank Private taps into the Dividend Powerhouses theme through a health insurance franchise built on regular premium income that can underpin a consistent payout profile, even as healthcare habits shift toward new models of care.
"The expansion and scaling of primary care clinics, virtual health, and home care offerings position Medibank to benefit from the shift in consumer preferences toward preventative care and at-home healthcare, helping to differentiate its offering, limit claims inflation, and improve net margins."
What happens to Medibank’s income story if one unseen pressure quietly squeezes those margins investors are banking on?
If that pressure worries you, read the full narrative for Medibank Private to see how Medibank Private’s income engine could absorb shocks while keeping dividends front and center.

Monadelphous Group (ASX:MND)
Overview: Monadelphous Group is an engineering contractor that builds and maintains large resources, energy, renewable power, and infrastructure projects across Australia and nearby regions.
Operations: Monadelphous Group generates about A$1.4b from Engineering Construction and A$1.6b from Maintenance and Industrial Services, mainly in Australia.
Market Cap: A$3.1b
For income investors, Monadelphous Group matters because its construction and maintenance work on long-lived energy and infrastructure assets can support the kind of recurring earnings that help keep a 3%+ dividend yield covered when conditions get bumpy.
"Accelerating investment in decarbonisation and renewable energy infrastructure is now translating into tangible contract wins and a growing pipeline, as evidenced by record awards secured by Zenviron and new high-voltage services capability."
The next test for Monadelphous Group’s dividend appeal is how tight funding and balance sheet pressure play out against that project backlog.
That funding squeeze is exactly why reading the full narrative for Monadelphous Group can be useful, as it unpacks how Monadelphous Group could turn that pressure into accelerating contract strength.

nib holdings (ASX:NHF)
Overview: nib holdings is an Australian insurer that earns recurring premiums from private health cover for local residents, plus international, New Zealand, travel and health services businesses that add diversification around this dividend focused engine.
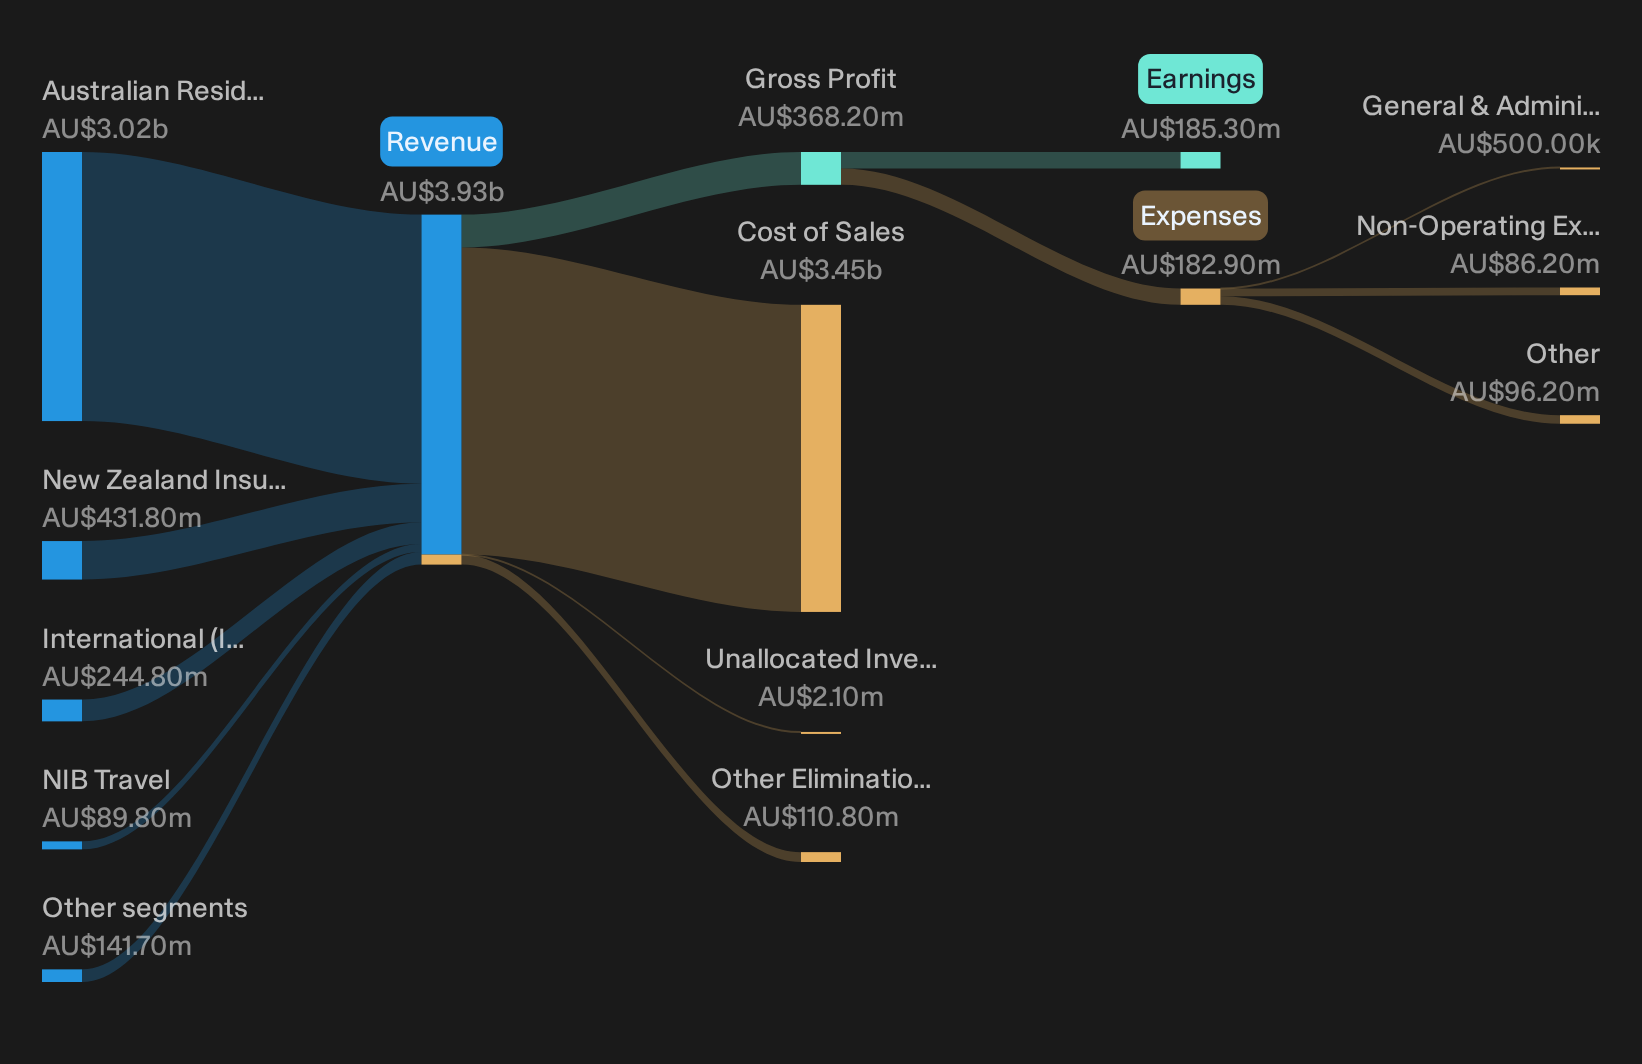
Operations: nib holdings generates about A$3.0b from Australian Residents Health Insurance, A$432 million from New Zealand, A$245 million from International, and smaller travel, Thrive and health services lines.
Market Cap: A$3.2b
nib holdings matters for this Dividend Powerhouses screen because regular health insurance premiums from Australian residents give the payout story a steady foundation, even as the group experiments with newer digital and service lines around it.
"Expansion of health management and preventative care offerings (telehealth, wellbeing programs, in-home care, no/known gap networks) is broadening revenue streams, improving customer retention, and actively managing claims inflation, which is positively impacting both top-line growth and future claims ratios."
The real dividend test for nib holdings now hinges on how one subtle shift in funding and cash earnings quality influences future margin support.
That funding shift is exactly why reading the full narrative for nib holdings now can highlight where nib holdings’ margins might quietly be strengthening and where risks could be masking upside.
Seeking Fresh Alternatives Beyond Dividends?
New ideas move first. Capital chases momentum while signals are still fresh and quiet. Do not get caught watching others act while you hesitate. Consider acting early when appropriate for your strategy.
- Track resilient operators tied to the energy transition by scanning the curated 16 nuclear energy infrastructure stocks and identify infrastructure plays while potential opportunities are still accessible.
- Target cash generative miners by running the focused 35 elite gold producer stocks and identify established producers before changes in market attention affect valuations.
- Focus on financially solid opportunities using the curated list of solid balance sheet and fundamentals (12 results) to filter for sturdy balance sheets while these businesses may still be less widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com