


IES Holdings (IESC) Tests Its DBM Global Bet As Valuation Debate Heats Up
IES Holdings (IESC) just expanded its financing firepower by amending its credit agreements to lift total borrowing capacity to US$700 million and to close the DBM Global acquisition using a mix of cash, stock, and new debt.
That financing move comes amid volatile trading for IES Holdings, with the share price down 9.66% over the past day and weaker over the past month and quarter. However, the stock still shows a 51.79% year-to-date share price gain and a very large 5-year total shareholder return, indicating that long-term momentum remains strong even as the market reassesses near-term risk around the DBM Global deal.
Scan how IES Holdings compares to peers tapping fresh credit and acquisition-driven growth stories by reviewing the hand-picked list of solid balance sheet and fundamentals (25 results) for potential next ideas in your watchlist.
After a sharp run and a fresh US$700 million credit line tied to DBM Global, the debate now is simple. Is most of IES Holdings’ upside already in the rear-view mirror, or still ahead when you crunch the valuation next?
Most Popular Narrative: 22% Undervalued
At a last close of $308.83, the most followed valuation narrative on IES Holdings points to a fair value of $397.93, which presents the DBM Global acquisition as a key swing factor rather than a side story.
IES is well positioned to continue making a healthy impact within its sector due to the continued demand for hyperscaling datacenter construction. The financial risk is real and is more heavily tied to the semiconductor and AI boom; however, the near term demand displayed in their backlog projects a "Fair Value" of $567.75 based upon a 25.52x 5-year CAGR, a 12.3% Net Profit Margin (TTM) and future PE of 25.52x.
See why 1 investors see IES Holdings as 22% undervalued.
Result: Fair Value of $397.93 (UNDERVALUED)
However, this depends on IES Holdings managing concentration in data center projects and the added complexity from DBM Global without eroding margins or cash generation.
Find out about the key risks to this IES Holdings narrative.
Another View: DCF Flags IES Holdings As Overvalued
There is a very different message when you switch from the narrative fair value on IES Holdings to the SWS DCF model. On this framework, IESC at $308.83 sits above an estimated future cash flow value of $260.87, which frames the stock as overvalued rather than discounted. That raises a blunt question for investors: Is the excitement around data centers and DBM Global running ahead of what the cash flows currently support?
For readers who want to see how this cash flow based view is built line by line, it is worth going through the full calculation in the Look into how the SWS DCF model arrives at its fair value..
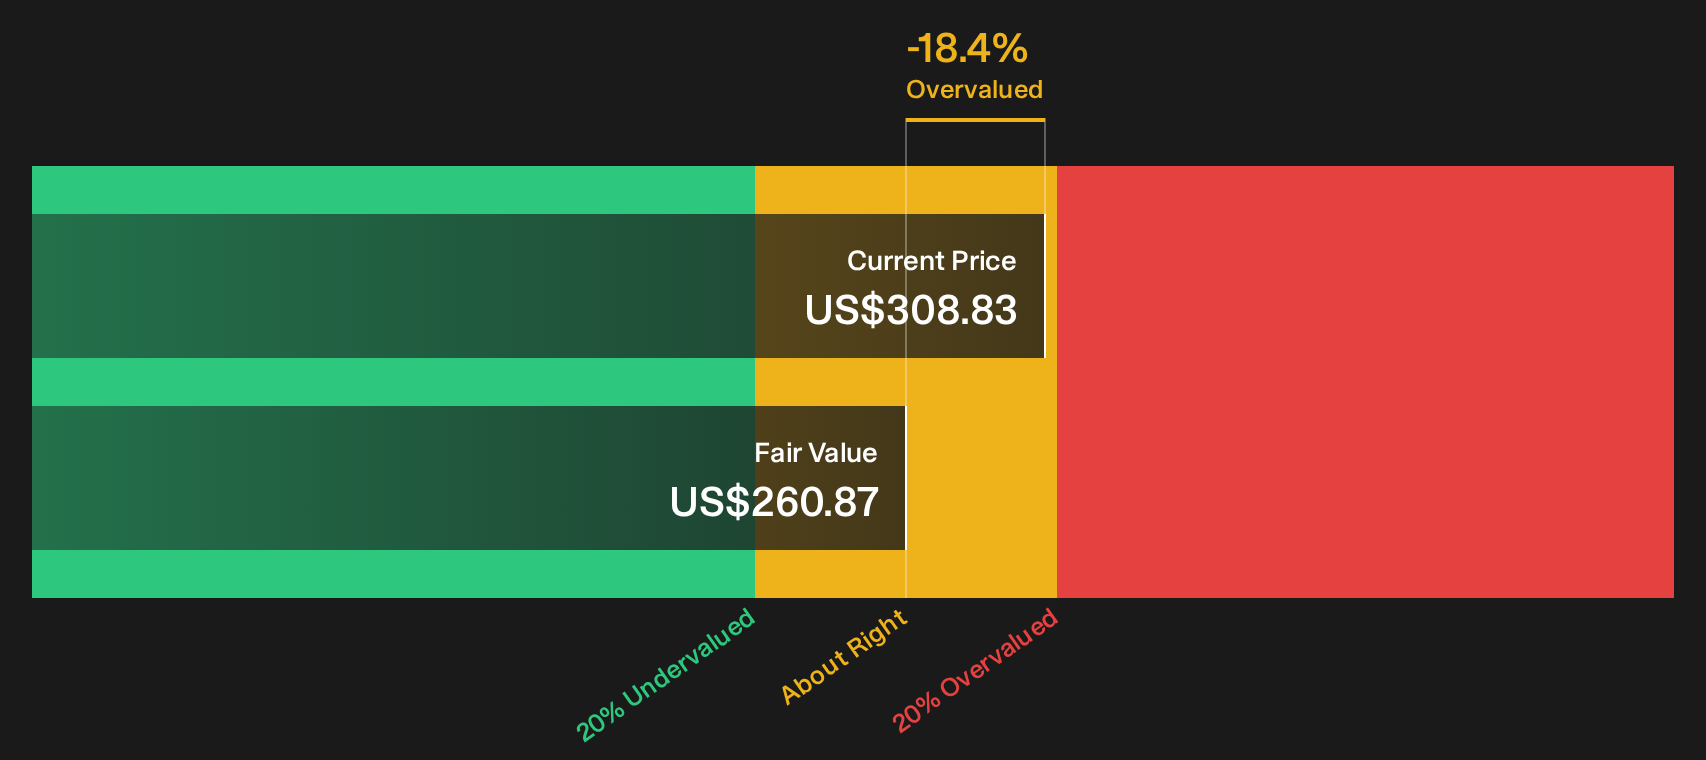
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out IES Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Reading through the split views on IES Holdings, the real edge comes from testing the numbers yourself and deciding how much risk feels acceptable for your portfolio. If you want a concise snapshot of both caution and optimism baked into current metrics, start with the 4 key rewards and 2 important warning signs.
Looking for more IES Holdings ideas beyond this headline?
If you stop with IES Holdings, you risk missing other stocks that fit your style, your timeframe, and your comfort with risk and reward.
- Target potential mispricing by scanning companies flagged as high quality yet out of favor through the 29 high quality undervalued stocks.
- Prioritize income and resilience by reviewing a curated set of reliable payers in the 8 dividend fortresses.
- Lean toward capital preservation by focusing on sturdier balance sheets and fundamentals via the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com