


Glory (TSE:6457), What Is Behind The Fresh Attention Today?
Glory (TSE:6457) has just wrapped up a sizeable buyback, completing the repurchase of 1,383,000 shares, or 2.58% of its equity, for ¥5,869.06 million under its May 2026 program.
Glory’s buyback lands on a share price of ¥4,522, with the stock posting a 12.01% year to date share price return and a 27.43% total shareholder return over one year, indicating that momentum has been building rather than fading.
Scan how Glory’s buyback momentum compares with other firms returning cash to shareholders by reviewing the hand picked 32 dividend fortresses in today's market.
Glory has already rewarded shareholders with a buyback and strong recent returns, yet the shares still trade at what some models flag as a 26.5% discount to intrinsic value. Is most of the upside already realized, or is it not yet priced in?
Preferred P/E of 13.8x: Is it justified for Glory?
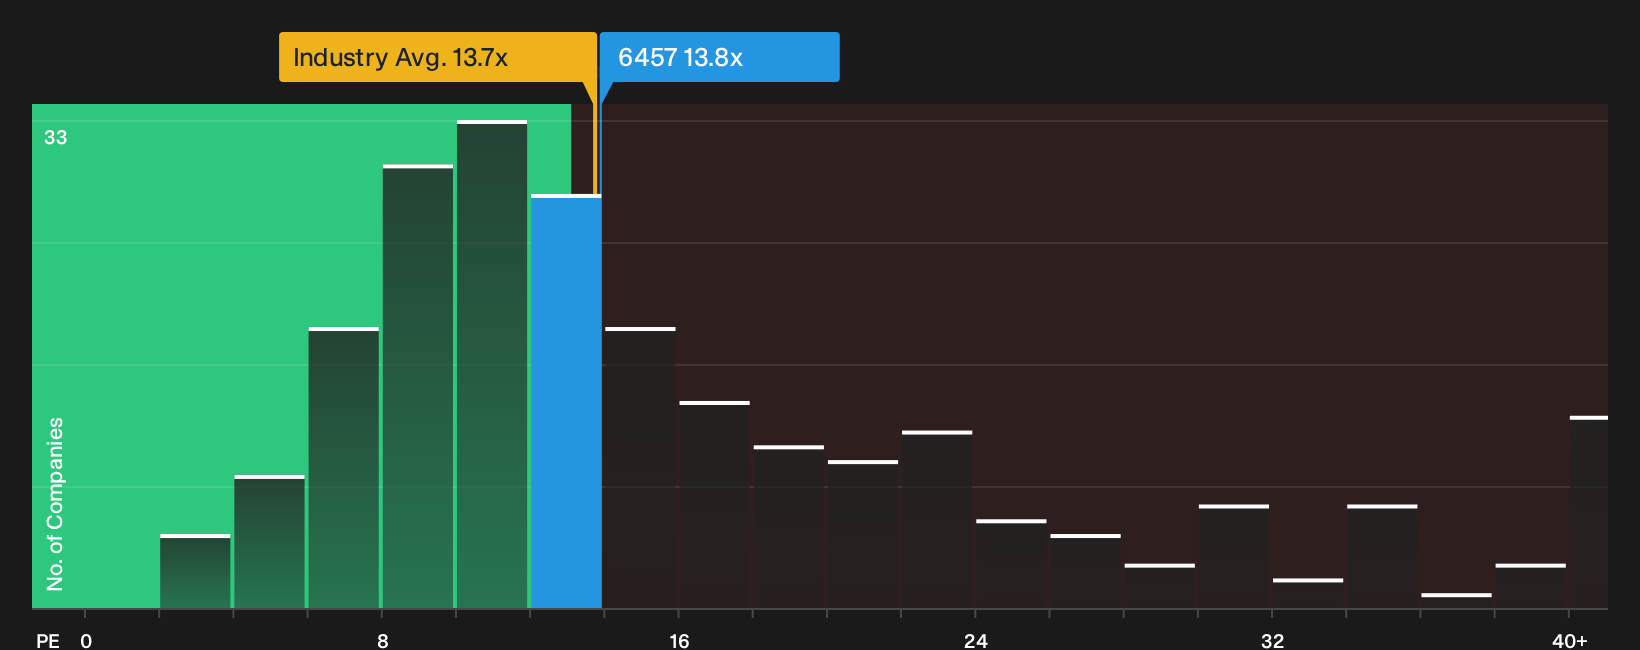
On one side, Glory is trading at a 26.5% discount to an estimated fair value based on future cash flows, with the SWS DCF model pointing to a fair value of ¥6,153.43 against a last close of ¥4,522. On the other side, the stock changes hands at a P/E of 13.8x, which only marginally trails peers and sits slightly above the wider JP Machinery industry.
The P/E ratio compares the share price with earnings per share, so it effectively reflects how much investors are paying for each unit of profit. For a business like Glory that reports high quality earnings and profit growth of 25.1% per year over the past 5 years, a mid-teens multiple suggests the market is pricing in steady, but not aggressive, expectations.
Compared with similar companies, 13.8x is a touch cheaper than the peer average P/E of 14.3x. This implies the market is applying a small discount versus close competitors. Set against the JP Machinery industry though, the multiple sits slightly higher than the 13.7x sector average, so investors are still paying a bit more than the wider group even with the DCF suggesting a 26.5% markdown to intrinsic value.
Explore the SWS fair ratio for Glory.
Result: Price-to-earnings of 13.8x (ABOUT RIGHT)
Still, the story around Glory can change quickly if demand for cash handling equipment weakens faster than expected or if overseas segments struggle to sustain recent revenue growth.
Find out about the key risks to this Glory narrative.
Another View On Glory’s Valuation
A second lens tells a different story. The fair ratio for Glory’s P/E sits at 13.6x, only slightly below the actual 13.8x. That tiny gap suggests less of a clear bargain and more of a finely balanced pricing question for anyone weighing fresh capital.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Glory for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Glory’s value and risks make this a decision point. Move quickly to review the full picture and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Glory?
If Glory has you thinking about what else might be sitting in plain sight, this is the moment to widen your search before the next move happens without you.
- Target steady compounding by reviewing proven income payers through the 32 dividend fortresses, which is built to spotlight higher yielding candidates.
- Hunt for quality at a potential markdown by scanning the 14 high quality undervalued stocks, which filters for fundamentals first and price second.
- Stack the odds toward resilience by checking the 22 resilient stocks with low risk scores, which focuses on sturdier balance sheets and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com