


What Carrefour Doubters Got Wrong
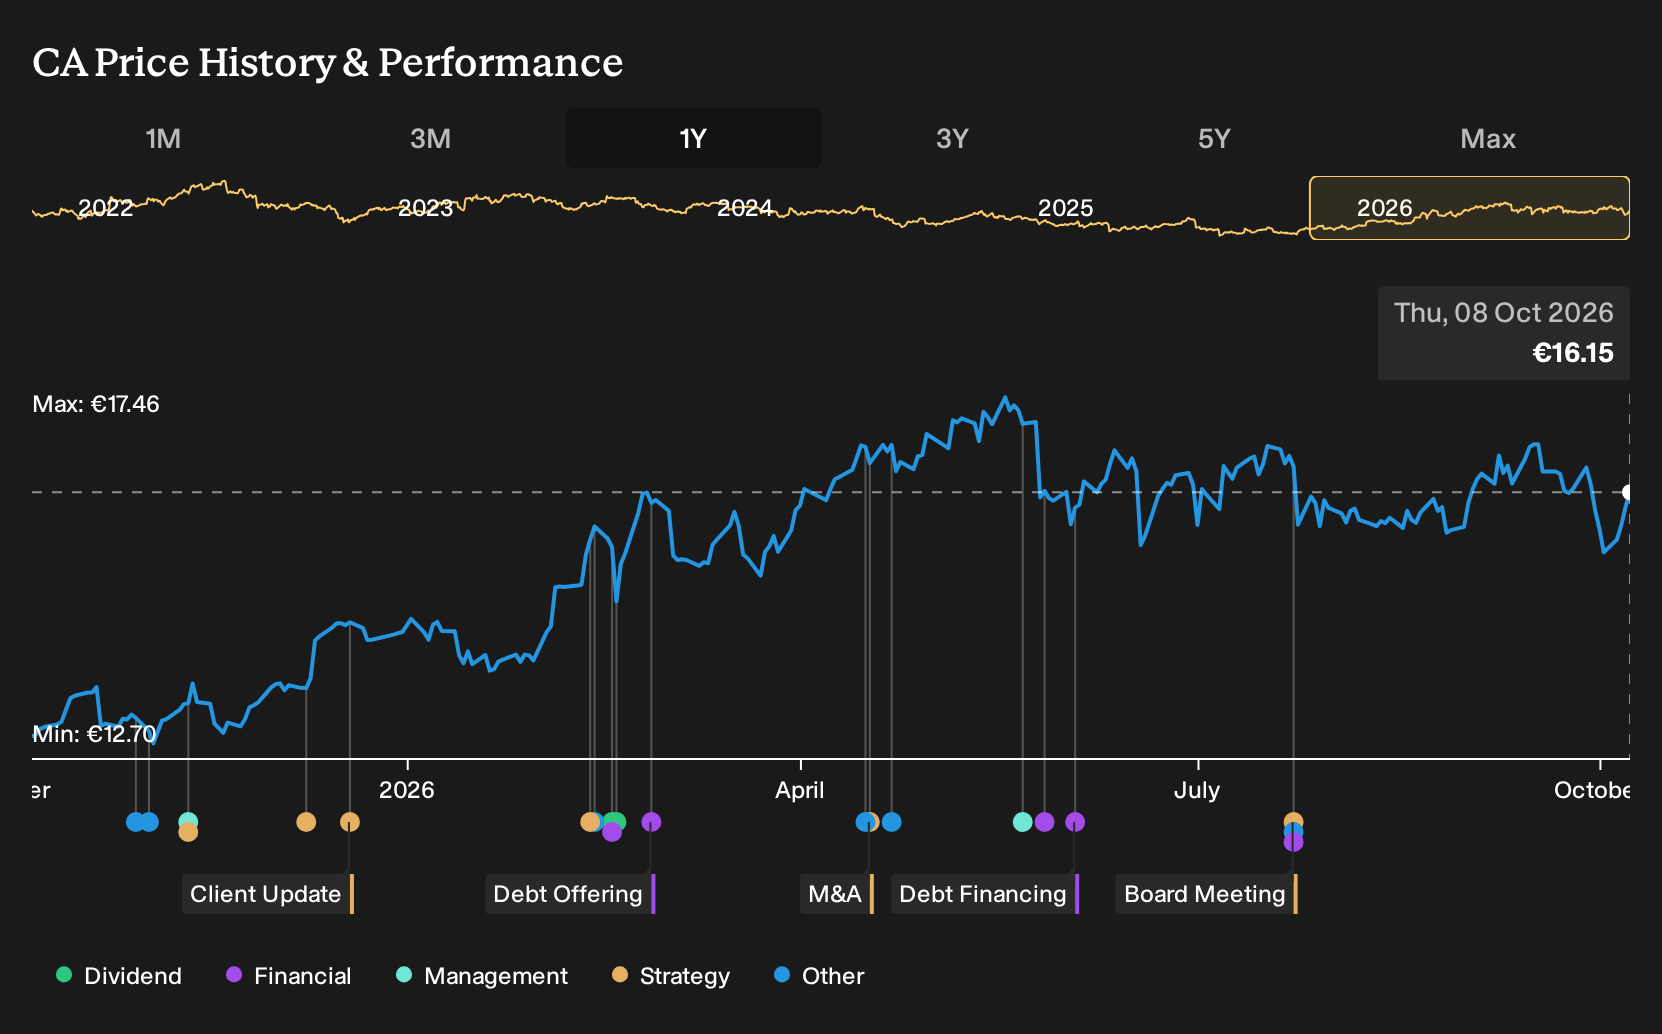
Carrefour’s return to India with a flagship store in Greater Noida, backed by local supplier agreements and an omnichannel set up, gave investors a fresh, concrete project to watch. Holding Carrefour over the past year would have returned 34.5%, including dividends. If you had been weighing a purchase back on 8 October 2025, what would you have needed to believe about this retailer’s footprint, margins, and capital choices for that outcome to feel reasonable?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Carrefour has already moved. See which of 182 high quality undervalued stocks still trade below our estimates.
The Two Carrefour Stories Investors Were Arguing About
The shares cost €12.81 at the start of the period, and you were choosing between two very different stories about where Carrefour might be heading.
On the optimistic side, the Fair Value was set at €13.98, built on revenue growth of 0.1% and a profit margin assumption of 1.0%. This view leaned on Carrefour’s push into digital transformation and e-commerce as a route to better efficiency.
The cautious view pinned Fair Value at €9 and focused on structural threats in Europe. That case revolved around aging demographics, high operating costs, and the risk that only limited gains from online efforts would reach earnings.
What The Results Changed For The Carrefour Debate
Carrefour’s return to India through the Greater Noida flagship, backed by local suppliers and an omnichannel set up, supported the optimistic story about footprint quality and format mix. The half year 2026 report pulled the other way. Revenue moved from €39,518m to €40,298m, while net income eased from €188m to €122m and margin slipped from 0.5% to 0.3%, so the evidence cut both ways.
The core assumption investors needed to test was margin resilience. For a different retailer, you would track net income and net margin beside new market openings and format shifts, then ask whether each expansion phase coincides with fatter, stable, or thinner profitability.
What You Would Be Paying For Today With Carrefour
Carrefour now trades at €16.15 after a 34.5% gain over the past year. The selected Narrative’s Fair Value sits below the current price, which means it treats today's level as demanding for the business plan baked into Carrefour 2030.
The Narrative focuses on whether cost savings, AI spending and portfolio pruning can consistently support operating margin and cash generation. A buyer today needs to judge if Carrefour can keep hitting its 3.5% margin and free cash flow aims while handling weaker markets and tighter regulatory scrutiny.
"The main thing that has to go right is that Carrefour converts its Carrefour 2030 plan, including cost savings, digital and AI roll out and portfolio pruning, into sustained operating margin and cash generation while managing weaker markets such as Poland and Argentina."
The price and this Narrative do not agree. → Uncover what this Narrative says Carrefour is actually worth
Another Way To Read Carrefour
Carrefour’s push into omnichannel retail raises a direct question for you. What happens when that customer expects the same seamless experience everywhere?
One large competitor is betting that loyalty apps, data tools and online marketplaces keep shoppers engaged. It is trying to connect food, pharmacy and general merchandise into one routine.
The emphasis shifts from new stores to digital stickiness. Health, sustainability and own-label ranges become reasons to remain inside that ecosystem.
If blending efficient supply chains with heavy tech spending succeeds, the supermarket’s role changes. You are no longer just buying groceries.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 18% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com